
5
#000000
#FFFFFF
To donate by check, phone, or other method, see our More Ways to Give page.
Donald Trump loves to put his name on things, and when it comes to the recent burst of inflation, it’s totally deserved. Trump and Republican politicians are doing their best to try to make a simple story complicated. But there is no doubt that Trump is the lead and almost sole author of the inflation we are now seeing.
Just to quickly clear away the stupid: We did have a large burst of inflation under Biden, just like the rest of the world. We were hit with a worldwide pandemic in Trump’s first term, which he apparently can’t remember. The pandemic led to a massive fall in output in 2020, while Trump was president.
When Biden took office in January of 2021, we were still down more than 10 million jobs from the pre-pandemic level. Biden’s recovery package quickly got back the lost jobs and got the unemployment rate down to 4.0 percent by the end of the year, far faster than anyone expected.
The reopening of the economy from the pandemic recession led to a burst of inflation in the United States, as it did in Germany, France, and everywhere else. Suddenly people were buying lots of things, and it took a while for businesses to ramp up production.
If Biden had cared less about getting people back to work, the recovery package could have been smaller, and the peak inflation rate might have been 1-2 percentage points lower. But the important part of the story is that inflation quickly came down.
Year-over-year inflation peaked at 9.0 percent in June of 2022. A year later, it was down to 3.1 percent. It was down to 2.6 percent by the election in November of 2024. Inflation was generally expected to continue to fall and to be at or near the Fed’s 2.0 percent target by the end of 2025.
But then Trump turned everything around. Inflation began to rise even before he took office, as households and businesses stocked up on imported goods in anticipation of Trump tariffs. Durable goods prices, which had been falling since early 2023, stopped falling and began to rise. The Consumer Price Index also stopped falling and started to rise. Year-over-year inflation hit 3.0 percent in September 2025 but then slowed to 2.7 percent by the end of the year.
It likely would have continued to slow through 2026. After all, Trump’s tariffs were primarily a one-time event. If he didn’t keep imposing new ones (a big “if”), it was reasonable to think that inflation would settle back down to its pre-tariff pace.
But we never got to test that theory. Trump decided to go to war with Iran at the end of February. As we all know, the stated rationale was crazy. Iran was not close to having nuclear weapons, and Trump himself had boasted about destroying the country’s nuclear program in a bombing strike the prior summer.
Logic doesn’t mean much to Donald Trump. He and Israel’s Prime Minister Benjamin Netanyahu wanted to attack Iran, and whatever story they came up with was secondary.
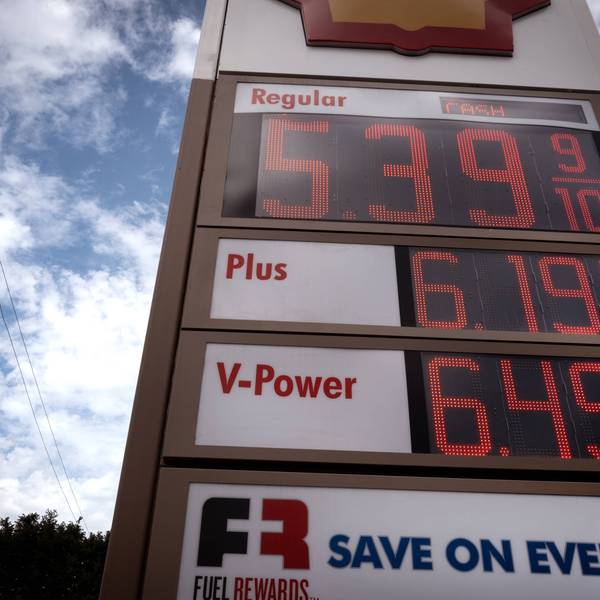
Anyhow, regardless of their motives, they apparently did not expect that the Iranian government would both survive and retaliate by blocking oil from going through the Strait of Hormuz. This sent oil prices soaring, which is the biggest element in the current burst of inflation. However, since oil is not just gas for our cars, but also diesel, which is needed for transporting just about everything, the price hikes are spreading throughout the economy. Also, since much of the world’s fertilizer production takes place in the Gulf countries, fertilizer prices are also soaring. This had some effect on crops already but will be a much bigger deal next year.
The broad impact of Trump’s war on inflation can be clearly seen in the Producer Price Index. The latest year-over-year figure was 6.3 percent for September. Since this is inflation at the wholesale level, it will be showing up at the consumer level in the next few months. To be clear, the impact is not one-to-one, so this doesn’t mean that consumer inflation will be rising to 6.3 percent, but it means that the direction of change in future months will likely be higher, not lower.
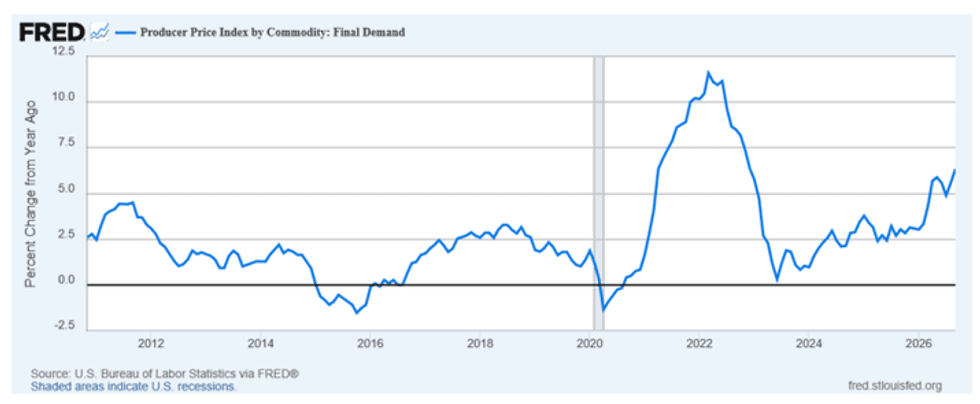
This is very far from a number consistent with the Fed’s 2 percent target. And this is all Trump’s doing. One important difference from the 1970s inflation is that, unlike the 1970s, wages are not rising in step with inflation. The pace of wage growth slowed from 4.0 percent in 2023 and 2024 to 3.0 percent in the most recent data. This means that workers are falling further behind as prices accelerate. The higher prices are going to profits, not covering higher labor costs. That might be good news for Trump’s billionaire donors, but not for the rest of us.
Donald Trump loves to put his name on things, and when it comes to the recent burst of inflation, it’s totally deserved. Trump and Republican politicians are doing their best to try to make a simple story complicated. But there is no doubt that Trump is the lead and almost sole author of the inflation we are now seeing.
Just to quickly clear away the stupid: We did have a large burst of inflation under Biden, just like the rest of the world. We were hit with a worldwide pandemic in Trump’s first term, which he apparently can’t remember. The pandemic led to a massive fall in output in 2020, while Trump was president.
When Biden took office in January of 2021, we were still down more than 10 million jobs from the pre-pandemic level. Biden’s recovery package quickly got back the lost jobs and got the unemployment rate down to 4.0 percent by the end of the year, far faster than anyone expected.
The reopening of the economy from the pandemic recession led to a burst of inflation in the United States, as it did in Germany, France, and everywhere else. Suddenly people were buying lots of things, and it took a while for businesses to ramp up production.
If Biden had cared less about getting people back to work, the recovery package could have been smaller, and the peak inflation rate might have been 1-2 percentage points lower. But the important part of the story is that inflation quickly came down.
Year-over-year inflation peaked at 9.0 percent in June of 2022. A year later, it was down to 3.1 percent. It was down to 2.6 percent by the election in November of 2024. Inflation was generally expected to continue to fall and to be at or near the Fed’s 2.0 percent target by the end of 2025.
But then Trump turned everything around. Inflation began to rise even before he took office, as households and businesses stocked up on imported goods in anticipation of Trump tariffs. Durable goods prices, which had been falling since early 2023, stopped falling and began to rise. The Consumer Price Index also stopped falling and started to rise. Year-over-year inflation hit 3.0 percent in September 2025 but then slowed to 2.7 percent by the end of the year.
It likely would have continued to slow through 2026. After all, Trump’s tariffs were primarily a one-time event. If he didn’t keep imposing new ones (a big “if”), it was reasonable to think that inflation would settle back down to its pre-tariff pace.
But we never got to test that theory. Trump decided to go to war with Iran at the end of February. As we all know, the stated rationale was crazy. Iran was not close to having nuclear weapons, and Trump himself had boasted about destroying the country’s nuclear program in a bombing strike the prior summer.
Logic doesn’t mean much to Donald Trump. He and Israel’s Prime Minister Benjamin Netanyahu wanted to attack Iran, and whatever story they came up with was secondary.
Anyhow, regardless of their motives, they apparently did not expect that the Iranian government would both survive and retaliate by blocking oil from going through the Strait of Hormuz. This sent oil prices soaring, which is the biggest element in the current burst of inflation. However, since oil is not just gas for our cars, but also diesel, which is needed for transporting just about everything, the price hikes are spreading throughout the economy. Also, since much of the world’s fertilizer production takes place in the Gulf countries, fertilizer prices are also soaring. This had some effect on crops already but will be a much bigger deal next year.
The broad impact of Trump’s war on inflation can be clearly seen in the Producer Price Index. The latest year-over-year figure was 6.3 percent for September. Since this is inflation at the wholesale level, it will be showing up at the consumer level in the next few months. To be clear, the impact is not one-to-one, so this doesn’t mean that consumer inflation will be rising to 6.3 percent, but it means that the direction of change in future months will likely be higher, not lower.
This is very far from a number consistent with the Fed’s 2 percent target. And this is all Trump’s doing. One important difference from the 1970s inflation is that, unlike the 1970s, wages are not rising in step with inflation. The pace of wage growth slowed from 4.0 percent in 2023 and 2024 to 3.0 percent in the most recent data. This means that workers are falling further behind as prices accelerate. The higher prices are going to profits, not covering higher labor costs. That might be good news for Trump’s billionaire donors, but not for the rest of us.