5
#000000
#FFFFFF
To donate by check, phone, or other method, see our More Ways to Give page.
Daily news & progressive opinion—funded by the people, not the corporations—delivered straight to your inbox.
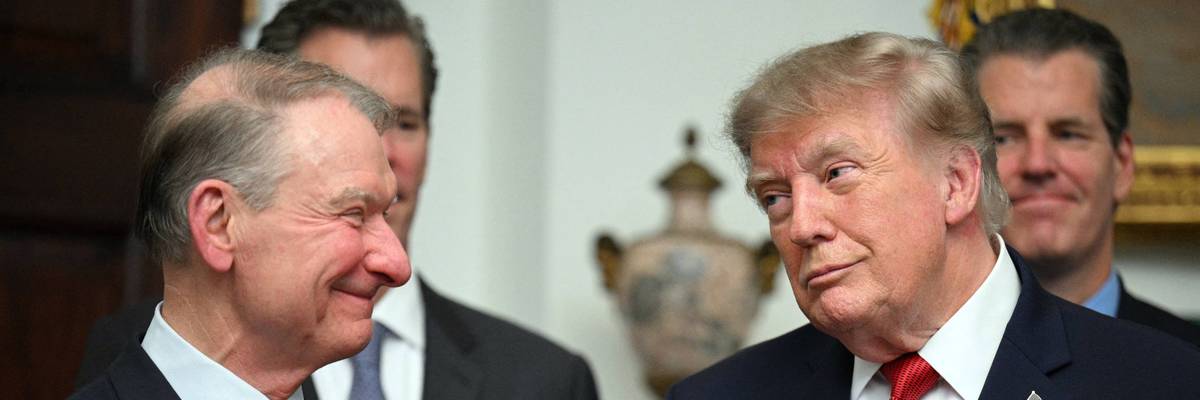
US Securities and Exchange Commission Chair Paul Atkins and President Donald Trump smile at each other during a meeting with cryptocurrency executives in the Roosevelt Room of the White House in Washington, DC on August 19, 2026.
"The Trump SEC is seeking to bail out the struggling private equity and private credit industry with hardworking Americans' retirement savings."
The US Securities and Exchange Commission on Wednesday proposed policies that SEC Chair Paul Atkins framed as an effort to promote private market investments by retail investors—or everyday Americans—while also "protecting those investors from bad actors and fraud," but critics accused the Republican-dominated federal agency of serving Wall Street at the expense of the public.
"Chair Atkins talks about the 'responsible retailization' of the private markets, but the rules the SEC proposed today are irresponsible," declared Benjamin Schiffrin, director of securities policy for the nonprofit Better Markets. "The SEC is supposed to protect retail investors from risky private market assets. Instead, it is encouraging investors saving for college and retirement to direct their savings to private market investments that do not offer greater returns but that do offer less disclosure and more limited legal recourse when harmed."
"Although hedge funds may charge fees based on performance to their investors, the SEC has long prohibited investment advisers from charging retail investors performance-based fees," Schiffrin explained. "This protects them from arrangements that might encourage advisers to take undue risks with retail client funds to increase their compensation. Yet the SEC's proposed rules would make such arrangements permissible. This change would eliminate a limitation on the ability of private funds that charge performance-based fees to sell to retail investors and would incentivize advisers to push retail clients into risky private funds that have performance-based fees."
The new rules would also make it easier to sell interval funds, which "hold complex and illiquid assets and charge high fees," Schiffrin noted. "Given that many interval funds have faced heightened redemption requests from existing investors seeking to exit these funds in recent months, now hardly seems like the time to further expose retail investors to these funds."
“Perhaps most troublingly, the SEC expands the categories of individuals who qualify as so-called 'accredited investors' to whom private market assets may be sold," he continued. Specifically, the agency said it is considering letting individuals with some certificates or licenses—such as certified public accountants, research analysts, and financial analysts and planners—qualify.
"Accredited investors are supposed to be institutions and individuals with enough assets to bear the risk of loss inherent in private market assets," Schiffrin stressed. "Now, the SEC would allow individuals to qualify as accredited investors without regard to their ability to lose money in the private markets."
The expert also highlighted the timing of these proposals, pointing to the agency's Monday statement that "reminded the private funds industry of its obligations regarding valuing assets and providing disclosure to investors," which Schiffrin said was "obviously intended to provide cover for the SEC's desired expansion of the private markets."
"Having previously downplayed the turmoil in the private credit markets, continued redemption requests by private credit investors forced the SEC to acknowledge that private market assets are particularly risky and to reassure investors it was not asleep at the switch," he said. "Yet the statement begs the question of why the SEC would seek to expose retail investors to the private markets at the same time it acknowledges the risks that private market assets pose even to institutional investors."
"The answer is that the SEC has lost its way," he concluded. "Its agenda is now the financial industry's agenda, and private funds need access to retail investors and their savings as institutional investors increasingly pull back from private markets. So the proposed rules the SEC issued today have nothing to do with 'democratizing access' to the private markets and everything to do with allowing the financial industry to prey on unsuspecting retail investors."
The SEC chair said Wednesday that the agency's latest moves "complement efforts undertaken pursuant to" President Donald Trump's August 2025 executive order on Democratizing Access to Alternative Assets for 401(k) Investors—which Schiffrin warned last year "exemplifies the administration's determination to prioritize the interests of Wall Street over the interests of Main Street and retail investors."
"Let's be clear: Neither 401(k) plan sponsors or 401(k) plan participants—regular, hardworking Americans—are asking to replace stocks and bonds in their 401(k)s with risky private assets," Schiffrin said at the time. "Instead, the private funds industry needs a way to get its hands on the $12 trillion in Americans' retirement accounts to boost its profits and make up for the fact that institutional investors are fleeing the private markets due to mediocre returns, higher fees, and more risk."
Despite such criticism of Trump's order, the US Department of Labor unveiled its related proposal in March. Jim Baker, executive director of the nonprofit Private Equity Stakeholder Project, pointed to the pending DOL policy in a Wednesday statement responding to the SEC action.
"With the proposed rules, combined with the DOL's 401(k) rule, the Trump SEC is seeking to bail out the struggling private equity and private credit industry with hardworking Americans' retirement savings," he said. "Private equity funds have lagged public markets while charging much higher fees, and institutional investors are pulling back from the asset class. These rules risk shifting more financial risk onto workers who rely on their retirement savings for long-term security."
"Private equity firms are already under pressure from a backlog of unsold assets and declining distributions to investors," Baker emphasized. “At the same time, policymakers are giving private equity access to retirement savers' 401(k) plans, raising serious questions about whether these investment risks are being shifted onto everyday retirement savers."
"Retirement accounts exist to provide security, not to bail out private market investments by shifting liquidity risk onto workers when markets turn," he added. "At a minimum, the SEC should hold private equity to the same disclosure and transparency standards expected of publicly traded stocks, mutual funds, and [exchange-traded funds], including clear reporting on what funds are investing in, the fees and expenses retirement savers are paying, the amount of debt funds are using, and how these investments are actually performing compared with stocks."
Key members of Congress also responded to the SEC's Wednesday proposals. While Republicans on the US Senate Banking, Housing, and Urban Affairs Committee welcomed the push to expand the accredited investor definition, which aligns with Chair Tim Scott's (R-SC) Empowering Main Street in America Act, Ranking Member Elizabeth Warren (D-Mass.) was critical.
"Today, the SEC proposed a new rule that would override decades-old protections for Americans' retirements to allow Wall Street to start charging high, private equity-level fees on lower-cost retail funds," Warren said. "Americans already struggling to save in Trump's economy shouldn’t be used as piggy banks to boost the profits of Trump’s Wall Street buddies."
Dear Common Dreams reader, It’s been nearly 30 years since I co-founded Common Dreams with my late wife, Lina Newhouser. We had the radical notion that journalism should serve the public good, not corporate profits. It was clear to us from the outset what it would take to build such a project. No paid advertisements. No corporate sponsors. No millionaire publisher telling us what to think or do. Many people said we wouldn't last a year, but we proved those doubters wrong. Together with a tremendous team of journalists and dedicated staff, we built an independent media outlet free from the constraints of profits and corporate control. Our mission has always been simple: To inform. To inspire. To ignite change for the common good. Building Common Dreams was not easy. Our survival was never guaranteed. When you take on the most powerful forces—Wall Street greed, fossil fuel industry destruction, Big Tech lobbyists, and uber-rich oligarchs who have spent billions upon billions rigging the economy and democracy in their favor—the only bulwark you have is supporters who believe in your work. But here’s the urgent message from me today. It's never been this bad out there. And it's never been this hard to keep us going. At the very moment Common Dreams is most needed, the threats we face are intensifying. We need your support now more than ever. We don't accept corporate advertising and never will. We don't have a paywall because we don't think people should be blocked from critical news based on their ability to pay. Everything we do is funded by the donations of readers like you. When everyone does the little they can afford, we are strong. But if that support retreats or dries up, so do we. Will you donate now to make sure Common Dreams not only survives but thrives? —Craig Brown, Co-founder |
The US Securities and Exchange Commission on Wednesday proposed policies that SEC Chair Paul Atkins framed as an effort to promote private market investments by retail investors—or everyday Americans—while also "protecting those investors from bad actors and fraud," but critics accused the Republican-dominated federal agency of serving Wall Street at the expense of the public.
"Chair Atkins talks about the 'responsible retailization' of the private markets, but the rules the SEC proposed today are irresponsible," declared Benjamin Schiffrin, director of securities policy for the nonprofit Better Markets. "The SEC is supposed to protect retail investors from risky private market assets. Instead, it is encouraging investors saving for college and retirement to direct their savings to private market investments that do not offer greater returns but that do offer less disclosure and more limited legal recourse when harmed."
"Although hedge funds may charge fees based on performance to their investors, the SEC has long prohibited investment advisers from charging retail investors performance-based fees," Schiffrin explained. "This protects them from arrangements that might encourage advisers to take undue risks with retail client funds to increase their compensation. Yet the SEC's proposed rules would make such arrangements permissible. This change would eliminate a limitation on the ability of private funds that charge performance-based fees to sell to retail investors and would incentivize advisers to push retail clients into risky private funds that have performance-based fees."
The new rules would also make it easier to sell interval funds, which "hold complex and illiquid assets and charge high fees," Schiffrin noted. "Given that many interval funds have faced heightened redemption requests from existing investors seeking to exit these funds in recent months, now hardly seems like the time to further expose retail investors to these funds."
“Perhaps most troublingly, the SEC expands the categories of individuals who qualify as so-called 'accredited investors' to whom private market assets may be sold," he continued. Specifically, the agency said it is considering letting individuals with some certificates or licenses—such as certified public accountants, research analysts, and financial analysts and planners—qualify.
"Accredited investors are supposed to be institutions and individuals with enough assets to bear the risk of loss inherent in private market assets," Schiffrin stressed. "Now, the SEC would allow individuals to qualify as accredited investors without regard to their ability to lose money in the private markets."
The expert also highlighted the timing of these proposals, pointing to the agency's Monday statement that "reminded the private funds industry of its obligations regarding valuing assets and providing disclosure to investors," which Schiffrin said was "obviously intended to provide cover for the SEC's desired expansion of the private markets."
"Having previously downplayed the turmoil in the private credit markets, continued redemption requests by private credit investors forced the SEC to acknowledge that private market assets are particularly risky and to reassure investors it was not asleep at the switch," he said. "Yet the statement begs the question of why the SEC would seek to expose retail investors to the private markets at the same time it acknowledges the risks that private market assets pose even to institutional investors."
"The answer is that the SEC has lost its way," he concluded. "Its agenda is now the financial industry's agenda, and private funds need access to retail investors and their savings as institutional investors increasingly pull back from private markets. So the proposed rules the SEC issued today have nothing to do with 'democratizing access' to the private markets and everything to do with allowing the financial industry to prey on unsuspecting retail investors."
The SEC chair said Wednesday that the agency's latest moves "complement efforts undertaken pursuant to" President Donald Trump's August 2025 executive order on Democratizing Access to Alternative Assets for 401(k) Investors—which Schiffrin warned last year "exemplifies the administration's determination to prioritize the interests of Wall Street over the interests of Main Street and retail investors."
"Let's be clear: Neither 401(k) plan sponsors or 401(k) plan participants—regular, hardworking Americans—are asking to replace stocks and bonds in their 401(k)s with risky private assets," Schiffrin said at the time. "Instead, the private funds industry needs a way to get its hands on the $12 trillion in Americans' retirement accounts to boost its profits and make up for the fact that institutional investors are fleeing the private markets due to mediocre returns, higher fees, and more risk."
Despite such criticism of Trump's order, the US Department of Labor unveiled its related proposal in March. Jim Baker, executive director of the nonprofit Private Equity Stakeholder Project, pointed to the pending DOL policy in a Wednesday statement responding to the SEC action.
"With the proposed rules, combined with the DOL's 401(k) rule, the Trump SEC is seeking to bail out the struggling private equity and private credit industry with hardworking Americans' retirement savings," he said. "Private equity funds have lagged public markets while charging much higher fees, and institutional investors are pulling back from the asset class. These rules risk shifting more financial risk onto workers who rely on their retirement savings for long-term security."
"Private equity firms are already under pressure from a backlog of unsold assets and declining distributions to investors," Baker emphasized. “At the same time, policymakers are giving private equity access to retirement savers' 401(k) plans, raising serious questions about whether these investment risks are being shifted onto everyday retirement savers."
"Retirement accounts exist to provide security, not to bail out private market investments by shifting liquidity risk onto workers when markets turn," he added. "At a minimum, the SEC should hold private equity to the same disclosure and transparency standards expected of publicly traded stocks, mutual funds, and [exchange-traded funds], including clear reporting on what funds are investing in, the fees and expenses retirement savers are paying, the amount of debt funds are using, and how these investments are actually performing compared with stocks."
Key members of Congress also responded to the SEC's Wednesday proposals. While Republicans on the US Senate Banking, Housing, and Urban Affairs Committee welcomed the push to expand the accredited investor definition, which aligns with Chair Tim Scott's (R-SC) Empowering Main Street in America Act, Ranking Member Elizabeth Warren (D-Mass.) was critical.
"Today, the SEC proposed a new rule that would override decades-old protections for Americans' retirements to allow Wall Street to start charging high, private equity-level fees on lower-cost retail funds," Warren said. "Americans already struggling to save in Trump's economy shouldn’t be used as piggy banks to boost the profits of Trump’s Wall Street buddies."