
SUBSCRIBE TO OUR FREE NEWSLETTER
Daily news & progressive opinion—funded by the people, not the corporations—delivered straight to your inbox.
5
#000000
#FFFFFF
To donate by check, phone, or other method, see our More Ways to Give page.
Daily news & progressive opinion—funded by the people, not the corporations—delivered straight to your inbox.
"The Trump SEC is seeking to bail out the struggling private equity and private credit industry with hardworking Americans' retirement savings."
The US Securities and Exchange Commission on Wednesday proposed policies that SEC Chair Paul Atkins framed as an effort to promote private market investments by retail investors—or everyday Americans—while also "protecting those investors from bad actors and fraud," but critics accused the Republican-dominated federal agency of serving Wall Street at the expense of the public.
"Chair Atkins talks about the 'responsible retailization' of the private markets, but the rules the SEC proposed today are irresponsible," declared Benjamin Schiffrin, director of securities policy for the nonprofit Better Markets. "The SEC is supposed to protect retail investors from risky private market assets. Instead, it is encouraging investors saving for college and retirement to direct their savings to private market investments that do not offer greater returns but that do offer less disclosure and more limited legal recourse when harmed."
"Although hedge funds may charge fees based on performance to their investors, the SEC has long prohibited investment advisers from charging retail investors performance-based fees," Schiffrin explained. "This protects them from arrangements that might encourage advisers to take undue risks with retail client funds to increase their compensation. Yet the SEC's proposed rules would make such arrangements permissible. This change would eliminate a limitation on the ability of private funds that charge performance-based fees to sell to retail investors and would incentivize advisers to push retail clients into risky private funds that have performance-based fees."
The new rules would also make it easier to sell interval funds, which "hold complex and illiquid assets and charge high fees," Schiffrin noted. "Given that many interval funds have faced heightened redemption requests from existing investors seeking to exit these funds in recent months, now hardly seems like the time to further expose retail investors to these funds."
“Perhaps most troublingly, the SEC expands the categories of individuals who qualify as so-called 'accredited investors' to whom private market assets may be sold," he continued. Specifically, the agency said it is considering letting individuals with some certificates or licenses—such as certified public accountants, research analysts, and financial analysts and planners—qualify.
"Accredited investors are supposed to be institutions and individuals with enough assets to bear the risk of loss inherent in private market assets," Schiffrin stressed. "Now, the SEC would allow individuals to qualify as accredited investors without regard to their ability to lose money in the private markets."
The expert also highlighted the timing of these proposals, pointing to the agency's Monday statement that "reminded the private funds industry of its obligations regarding valuing assets and providing disclosure to investors," which Schiffrin said was "obviously intended to provide cover for the SEC's desired expansion of the private markets."
"Having previously downplayed the turmoil in the private credit markets, continued redemption requests by private credit investors forced the SEC to acknowledge that private market assets are particularly risky and to reassure investors it was not asleep at the switch," he said. "Yet the statement begs the question of why the SEC would seek to expose retail investors to the private markets at the same time it acknowledges the risks that private market assets pose even to institutional investors."
"The answer is that the SEC has lost its way," he concluded. "Its agenda is now the financial industry's agenda, and private funds need access to retail investors and their savings as institutional investors increasingly pull back from private markets. So the proposed rules the SEC issued today have nothing to do with 'democratizing access' to the private markets and everything to do with allowing the financial industry to prey on unsuspecting retail investors."
The SEC chair said Wednesday that the agency's latest moves "complement efforts undertaken pursuant to" President Donald Trump's August 2025 executive order on Democratizing Access to Alternative Assets for 401(k) Investors—which Schiffrin warned last year "exemplifies the administration's determination to prioritize the interests of Wall Street over the interests of Main Street and retail investors."
"Let's be clear: Neither 401(k) plan sponsors or 401(k) plan participants—regular, hardworking Americans—are asking to replace stocks and bonds in their 401(k)s with risky private assets," Schiffrin said at the time. "Instead, the private funds industry needs a way to get its hands on the $12 trillion in Americans' retirement accounts to boost its profits and make up for the fact that institutional investors are fleeing the private markets due to mediocre returns, higher fees, and more risk."
Despite such criticism of Trump's order, the US Department of Labor unveiled its related proposal in March. Jim Baker, executive director of the nonprofit Private Equity Stakeholder Project, pointed to the pending DOL policy in a Wednesday statement responding to the SEC action.
"With the proposed rules, combined with the DOL's 401(k) rule, the Trump SEC is seeking to bail out the struggling private equity and private credit industry with hardworking Americans' retirement savings," he said. "Private equity funds have lagged public markets while charging much higher fees, and institutional investors are pulling back from the asset class. These rules risk shifting more financial risk onto workers who rely on their retirement savings for long-term security."
"Private equity firms are already under pressure from a backlog of unsold assets and declining distributions to investors," Baker emphasized. “At the same time, policymakers are giving private equity access to retirement savers' 401(k) plans, raising serious questions about whether these investment risks are being shifted onto everyday retirement savers."
"Retirement accounts exist to provide security, not to bail out private market investments by shifting liquidity risk onto workers when markets turn," he added. "At a minimum, the SEC should hold private equity to the same disclosure and transparency standards expected of publicly traded stocks, mutual funds, and [exchange-traded funds], including clear reporting on what funds are investing in, the fees and expenses retirement savers are paying, the amount of debt funds are using, and how these investments are actually performing compared with stocks."
Key members of Congress also responded to the SEC's Wednesday proposals. While Republicans on the US Senate Banking, Housing, and Urban Affairs Committee welcomed the push to expand the accredited investor definition, which aligns with Chair Tim Scott's (R-SC) Empowering Main Street in America Act, Ranking Member Elizabeth Warren (D-Mass.) was critical.
"Today, the SEC proposed a new rule that would override decades-old protections for Americans' retirements to allow Wall Street to start charging high, private equity-level fees on lower-cost retail funds," Warren said. "Americans already struggling to save in Trump's economy shouldn’t be used as piggy banks to boost the profits of Trump’s Wall Street buddies."
"Doctors should be able to do what's best for their patients, not what's best for some wealthy investor."
Thanks to legislation passed in Oregon last year, physicians in the state have stopped corporate takeovers of medical practices—and six Democratic members of Congress on Wednesday introduced a bill to replicate the state law nationwide, arguing, as Sen. Elizabeth Warren said, that "patients want to know that decisions about their health are being made by their doctors, not by Wall Street investors."
The Massachusetts Democrat was joined by Sens. Ron Wyden (D-Ore.) and Jeff Merkley (D-Ore.), along with Reps. Val Hoyle (D-Ore.), Alexandria Ocasio-Cortez (D-NY), and Suhas Subramanyam (D-Va.) in introducing the Stop Corporate Takeovers of Physicians Act.
The bill would ban the corporate practice of medicine by making it illegal for private equity funds, insurance companies, and other for-profit corporations to own or control medical practices—as is increasingly the case in the profit-driven US healthcare system.
Over 80% of doctors in the US are employed by corporate entities including private equity firms—up from 62% just seven years ago, according to the lawmakers.
Corporations have also exploited legal loopholes that allow them to take over medical practices, despite laws in over 30 states banning the corporate practice of medicine.
“Americans want medical decisions to stay between patients and their doctor, not dictated by corporate actors and private equity firms focused on maximizing profits,” said Wyden. “I’m proud of Oregon’s pioneering state law that has been used by doctors to protect their independence, and it’s time to take that model to the federal level. Corporate medicine is making healthcare more expensive for everyone, and safeguards must be put in place to ensure healthcare decisions stay in the hands of physicians.”
The legislation would:
"But these actors often challenge the autonomy of acquired physicians once in control," they said. "For example, corporate entities often assume control over clinical operations, management and staffing decisions, and billing and coding practices—all of which can exert pressure on physicians to change care delivery."
Such entities "often cut corners, leading to patients paying more for significantly worse care," said Ocasio-Cortez. “I’m proud to co-lead the Stop Corporate Takeovers of Physicians Act to get Wall Street out of Americans’ doctors’ offices."
Warren added that "doctors should be able to do what's best for their patients, not what's best for some wealthy investor."
BREAKING: Today, I'm introducing a bill to BAN corporate takeovers of your doctor's office.
Doctors should be able to care for their patients without greedy private equity investors getting in the way.
Let's get this done. pic.twitter.com/e3gdamIotQ
— Elizabeth Warren (@SenWarren) September 16, 2026
The legislation is supported by several medical associations as well as economic justice advocates.
"A prohibition is only as strong as its enforcement, and this bill backs its corporate practice of medicine (CPOM) prohibition with three enforcement paths: the Federal Trade Commission, state attorneys general suing on behalf of residents, and physicians themselves through a private right of action with treble damages. That layered enforcement, paired with mandatory divestment, is what gives this bill teeth that earlier CPOM laws have often lacked,” said Dr. Marco Fernandez, president of the Association for Independent Medicine.
Alex Lawson, executive director of Social Security Works, said that the "groundbreaking legislation is absolutely needed to give health providers and patients a fighting chance against corporate greed."
"Congress must stop private equity from ripping the copper wires out of American healthcare and put patients first," said Lawson. "Social Security Works is proud to endorse this legislation."
Charles Idelson, the former communications director of National Nurses United, which advocates for Medicare for All, said the bill "would help close some, though not all, of the worst profiteering in healthcare."
"Exploiting sickness to enrich wealthy executives," said Idelson, "is obscene."
"These deals produce harm reliably enough that researchers can now count it."
Investigative journalist Ronan Farrow on Tuesday published a video on social media where he examines how private equity firms have been buying up hospitals throughout the US and saddling them with enormous debt burdens.
At the start of the video, Farrow notes that private equity firms such as The Carlyle Group, Cerberus, and Pinta have acquired hundreds of hospitals and nursing homes over the last 20 years.
"The pitch is generally: Infuse capital, cut inefficiency, and exit in five to seven years," Farrow explains. "And the deals work like this: A private equity firm puts some of its own money and borrows the rest. Typically, it'll borrow more than 70% of the purchase price."
"The twist is that debt doesn't sit on the firm's books," Farrow continues. "It gets placed on the facility itself, so the hospital or nursing home now carries the debt and the interest on it."
Studies now present a striking picture of what happens when private equity firms acquire hospitals and nursing homes: predictable increases in harm and deaths. One landmark study shows: patient deaths up about 11% after such acquisitions. pic.twitter.com/N6yfXJQIwW
— Ronan Farrow (@RonanFarrow) July 7, 2026
Farrow then cites research published by The Review of Financial Studies in 2023, which found healthcare facilities saw their interest payments more than triple after being acquired by private equity firms.
"In many cases," Farrow says, "private equity firms sold the nursing home's building shortly after acquiring it, returning the proceeds to investors, and then charging the facility rent on the building it used to own."
In addition to added debt burdens placed on hospitals and nursing homes, Farrow adds, the 2023 study found that private equity firms also cut staff hours after acquiring facilities, which has hurt patient care.
"The authors... found that private equity ownership can increase patient mortality by up to 11%," he says. "Over the study period, that translated to more than 20,000 lives lost."
Farrow then points to a 2025 study that found salaries of emergency room workers fall by an average of 18% in hospitals acquired by private equity firms, while hospital-acquired infections and complications rose by 25%.
Farrow concedes that not all private-equity deals turn out poorly and that some of the facilities are already in distress before being acquired.
However, he warns that "these deals produce harm reliably enough that researchers can now count it," adding that "so far, the industry has moved faster than the rules."
Research published Monday by the Private Equity Stakeholder Project (PESP) warned that private equity firms have been increasingly relying on nonprofit joint ventures to expand their reach throughout the US healthcare industry and "siphon profits from health systems and critical healthcare infrastructure."
"Private equity's healthcare playbook is evolving,” said Jim Baker, executive director of PESP. “Our research documents how private equity has increasingly relied on joint ventures with nonprofits to expand its presence in healthcare. These arrangements have received far less attention than traditional private equity buyouts, even as they become more common across hospitals and other healthcare sectors."
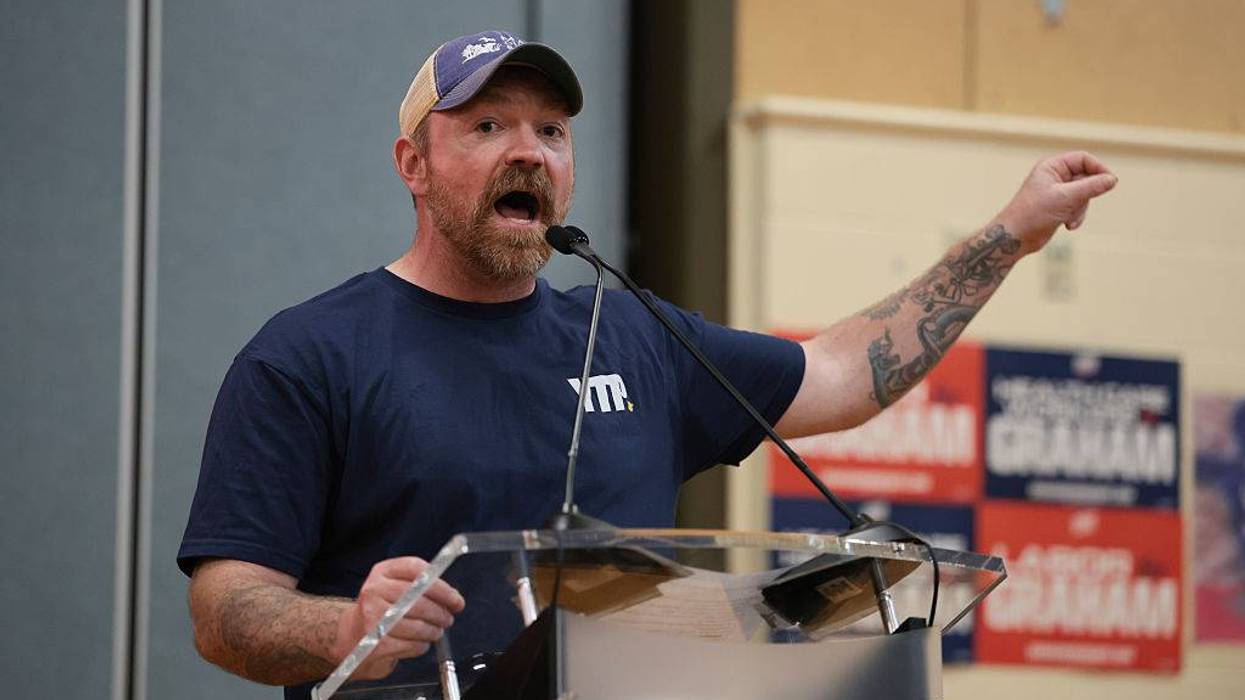
"Private equity is destroying our favorite baseball team, stripping them for parts," Democratic US Senate candidate Platner said in an ad that aired on the New England Sports Network.
Maine Democratic US Senate candidate Graham Platner on Saturday said that a campaign ad that aired during a Boston Red Sox game was "taken down" after it took aim at the team's ownership.
The ad in question features Platner discussing the role that private equity firms play in the US economy, including sports teams.
"Private equity is destroying our favorite baseball team, stripping them for parts," Platner says at the start of the ad. "Private equity is buying up our homes, our sports, and our lives. I will reverse the private equity curse."
Private equity is taking our homes. It's taking our hospitals. It's taking beloved local businesses and stripping them for parts.
And now private equity is running the Red Sox into the ground.
Our new ad ⬇️ pic.twitter.com/w7LapElpdA
— Graham Platner for Senate (@grahamformaine) May 22, 2026
Platner concludes the ad by saying that he approves this message "because I miss Mookie Betts," the star player whom the Red Sox traded to the Los Angeles Dodgers in 2020 in a deal that was widely decried by local fans as a salary dump.
According to Platner, his campaign began airing the ad Friday on the New England Sports Network (NESN), the cable TV station owned partially by Fenway Sports Group, the conglomerate that owns the Red Sox.
However, he said that "midway through the game the ad was taken down" by NESN, after which the Red Sox proceeded to blow a 4-0 lead, losing to the Minnesota Twins by a final score of 8-6.
Platner, an oyster farmer and upstart candidate who has never before held political office, became the Democratic Party's presumptive nominee for the 2026 US Senate race in Maine last month after his top rival, Democratic Maine Gov. Janet Mills, dropped out of the race.
In recent weeks, Platner has pivoted to challenging incumbent Sen. Susan Collins (R-Maine), who has held the seat since 1996 and is now running for her sixth term in office.
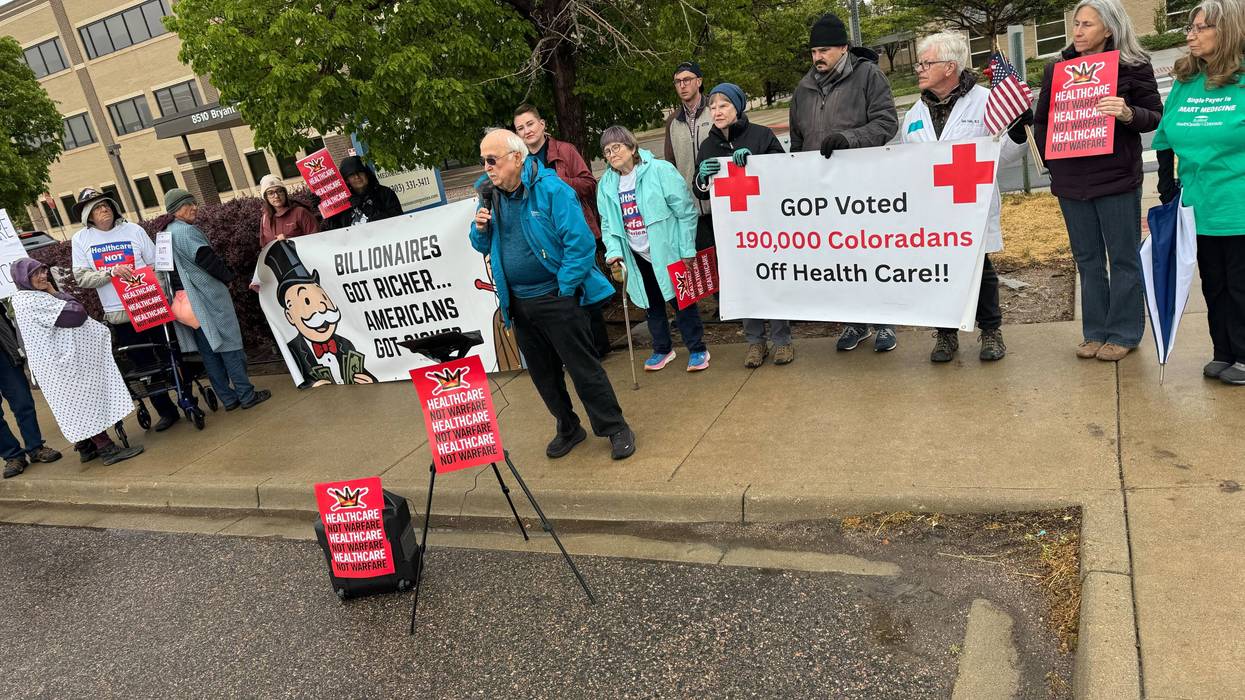
In Colorado and all over the country, we gathered to demand that those who vote to take our healthcare away will be held accountable.
What we say at rallies and meetings with people who could help, but rarely do, is sometimes abstract and loaded with policy discussions that muddle even interested advocates at times. Healthcare in Colorado and all over the country is not only taking a hit with provisions of the “Big Beautiful Bill” passed by Congress in 2024 beginning to take effect, the healthcare industry is also still and increasingly one of the most profitable investment opportunities and nearly one-fifth of our GDP, or gross domestic product, flows from the healthcare industry. Private equity is in. Wall Street is in. It is as though the health industry CEOs and the elected officials they fund know exactly how to play the market to win. Human life is on the balance sheet bottom line buried in accounting lingo and those gorgeous profit terms.
Medicaid cuts hurt people. Medicaid cuts hurt communities. And on Tuesday, May 5, 2026, Coloradans were busy explaining the pain. Some were in warm conference rooms at Denver Health with a United States senator, and some were in the cold rain outside a clinic that could suffer or even close because of the cuts.
Cut losses; maximize gains. We are human widgets—forget the AI revolution if you have ignored the business insurgency into every aspect of the healthcare industry. We all needed to learn the language of greed and profit taking without regard for human life, and all the while we argued lives were lost without coverage. Those numbers of sacrificial dead are no match for the billions and yes, trillions, of dollars wagered, won, and lost making sure that final bottom line looks sexy.
So, in Colorado and all over the country, we gathered to demand those who vote to take our healthcare away will be held accountable. We may be widgets to the bean counters, but to one another and across multiple states and organizations, we stood together against the storm. In Westminster, Colorado, it was freezing rain and chilly, but we stood and carried on.
We intend to love one another enough to make sure human life is the profit we value more than the almighty dollar.
Dr. Vince Markovchick ran the emergency medicine department at Denver Health for 26 years. Think about what he must have seen and heard over time. Human life saved. The care not given when a patient tells the doctor they cannot afford the care or missing work or groceries if they allow care for a serious illness or injury. That is what Dr. Markovchick spoke about. Tender mercies delayed and shared as the rain briefly paused as we listened, as if the universe cared too. (Meanwhile, safe and sound and warm, in the hospital where he gave his professional life for us all, Sen. John Hickenlooper (D-Colo.) held an invitation only round table on the Medicaid cuts. Even the press stayed nice and warm and didn’t come to witness the more than 25 Coloradans who gathered in the cold.)
Lydia Guzman spoke with passion and fire about the damage she saw and sees in lives without access to care; Tyler Quick spoke to us about the issues the LGBTQ+ community faces in receiving not only gender affirming care but HIV prevention and care. We might weep for his reminder to us that what happens in the LGBTQ+ community will also spread to the straight community and others among us. Like it or not, no human is an island. Nope. We are the human community.
What do we demand together in this drippy, difficult weather? We spoke clearly, “Stop Taking Our Healthcare.” No more beautiful bills taking benefits away; no more enforcement of policies in unrelated ways to healthcare delivery; and no more healthcare dollars wasted on business measures like advertising, stockholder pleasures, “inducements” for prescribing or procedures, lobbying expenses for policies passed or policies blocked, or even baubles and freebies when you table with your wares at all those conferences.
Then, we would be fine with seeing that end of the healthcare industry given over to actual delivery of care—for us all. And we intend to stay loud. We intend to be seen. And we intend to love one another enough to make sure human life is the profit we value more than the almighty dollar.
“This isn’t about advancing the interests of retirement savers, it is about opening a new profit center for crypto and Wall Street," said one critic.
US President Donald Trump's Labor Department on Monday unveiled a proposal that would welcome private equity and cryptocurrency investments into Americans' 401(k) plans, the culmination of an aggressive Wall Street lobbying push that could leave the retirement savings of millions vulnerable to the wild swings of so-called "alternative assets."
The proposed rule, now subject to a public comment period, was issued at the direction of a Trump executive order from last year that was characterized at the time as "the holy grail for private equity."
In addition to giving employers a green light to include private equity and crypto investments in 401(k) plans offered to workers, the new rule would establish a "safe harbor" allowing retirement account administrators to avoid legal action from employees who believe their funds were steered into excessively risky products.
"The legal immunity created by this safe harbor will incentivize financial advisers to pitch these toxic products, which will become ticking time bombs in tens of millions of retirement accounts, which will no doubt result in significant losses," warned Benjamin Schiffrin, director of securities policy at the advocacy group Better Markets. "There are good reasons why 401(k) plans have been considered closed to private markets and cryptocurrencies, and those reasons have not changed. The only thing that has changed is the administration’s support for these industries and regulators’ willingness to do their bidding."
"This is no reason to endanger the retirement savings of millions of Americans," Schiffrin added.
Oscar Valdés Viera, senior policy analyst at Americans for Financial Reform, similarly warned that "opening 401(k)s to these products risks turning workers’ retirement savings into a Ponzi-like scheme that throws a lifeline to an industry scrambling for fresh cash."
"This isn’t about advancing the interests of retirement savers, it is about opening a new profit center for crypto and Wall Street," said Viera. "Retirement savers should not be bailing out these high-risk industries and subsidizing the Wall Street and crypto billionaire class."
"Private equity firms should not get a free pass to loot workers’ 401(k) retirement savings."
Americans currently hold over $10 trillion combined in 401(k) plans, a huge trove of wealth that the private equity industry has been working for years to access. The Labor Department indicated that its proposed rule would apply to over 720,000 retirement plans covering roughly 118 million workers.
The American Prospect reported Tuesday that the managers of private equity firms are "already pressuring companies, third-party administrators, and the consultants who advise them to list their offerings" among workers' retirement plan options.
"One staffer at an institutional investor who is not authorized to speak to the media told the Prospect about their primary worry: that private equity will stick their most overvalued companies into continuation funds exclusively for 401(k) plan holders, or 'retail investors,' as they are known," the outlet continued. "Private credit firms are retailoring their funds for 401(k) plans as well, and some of the biggest have already struck deals with asset managers like Voya and Vanguard. 'I’d be shocked if the industry doesn’t attempt to dump their garbage onto retail,' the staffer said."
One recent analysis by the Private Equity Stakeholder Project (PESP) found that private equity funds for retail investors "dramatically underperformed publicly listed stock indexes" in 2025 while charging much higher fees.
Jim Baker, PESP's executive director, said Monday that "private equity firms should not get a free pass to loot workers’ 401(k) retirement savings."
“The bar for including private equity in 401(k)s should be extremely high,” said Baker. “Private equity funds have lagged public markets while charging much higher fees, and public pension funds are pulling back from the asset class. Instead, this rule risks shifting more financial risk onto workers who rely on their retirement savings for long-term security.”
Sen. Elizabeth Warren (D-Mass.) also ripped the Labor Department rule, saying in a statement that "Americans facing an uncertain future in Trump’s economy will now have more reasons to question the security of their retirement savings—all so that Trump’s Wall Street buddies have another pile of cash to play with."
"Anyone who cares about the financial security of working people," said Warren, "should oppose this proposed rule."
“Private equity firms have increasingly brought their playbook to essential care industries," warns Sen. Jeff Merkley, by rolling local childcare centers nationwide "into large chains, and prioritizing investor profits over the well-being of the families.”
US Sen. Jeff Merkley announced the launch of a new investigation into the role of private equity firms in making childcare increasingly unaffordable for American families.
Merkley, the Oregon Democrat who serves as ranking member of the Senate Budget Committee, sent letters to KinderCare Learning Companies and Learning Care Group (LCG), the two largest childcare companies controlled by private equity firms, seeking information about the impact of the relentless profit-seeking of their owners on day-to-day business decisions.
Among other things, Merkley wants the companies to provide insight into the influence that their private equity owners exert over facility acquisition, expansion plans, staffing levels, employee wages and benefits; and capital investments.
Merkley is also asking the companies to "describe how tuition increases... are determined and whether financial obligations to lenders or owners are considered in pricing decisions." He also noted that both KinderCare and LCG faced serious accusations of mismanagement in multiple states.
KinderCare, which is owned by Switzerland-based private equity firm Partners Group, has been cited by state regulators in Indiana and Wisconsin for maintaining facilities with "inadequate supervision, staff-to-child ratio violations, unsafe or unsanitary conditions, and failures to report or respond appropriately to alleged abuse," Merkley wrote.
LCG, which is owned by private equity firm American Securities, operates facilities that have been reported for health and safety violations in numerous states, including Georgia, Missouri, and Texas, Merkley noted, "with incidents involving children left unattended on buses, supervision failures, and alleged physical abuse by staff."
Merkley said he was concerned that the failings at these facilities were being driven by the profit considerations at Partners Group and American Securities.
"Private equity firms have increasingly brought their playbook to essential care industries," said Merkley, "buying up independent providers, rolling them into large chains, and prioritizing investor profits over the well-being of the families and communities that depend on these services."
The senator urged both the childcare companies and their private equity owners to "fully cooperate with this investigation."
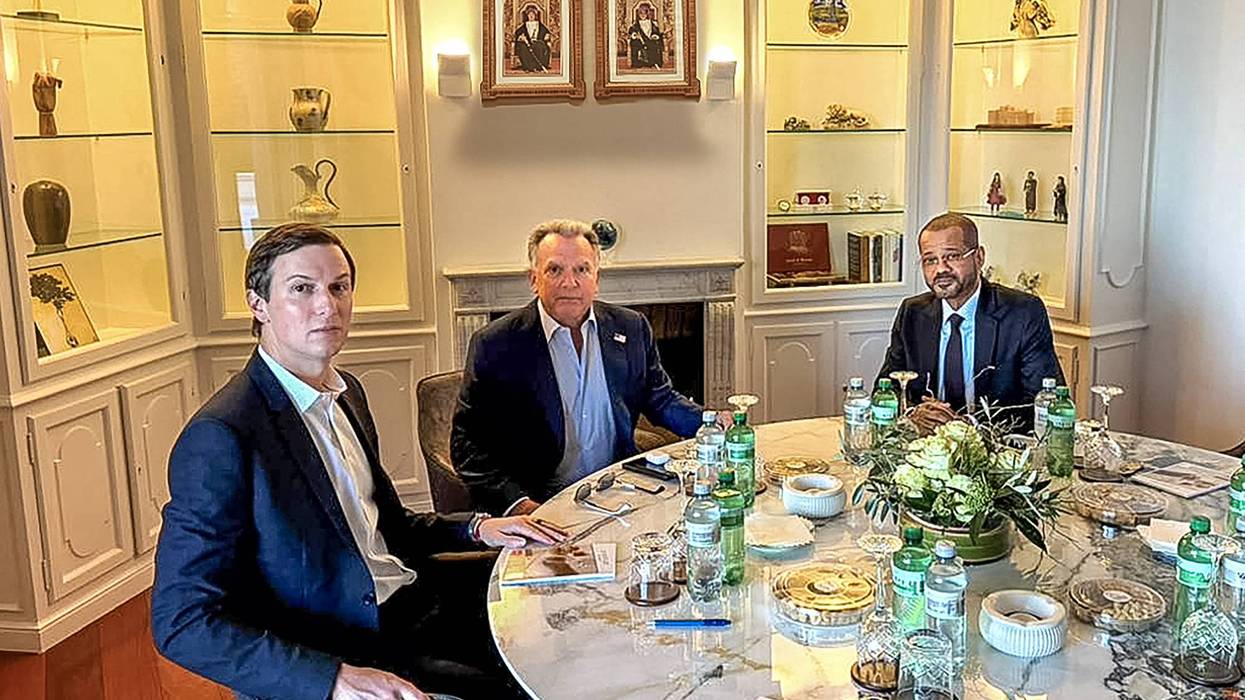
"While US servicemembers die in another forever war in the Middle East, Donald Trump’s 'peace envoy' is raising money for his private equity firm," wrote US Sen. Elizabeth Warren.
Jared Kushner, US President Donald Trump's son-in-law, is reportedly trying to entice governments in the Middle East to invest billions in his private equity firm while he simultaneously works as "a special envoy for peace"—a role he appears to have used to help convince Trump to wage war on Iran.
The New York Times reported late last week that Kushner "has spoken with potential investors in recent weeks about raising $5 billion or more for Affinity Partners, his investment firm."
Citing five unnamed people with knowledge of the talks, the Times reported that "Affinity’s representatives have already met with Saudi Arabia’s Public Investment Fund," Affinity's largest investor. Saudi Arabia's leader, Crown Prince Mohammed bin Salman, reportedly played a significant role in the behind-the-scenes lobbying campaign urging Trump to attack Iran—Saudi Arabia's top regional rival.
Bin Salman controls the Saudi Public Investment Fund, which pumped $2 billion into Kushner's firm in 2022.
"Mr. Kushner’s fundraising is expected to stretch on for the better part of this year," the Times added. "The efforts show the blurring of the lines between public service and private profit-seeking during Mr. Trump’s second term. Only a few weeks ago, in his role as Mr. Trump’s 'peace envoy,' Mr. Kushner met in Geneva with Iran’s foreign minister. The US and Israeli bombing campaign in Iran began shortly after those meetings concluded without a deal on Iran’s nuclear program."
Last week, Trump said he decided to attack Iran in coordination with Israel—whose prime minister, Benjamin Netanyahu, is a personal friend of Kushner's—because the president "thought they were going to attack us," a view he claimed to have reached after listening to "what Steve [Witkoff] and Jared and Pete [Hegseth] and others were telling me."
US Sen. Elizabeth Warren (D-Mass.) wrote in response to the Times reporting that "while US servicemembers die in another forever war in the Middle East, Donald Trump’s 'peace envoy' is raising money for his private equity firm."
Abbas Araghchi, Iran's foreign minister, wrote in a social media post on Sunday that a "fair and equitable deal" between the US and Iran "was within reach" before Trump and Netanyahu started bombing.
"Those providing poor advice to POTUS are responsible for bloodshed," Araghchi wrote, attaching a screenshot of the Times story on Kushner's fundraising efforts. "This war is imposed on both Americans and Iranians."
I've been told that family of a U.S. soldier killed in the war of choice on Iran is relying on public donations.
As fair and equitable deal was within reach, those providing poor advice to POTUS are responsible for bloodshed.
This war is imposed on both Americans and Iranians. pic.twitter.com/fR15XKjfYk
— Seyed Abbas Araghchi (@araghchi) March 15, 2026
Judd Legum, founder and author of the Popular Information newsletter, noted last week that Kushner's participation in the Geneva diplomatic talks that preceded the US-Israeli assault on Iran "violated his pledge not to be involved in foreign policy in a second Trump administration."
On Monday, Legum observed that Kushner also said in December 2024 that his private equity firm would not "have to raise capital for the next four years," allowing him to "avoid any conflicts" of interest.
Trump formally named Kushner a "special envoy for peace" last month, a move that means the president's son-in-law is now required by law to file a financial disclosure report. Kushner has just days left before the 30-day deadline to file the disclosure.
Donald Sherman, president and CEO of Citizens for Responsibility and Ethics in Washington, wrote in a letter to the White House last week that "Mr. Kushner’s history of financial gains resulting from his time as a White House advisor during President Trump’s first term raises serious concerns about potential conflicts of interest that must be addressed before Mr. Kushner participates in any additional matters that may relate to his own financial interests or those of his investors."
"The risk of Mr. Kushner’s potential conflicts is particularly concerning because his private investment firm has very publicly done significant business with foreign partners who also have interests in the conflicts on which he has been assigned to work," Sherman noted.
In the new, out-of-control rental economy, the product is often just bait. The real commodity, the real profit center, the real source of unending corporate cash flow is you.
On Sunday, both President Donald Trump and his secretary of Housing and Urban Development told us that 50-year home mortgages may soon be a thing. While seemingly insane (you could end up paying more than three times the cost of the house and never escape the burden of debt before you die), this is just the latest iteration of one of American businesses’ most profitable scams: the rental economy.
It’s a growing threat to the American middle class that rarely gets named, even as it reshapes our lives every day. Over the past two decades, it’s snuck in quietly, disguised as convenience, efficiency, and “innovation.”
As a result, nothing is “ours” any more. Instead, we’re renting our lives away.
There was a time when you bought things.
It’s become a never-ending extraction of money and personal data from each of us, every month, every year, time after time, over and over again until we’re financially exhausted.
You bought a house, a book, a record, a car, a word processing program. You paid once, took it home or lived in it, and it was yours. If the company went out of business, your stereo still worked. If the manufacturer didn’t get their annual payment, your computer didn’t lock you out of your own words. You could read books on your phone or pad without an internet connection to “confirm your purchase.”
That America is disappearing.
Today, almost everything that used to be a purchase has become a rental.
Take Microsoft Word. Decades ago, you bought it once and used it for years. Now it’s a monthly fee. Stop paying, and you may not even be able to open documents you wrote yourself. Adobe did the same thing. So did music, movies, and television. At first, it felt like convenience; a few dollars a month didn’t seem like a big deal.
Even the latest versions of the two major computer operating systems are essentially spyware, constantly tracking everything you do while demanding that you put all your personal information on their “cloud” servers.
Instead of buying homes, people are renting because, in part, massive New York hedge funds and foreign investors are purchasing as many as half of all the homes that come available for sale in some communities, and then flipping them into rentals. Renters can end up on the hook for their entire lives.
Even the means to get a good job—a college education—has become something you must pay for over a period of decades or even a lifetime instead of the pay-as-you-go model my generation had before Ronald Reagan gutted federal aid to higher ed. We now have almost $2 trillion in student debt—the only developed nation in the world that does this to its students—and I regularly get calls into my radio program from people in their 70s still paying off their student debt.
But this change was never really just about money. It has morphed over the past decades into a new form of corporate control over our lives and our wealth. It’s become a never-ending extraction of money and personal data from each of us, every month, every year, time after time, over and over again until we’re financially exhausted.
When you own something, you decide how it’s used. When you rent, someone else makes that choice. They can raise prices, change terms, remove features, track everything you do with it, or shut it off entirely. Your “choice” becomes compliance.
The billionaire Tech Bros and Wall Street are hoping we’ll all just roll over, sign up, and let them ding our credit cards until our dying day.
That same model has spread everywhere.
Cars used to be machines you owned. Now they’re rolling computers with features like heated seats, remote start, or performance upgrades locked behind monthly fees. Similarly, cars are increasingly leased instead of purchased. Miss your payment this month and the lender will remotely disable “your” vehicle. Your car doesn’t just take you places anymore: It reports on you.
Phones are even worse. They’re not just devices; they’re gatekeepers. Apps can be removed. Accounts can be banned. Services can disappear overnight. And because so much of modern life runs through that phone—banking, work, navigation, healthcare—being cut off isn’t an inconvenience. It’s a functional exclusion from society.
This extends from major things like our cars and homes to simple things like apps. Louise loves to play Scrabble on her phone, and would gladly pay a one-time fee for an app that doesn’t throw ads at her, track and sell her information, or demand constant interaction. Instead, since the old Scrabble app she’s used for years went to a rental model, she’s gone through a half-dozen apps, each worse than the last at demanding her interactions or throwing ads.
And to add insult to injury, layered on top of this rental business model is a vast, multibillion-dollar industry harvesting our personal information.
Every website you visit. Every app you download. Every product you register just to make it work. Your location, habits, preferences, relationships, and even emotional responses are tracked, analyzed, packaged, and sold. Most often without meaningful consent, and almost always without real alternatives.
This is not how American capitalism worked for over 250 years.
The question business leaders used to ask was simple: “What unmet needs do people have that our company can satisfy with a new product or service?” You built something useful, people bought it, and that was the deal.
Today, the question has changed: “How do we make our product so essential that people can’t function without it, then crush or buy out our competitors so there’s no real consumer choice, then charge a monthly fee forever, all while extracting user data we can sell for even more profit?”
That’s not innovation. It’s parasitism.
If everything we touch is leased, freedom is just another fee.
In this model, the product is often just bait. The real commodity, the real profit center, the real source of unending corporate cash flow is you.
And because the billionaire “Tech Bros” and Wall Street oligarchs control the products, the data, and increasingly our nation’s news and social media, they also control the content and algorithms that shape public opinion.
As a result, social media and even our news (think CBS, the Washington Post, the LA Times, Fox “News”) increasingly doesn’t just reflect reality, they engineer it to get us to think of this new rental economy as normal, as innovative, as The Way Things Should Be.
In addition to profitably amplifying outrage, profitably distorting truth, and polishing the public image of this new rental economy—all to create billions in ongoing month-after-month profits—America’s billionaire tech lords and the right-wing politicians they bankroll (thanks to five corrupt Republicans on the Supreme Court) are manufacturing our consent (to apply Noam Chomsky’s phrase).
Thomas Jefferson warned that people are inclined to suffer evils while they are sufferable rather than abolish the forms to which they’ve grown accustomed. The billionaire Tech Bros and Wall Street are hoping we’ll all just roll over, sign up, and let them ding our credit cards until our dying day.
It’s gotten so bad that apps—which also acquire and then sell our data—have emerged that track our “subscriptions” so we can try to get it all under control. They’re advertising them on TV every day: Get this app to find out what apps are secretly extracting your cash because you long ago forgot you clicked on that link.
None of this was inevitable.
The solution is not to smash technology or retreat into the past. It’s for government to once again work for the 99% instead of the 1%. That means once again regulating money in politics, private equity, social media, data harvesting, and the out-of-control rental economy that has replaced ownership.
It means breaking monopolies, restoring regulatory independence, making education affordable, supporting home and car ownership, and reaffirming that democracy—not billionaires—sets the rules of the road.
Technology should serve human freedom, not manage it. Markets should reward service and quality of content, not extraction. People should be able to choose to pay or not to pay for things from apps to the functionality of your car or home’s HVAC system.
Nothing is ours any more. Not the road, not the floor. If everything we touch is leased, freedom is just another fee.
If we don’t act to regulate this out-of-control rental economy, we may one day realize we didn’t lose our wealth and even our democracy all at once: We simply rented our way out of it.
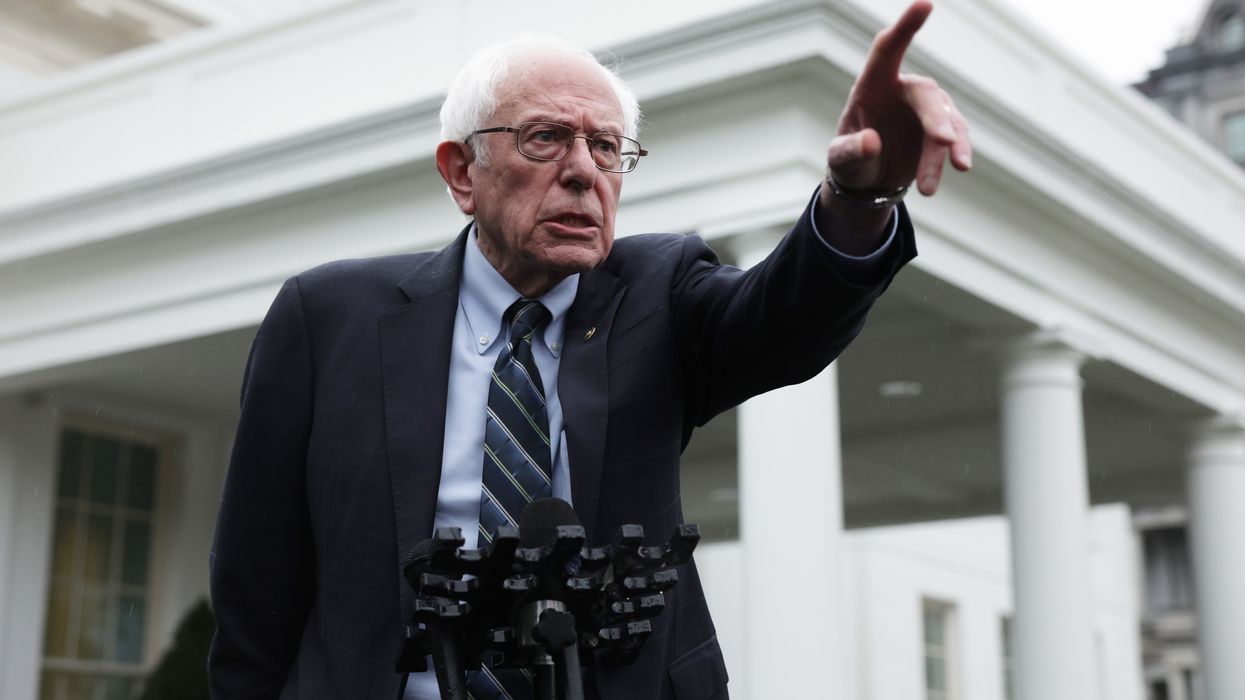
"While the rich get richer, workers are struggling, and your decision to cut workers' paid vacation is making the problem worse."
Independent US Sen. Bernie Sanders on Tuesday urged the private equity firm that recently acquired Walgreens to reverse its decision to strip hourly workers at the second-largest US pharmacy chain of paid days off on Christmas and other major holidays.
After Sycamore Partners finalized its $10 billion purchase of Walgreens in late August, the pharmacy chain—now headed by CEO Mike Motz—eliminated paid holidays for New Year's Day, Memorial Day, Independence Day, Labor Day, Thanksgiving, and Christmas. Workers were notified of the move, which was first reported by Bloomberg, in October.
The move is typical of what private equity firms—sometimes called vulture capitalists—often do in order to maximize profits. In addition to slashing paid time off and benefits, they often reduce or freeze pay, fire workers, close locations, introduce aggressive sales targets, and reduce job security by replacing full-time positions with hourly or independently contracted workers. Walgreens announced last year that it planned on closing around 1,200 of its roughly 8,000 US stores, citing their struggling performance.
"This Thanksgiving, Walgreens' hourly workers faced the impossible choice between losing pay and spending the holiday with their loved ones," Sanders (Vt.)—who is the ranking member of the Senate Health, Education, Labor, and Pensions (HELP) Committee—wrote Tuesday in a letter to Sycamore Partners founder and managing director Stefan Kaluzny.
"Walgreens employs 220,000 employees, the vast majority of whom are hourly workers... Sycamore Partners' decision to cut paid holidays for these hourly workers is unfortunately not surprising," the senator continued. "The firm follows the private equity playbook of buying businesses and aggressively extracting profit while using and abusing workers."
"For example, just one year after Sycamore Partners purchased Staples, the firm extracted $1 billion from the company as it closed 100 stores and laid off 7,000 workers," Sanders noted. "That same year, Sycamore Partners drove Nine West into bankruptcy and was accused of siphoning off over $1 billion in funds."
"Meanwhile, from 2016-22, companies owned by Sycamore Partners racked up over $3 million in labor violations, including wage-and-hour and workplace safety and health violations," he added.
During the holiday season, we all want to spend time with our loved ones. And yet, just two months after buying Walgreens for $10 billion, the private equity firm Sycamore Partners stripped hourly workers of paid vacation, including Christmas and New Year’s Day. Shameful.
[image or embed]
— Senator Bernie Sanders (@sanders.senate.gov) December 23, 2025 at 9:41 AM
Sanders contrasted a reality in which "60% of Americans are living paycheck to paycheck" with the fact that "more private equity managers make over $100 million annually than investment bankers, top financial executives, and professional athletes combined."
"While the rich get richer, workers are struggling, and your decision to cut workers' paid vacation leave is making the problem worse," he stressed. "Some Walgreens workers make as little as $15 an hour. Cutting their paid leave will make it even more difficult for these workers to pay for housing, childcare, healthcare, and groceries."
"In short," Sanders concluded, "Sycamore Partners is forcing workers to sacrifice their basic needs for private equity profit."