
SUBSCRIBE TO OUR FREE NEWSLETTER
Daily news & progressive opinion—funded by the people, not the corporations—delivered straight to your inbox.
5
#000000
#FFFFFF
To donate by check, phone, or other method, see our More Ways to Give page.
Daily news & progressive opinion—funded by the people, not the corporations—delivered straight to your inbox.

At least 717 US companies filed for bankruptcy through November 2025—the highest figure recorded since the aftermath of the Great Recession.
Businesses in the United States have filed for bankruptcy this year at a level not seen since 2010 as President Donald Trump's tariff regime has jacked up costs for companies in manufacturing and other major sectors.
Citing data from S&P Global Market Intelligence, the Washington Post reported over the weekend that at least 717 US companies filed for bankruptcy through November 2025, the highest figure recorded since the aftermath of the Great Recession and a 14% increase compared to the same period last year.
"Companies cited inflation and interest rates among the factors contributing to their financial challenges, as well as Trump administration trade policies that have disrupted supply chains and pushed up costs," the Post noted. "But in a shift from previous years, the rise in filings is most apparent among industrials—companies tied to manufacturing, construction, and transportation. The sector has been hit hard by President Donald Trump’s ever-fluid tariff policies—which he’s long insisted would revive American manufacturing."
Recent data shows that the US has lost 49,000 manufacturing jobs since Trump's return to office.
The bankruptcy figures add to the growing pile of evidence showing that Trump's tariffs and broader policy agenda have harmed the US economy—weakening job growth, driving the unemployment rate up to the highest level since the Covid-19 pandemic, and worsening the nation's cost-of-living crisis.
Democrats immediately seized on the new reporting as evidence of Trump's failed stewardship of the US economy, messaging that's likely to be central as the 2026 midterms approach.
Trump's economic policies did this. pic.twitter.com/tRfcNxAyAU
— Sean Casten (@SeanCasten) December 27, 2025
Ken Martin, chair of the Democratic National Committee, said Monday that "when Donald Trump signed his Big Ugly Bill into law, he cemented the Republican Party as the party of billionaires and special interests—not working families, farmers, or small business owners."
"While millions of working families are already being squeezed to afford groceries, utilities, and rent, Trump chose to strip them of their healthcare and food assistance just so he could give his ultrawealthy friends and donors an extra buck," said Martin. "Make no mistake: Trump’s ‘signature achievement’ will be the nail in the coffin for the Republican majority when voters head to the polls next November."
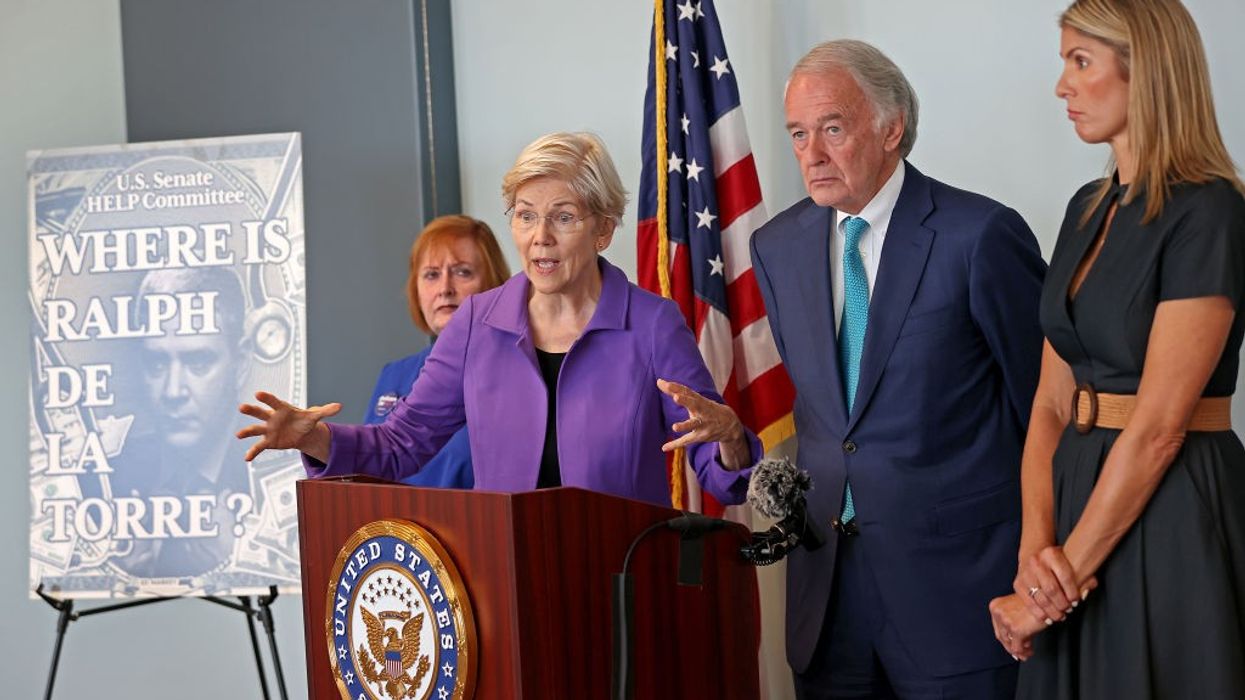
"Union-busting, pollution, and bankruptcy aren't side effects of the private equity model: They are the model," said one campaigner backing the bill. "It's a smash-and-grab, plain and simple."
Less than a month away from the U.S. general election, over a dozen congressional Democrats on Thursday renewed their fight to "fundamentally reform the private equity industry" with a bill that Rep. Mark Pocan said "will finally hold these predatory firms accountable and protect workers from being plundered by corporate greed."
"It's long past time for billionaires and big corporations to stop gambling with hardworking Americans' and their communities' assets in service of corporate greed," declared Pocan (D-Wis.), who is leading the Stop Wall Street Looting Act with Congressional Progressive Caucus Chair Pramila Jayapal (D-Wash.) and Sen. Elizabeth Warren (D-Mass.).
"In Wisconsin, we've seen what happens when private equity firms like Sun Capital raid companies for their wealth and leave workers and communities to pick up the pieces," he noted. "When Sun Capital took over Shopko—a Wisconsin-based retail chain that had stood strong for more than 50 years—they drained it dry, buried it in debt, pushed it into bankruptcy, and abandoned roughly 14,000 workers."
"Private equity takeovers are legal looting that make a handful of Wall Street executives very rich while costing thousands of people their jobs, putting valuable companies out of business, and in the case of healthcare, is literally a matter of life and death."
Warren's state is also dealing with fallout from the industry. As The Boston Globe reported Thursday, the legislation is "designed to rein in the growing power of private equity firms and limit the sort of leveraged buyout deals that led to the crisis at Steward Health Care, whose bankruptcy continues to roil communities in Massachusetts and seven other states."
The bill "was reintroduced in part as a response to the unfolding crisis at Steward, which before its bankruptcy was the nation's largest private for-profit hospital system," the newspaper noted. It follows the Senate's unanimous approval of a resolution to hold CEO Dr. Ralph de la Torre in criminal contempt of Congress for his refusal to comply with a subpoena to testify before a committee. Shortly after the vote—the first of its kind since 1971—he resigned.
"Private equity takeovers are legal looting that make a handful of Wall Street executives very rich while costing thousands of people their jobs, putting valuable companies out of business, and in the case of healthcare, is literally a matter of life and death," Warren, a former bankruptcy law professor, said Thursday. "Our bill is designed to close loopholes and end incentives for private equity pillaging—and it will make sure what happened at Steward never happens again."
As a fact sheet from the sponsors details, the bill would make private equity firms responsible for liabilities including debt, legal judgments, and pension-related obligations; limit how much money they can extract from companies; close a loophole they have used to conceal assets from bankruptcy courts; implement various protections for workers and customers; increase transparency; impose guardrails for receiving public funds; and drive real estate investment trusts out of healthcare.
"From healthcare to housing, millions of Americans are seeing private equity take over companies with the promise of improving services, only to strip them for parts and hurt both workers and working families," said Jayapal. "It's time for Congress to take action to protect Americans from the dangers of private equity and corporate greed, and that's exactly what our Stop Wall Street Looting Act will do."
The legislation is backed by Reps. Raúl Grijalva (D-Ariz.), Rick Larsen (D-Wash.), Barbara Lee (D-Calif.), Delia Ramirez (D-Ill.), Jan Schakowsky (D-Ill.), Alexandria Ocasio-Cortez (D-N.Y.), and Eleanor Holmes Norton (D-D.C.), along with Sens. Tammy Baldwin (D-Wis.), Jeff Merkley (D-Ore.), Bernie Sanders (I-Vt.), Tina Smith (D-Minn.), and Ed Markey (D-Mass.).
The bill is also endorsed by dozens of groups including the American Federation of Teachers, Americans for Financial Reform, Economic Policy Institute, Indivisible, National Employment Law Project, National Nurses United, Public Citizen, Service Employees International Union, Student Borrower Protection Center, Take on Wall Street, United for Respect, and Working Families Party.
"Union-busting, pollution, and bankruptcy aren't side effects of the private equity model: They are the model," said Porter McConnell of Take on Wall Street. "It's a smash-and-grab, plain and simple. That's why we are so pleased to see comprehensive legislation like the Stop Wall Street Looting Act introduced in Congress today. We created the loopholes in the law that allowed the private equity industry to thrive, and we can end them."
United for Respect co-executive directors Bianca Agustin and Terrysa Guerra stressed that "Wall Street private equity firms have proven themselves to be a parasite on workers, our economy, and American retailers by gutting companies for profit and driving mass layoffs. Holding billionaire profiteers accountable for the damage they do to our working families and communities is imperative to addressing growing economic inequality."
"The Stop Wall Street Looting Act will help close loopholes in our laws that for too long have allowed private equity to pillage companies and amass huge profits while workers lose their jobs and are left with nothing," they added. "United for Respect is proud to support this bill—and we need all legislators to join us in protecting workers and putting Wall Street on the hook for the havoc they reap."
While the bill is unlikely to go anywhere in the currently divided Congress, it's a clear statement from the sponsors where they stand, as early voting gets underway to determine the future of the Senate and House of Representatives as well as the next occupant of the White House—Democratic Vice President Kamala Harris or former Republican President Donald Trump.
"Selling Massachusetts doctors to another private equity firm could be a disaster," said Sen. Elizabeth Warren. "Regulators must scrutinize this deal."
Both of Massachusetts' Democratic U.S. senators on Tuesday expressed concern about a private equity firm striking a $245 million deal to buy the nationwide physicians network of the for-profit Steward Health Care, which filed for bankruptcy in May.
The network, Stewardship Health, has about 5,000 employees across nine states and serves around 400,000 patients, according to Steward. It is set to be acquired by Rural Healthcare Group, an affiliate of Kinderhook Industries.
"Steward also operates eight hospitals in Massachusetts," The Boston Globe reported Monday. "Last month, it said it will close two of them, Carney Hospital in Dorchester and Nashoba Valley Medical Center in Ayer, by August 31. It's currently in the final stages of negotiations to sell the other six."
Sen. Elizabeth Warren (D-Mass.), a former bankruptcy law professor, noted the planned closures in her social media post urging regulators to review the deal.
"Two Massachusetts hospitals are closing and communities are suffering because of private equity's looting of Steward," she said. "Selling Massachusetts doctors to another private equity firm could be a disaster. We can't make the same mistake again. Regulators must scrutinize this deal."
In March, Steward had confirmed plans for the Optum unit of insurer UnitedHealth to buy the network, but that was never finalized.
"As part of the ongoing Chapter 11 proceedings, following a robust and active bidding process, Steward Health Care is pleased to have reached an agreement with Rural Healthcare Group," Steward Health Care president Mark Rich said in a Monday statement. "Kinderhook has over 20 years of experience investing in mid-sized healthcare businesses that serve the nations' most vulnerable populations."
"Kinderhook's investments are focused on protecting access to high-quality healthcare in communities that are truly underserved," Rich added. "Rural Healthcare Group is a well-respected group of healthcare professionals that specifically focuses on underserved and underinsured areas. We are confident that Stewardship Health will continue its stellar treatment of the patient population as a result of this transaction."
According to the Globe:
In an attachment to an overnight filing with U.S. Bankruptcy Court in Houston, the company listed the purchase price as $245 million in cash.
That price is subject to change, the filing indicated, depending on several factors still to be determined, including whether U.S. Family Plan at Brighton Marine, a Boston health insurance agency, is included in the transaction. The filing listed the buyer as Brady Health Buyer LLC, a company set up by New York-based Kinderhook to purchase Stewardship.
The newspaper noted that "the sale to Rural Healthcare is subject to the approval of U.S. Bankruptcy Judge Christopher Lopez at a Houston hearing scheduled for Friday. It's also subject to regulatory approval in Massachusetts and other states."
As Common Dreams reported last month, Sen. Bernie Sanders (I-Vt.), chair of the Senate Committee on Health, Education, Labor, and Pensions (HELP), led the panel in bipartisan votes to authorize a probe into the bankruptcy of Steward Health Care (20-1) and subpoena CEO Ralph de la Torre (16-4).
The same day, Sen. Ed Markey (D-Mass.), a committee member, and Rep. Pramila Jayapal (D-Wash.) introduced the Health Over Wealth Act, which would increase the powers of the U.S. Department of Health and Human Services to monitor and block private equity deals in the healthcare industry.
"Private equity firms buying up healthcare systems are simply bad news for patients, leading to worse health outcomes and higher bills," Jayapal said at the time. "We have a duty to protect patients from greedy corporations that are prioritizing their bottom line over patient care."
In response to news of the doctors group deal, Markey said Tuesday that "private equity did to Steward what it will keep doing to hospitals and physician networks across the U.S.—unless we put guardrails on them. We need to pass my Health Over Wealth Act to get corporate greed out of healthcare for good."
Bankruptcy was designed so people could start over, but these days, the only ones starting over are those with enough political clout to shape bankruptcy laws to their liking.
Within days of a nearly $150 million judgment against former New York Mayor Rudy Giuliani for defaming Ruby Freeman and Shaye Moss, the election workers Giuliani falsely claimed stole the 2020 election in Georgia for President Joe Biden, Giuliani filed for bankruptcy.
He thereby shielded himself from having to surrender his assets to fulfill the judgment, at least in the near term.
The long term may be quite long. Freeman and Moss may not see a penny of that judgment for many years, and when they do, it’s likely to be far less than $150 million.
The prevailing myth that America has a “free market” existing outside and apart from government prevents us from understanding that the very rules by which the market runs—including the basic one about what to do when someone can’t or won’t pay what they owe—are made by lawmakers.
One of the most basic of all questions in a market economy is what to do when someone can’t pay what they owe. The U.S. Constitution (Article I, Section 8, Clause 4) authorizes Congress to enact “uniform Laws on the subject of Bankruptcies throughout the United States.”
Congress has done so repeatedly. In the last few decades, Congress’ changes have reflected the demands of the wealthy, giant corporations, and Wall Street banks, which have made it harder for average people to declare bankruptcy but easier for themselves to do it.
Many people are too broke to go bankrupt. Filing for bankruptcy costs money, as does hiring an attorney (which is the best way to make sure you actually get debt relief). Because attorney fees, like other debts, are wiped out in a bankruptcy, most bankruptcy lawyers require clients to pay in full before filing.
In an economy where nearly half of adults say that if they were hit with an emergency expense of $400, they wouldn’t have the cash on hand to cover it, large numbers of people simply can’t afford those upfront costs.
The 2005 bankruptcy bill pushed by Wall Street worsened the problem. To prevent people from cheating their lenders, the bill put new burdens on debtors and their lawyers. The extent of such abuses was questionable, but the new requirements have driven up attorney fees nationwide by about 50%. The result? Even fewer filings.
Bankruptcy was designed so people could start over. But these days, the only ones starting over are those with enough political clout to shape bankruptcy laws to their liking, and enough money to hire bankruptcy lawyers to use those laws to their full advantage.
On the opening day of Trump Plaza in Atlantic City in 1984, Donald Trump stood in a dark topcoat on the casino floor celebrating his new investment as the “finest building in the city and possibly the nation.”
Thirty years later, after the Trump Plaza folded, Trump was on Twitter praising himself for his “great timing” in getting out of the investment. He got a giant tax write-off, too.
But some 1,000 of his former employees were left holding the bag—without jobs, and with homes worth a fraction of what they paid for them. They couldn’t declare bankruptcy. Chapter 13 of the bankruptcy code—whose drafting was largely the work of the financial industry—prevents homeowners from declaring bankruptcy on mortgage loans for their primary residence.
The Granddaddy of all failures to repay occurred in September 2008 when Lehman Brothers went into the largest bankruptcy in history, with more than $691 billion of assets and far more in liabilities.
Some commentators (including yours truly) urged that the rest of Wall Street should be forced to grapple with their problems in bankruptcy, too.
But Lehman’s bankruptcy so shook the street that Henry Paulson Jr., George W. Bush’s outgoing secretary of the treasury (and, before that, head of Goldman Sachs), persuaded Congress to authorize several hundred billion dollars of funding to protect the other big banks from going bankrupt.
Paulson didn’t explicitly state that big banks were too big to fail. They were, rather, too big to be reorganized under bankruptcy—which would, in Paulson’s view, have threatened the entire financial system.
The real burden of Wall Street’s near meltdown fell on homeowners. As home prices plummeted, many found themselves owing more on their mortgages than their homes were worth and unable to refinance.
Some members of Congress tried to amend the bankruptcy law so distressed homeowners could use bankruptcy, which would have helped prevent the banks from foreclosing on their homes. But the financial industry (among the largest donors to both parties) claimed this would greatly increase the cost of home loans (no convincing evidence showed this to be the case), and the bill died.
Subsequently, more than 5 million people lost their homes.
Another group of debtors who can’t use bankruptcy to renegotiate their loans are former students laden with student debt.
Student loans are now about 10% of all debt in the United States, second only to mortgages and higher than auto loans and credit card debt. But the bankruptcy code doesn’t allow student debts to be worked out under its protection.
If graduates don’t meet their payments, the law allows lenders to garnish their paychecks. If they are still behind on student loan payments by the time they retire, lenders can even garnish their Social Security checks.
The only way graduates can reduce their student debt burdens—according to a provision enacted at the behest of the student loan industry—is to prove that repayment would impose an “undue hardship” on them and their dependents.
This is a stricter standard than bankruptcy courts apply to gamblers trying to reduce their gambling debts.
For years, Purdue Pharma, the maker of the prescription painkiller OxyContin, was entangled in civil lawsuits seeking to hold it accountable for its role in the spiraling opioid crisis.
A major settlement reached last year seemed to end thousands of those cases. It exempted members of the billionaire Sackler family, which once controlled the company, from all civil lawsuits in exchange for billions of dollars toward fighting the epidemic (although aware of OxyContin’s risk for abuse, members of the family had continued to aggressively market it).
Under the deal, the Sacklers do not have to personally declare bankruptcy and are insulated from liability even without the consent of all of those who could potentially sue them. (The Supreme Court has taken up the case.)
The prevailing myth that America has a “free market” existing outside and apart from government prevents us from understanding that the very rules by which the market runs—including the basic one about what to do when someone can’t or won’t pay what they owe—are made by lawmakers.
The real question is whose interests those lawmakers are pursuing. Are they working for the vast majority of Americans, or are they beholden to those at the top? The recent history of bankruptcy—right up to Rudy Giuliani’s use of it last week—provides a clear answer.

"I don't want their money," one woman who lost a son to the opioid crisis said of the Sackler family. "I want them in prison."
At the U.S. Supreme Court on Monday, families whose loved ones are among the tens of thousands of Americans who have died of opioid use disorder each year over the past two decades rallied to push the nine justices to reject a proposed bankruptcy plan that would give the former owners of Purdue Pharma legal immunity—with many joining the U.S. Justice Department in arguing that the company should not be released from accountability for the opioid epidemic.
Purdue Pharma filed for bankruptcy in 2019, as the number of Americans killed by opioids hit 50,000 and the OxyContin manufacturer faced thousands of lawsuits alleging its aggressive marketing of the addictive painkiller had fueled the rising death toll.
The company agreed to settle the lawsuits for $10 billion, with the Sackler family—which oversaw Purdue when OxyContin was introduced and flooded communities across the U.S.—contributing $4 billion. In exchange, the Sacklers would be shielded from future lawsuits.
The bankruptcy plan—which now includes $6 billion from the Sacklers following a push from lawsuit plaintiffs—has been approved by state and local governments, tribes, and families and individuals who would be entitled to money.
But the U.S. Trustee Program, a watchdog at the Justice Department, has joined some families in arguing that the Sacklers should not be shielded from liability for the opioid crisis.
"No Sackler immunity at any $$," read one sign held by a woman outside the Supreme Court on Monday, while another said, "My dead son does not release Sacklers."
The issue at hand in the case, Harrington v. Purdue Pharma, is whether it is legal to give a third party—the Sackler family—legal immunity in a bankruptcy case even though they themselves have not declared bankruptcy, also known as nonconsensual third-party release.
A lawyer for groups and individuals told the court that families and governments are highly unlikely to get any more out of Purdue and the Sacklers than the money the company and family have offered as part of the deal.
The plan would include $161 million in a trust set aside for Native American tribes and $700 million to $750 million in a trust for families and individuals who were able to file claims, with payouts expected to range from about $3,500 to $48,000. Governments would use the money to set up addiction treatment centers and other programs to mitigate the opioid crisis.
"Forget a better deal—there is no other deal," lawyer Pratik Shah told the Supreme Court on Monday.
Curtis Gannon, representing the U.S. Trustee Program, noted that the Sackler family already showed that a "better deal" could be possible when it offered $6 billion for the plan instead of $4 billion. The Justice Department is advocating for a new settlement that would not include nonconsensual third-party releases, saying the current bankruptcy deal violates federal law.
"We do hope there is another deal at the end of this," said Gannon.
The justices appeared split on the case, in which a ruling is expected next summer. Justice Ketanji Brown Jackson noted that appeals courts do not allow bankruptcy plans that take away the rights of alleged victims to sue parties that have not declared bankruptcy.
Outside the court, Alexis Pleus, who lost her son to opioid use disorder, told Aneri Pattani of KFF Health News that many families, including hers, will not be entitled to money under the current deal because they are required to provide records such as the original opioid prescription.
Beth Macy, author of the book Dopesick, told CNN Monday morning that while some families "are divided" about whether the bankruptcy plan and payouts should move forward, as the U.S. Trustee Program "has pointed out, only 20% of the families who were eligible to vote on [the proposal], even voted."
"I don't want their money," Jen Trejo, whose son Christopher was prescribed OxyContin at age 15 and died of an overdose when he was 32, told Pattani. "I want them in prison."
"The United States can pay any debt it has because we can always print money to do that. So there is zero probability of default." -- Former Fed Chairman Alan Greenspan on Meet the Press, August 2011
In a post on "Sovereign Man" dated August 14th, Simon Black argued that Donald Trump may be the right man for the presidency:
[T]here's one thing that really sets him apart, that, in my opinion, makes him the most qualified person for the job:
Donald Trump is an expert at declaring bankruptcy.
When the going gets tough, Trump stiffs his creditors. He's done it four times!
Candidly, this is precisely what the Land of the Free needs right now: someone who can stop beating around the bush and just get on with it already.
Black says the country is officially bankrupt, with the government's financial statements showing a negative net worth of $17.7 trillion:
Nations that pass the economic point of no return can't rebuild until they hit rock bottom. And the US is way past that point. So let's get on with it already and hit the reset button.
Black recommends doing this by defaulting, preferably on Social Security and Medicare. But that is unlikely to suit this leading Republican candidate. As Trump said on Meet the Press on August 16:
I want people to be taken care of from a healthcare standpoint.... I want to save Social Security without cuts. I want ... a strong country with very little debt.
How can the country remain strong with very little debt, without defaulting on Social Security, Medicare, or the federal debt itself?
There is a way. The government can reduce the debt by buying it - and ripping it up. The debt can be bought either with debt-free US Notes of the sort issued during the Civil War, or with US dollars issued by the Federal Reserve in the form of "quantitative easing."
The vast majority of the money supply today is created by banks when they make loans, as the Bank of England recently acknowledged. Banks create money by "monetizing" debt, turning loans into the digital deposits that make up most of the circulating money supply. The government could push the reset button by monetizing its own debt, turning it into what it should have been all along - debt-free, interest-free dollars. As Thomas Edison observed in 1921:
If the Nation can issue a dollar bond it can issue a dollar bill. The element that makes the bond good makes the bill good also. . . . It is absurd to say our Country can issue bonds and cannot issue currency. Both are promises to pay, but one fattens the usurer and the other helps the People.
That is not just a quaint idea from the 1920s. Credible authorities are making that argument today. In November 2010, Dean Baker, co-director of the Center for Economic and Policy Research in Washington, wrote in response to the debt ceiling crisis:
There is no reason that the Fed can't just buy this debt (as it is largely doing) and hold it indefinitely. If the Fed holds the debt, there is no interest burden for future taxpayers. The Fed refunds its interest earnings to the Treasury every year. Last year the Fed refunded almost $80 billion in interest to the Treasury, nearly 40 percent of the country's net interest burden. And the Fed has other tools to ensure that the expansion of the monetary base required to purchase the debt does not lead to inflation.
In 2011, Republican presidential candidate Ron Paul proposed dealing with the debt ceiling by simply voiding out the $1.7 trillion in federal securities then held by the Fed. As Stephen Gandel explained Paul's solution in Time Magazine, the Treasury pays interest on the securities to the Fed, which returns 90% of these payments to the Treasury. Despite this shell game of payments, the $1.7 trillion in US bonds owned by the Fed is still counted toward the debt ceiling. Paul's plan:
Get the Fed and the Treasury to rip up that debt. It's fake debt anyway. And the Fed is legally allowed to return the debt to the Treasury to be destroyed.
Congressman Alan Grayson, a Democrat, also endorsed this proposal.
In February 2015, financial author Richard Duncan made a strong case for going further than monetizing existing debt. He argued that under current market conditions, the US could rebuild its collapsing infrastructure with quantitative easing without causing price inflation. Prices go up when demand (money) exceeds supply (goods and services); and with automation and the availability of cheap labor in vast global markets today, supply (productivity) can keep up with demand for decades to come. Duncan observed:
Quantitative Easing has only been possible because it has occurred at a time when Globalization is driving down the price of labor and industrial goods. The combination of fiat money and Globalization creates a unique moment in history where the governments of the developed economies can print money on an aggressive scale without causing inflation.
They should take advantage of this once-in-history opportunity to borrow more in order to invest in new industries and technologies, to restructure their economies and to retrain and educate their workforce at the post-graduate level. If they do, they could not only end the global economic crisis, but also ensure that the standard of living in the developed world continues to improve, rather than sinking down to third world levels.
Abraham Lincoln revived the colonial system of government-issued money when he endorsed the printing of $450 million in US Notes or "greenbacks" during the Civil War. The greenbacks not only helped the Union win the war but triggered a period of robust national growth and saved the taxpayers about $14 billion in interest payments (figuring an average of $300 million in outstanding US Notes over 150 years, at an average real interest rate of 2.6% compounded annually). The US federal debt has been growing ever since 1835, when President Andrew Jackson last paid it off and closed down the Second US Bank. If judicious use of US Notes had continued to the present, there might now be no federal debt at all.
The Inflation Snag
In short, the sovereign debt crisis can be solved by issuing sovereign money. But is there really such a thing as a free lunch? Wouldn't buying up the debt with newly-issued money lead to a hyperinflationary disaster?That was the fear when the Federal Reserve began its QE program in 2008. But the Fed has now monetized $4.5 trillion in QE ($2.7 trillion of which consisted of buying back federal securities, and these fears have not materialized. The stock market has gone up, but not apparently from an increased money supply. More likely it is from very low interest rates, making bonds unattractive and facilitating stock buybacks and borrowing to invest. The cost of produce has gone up, but it is largely because of drought in California, which supplies nearly half the country's fruits, vegetables and nuts; and because speculators have moved into foodstuffs. Despite all that, the overall inflation rate remains at manageable levels.
Why didn't $4.5 trillion in QE drive prices into the stratosphere? As financial writer Matthew Kerkhoff explained in a November 2013 article, quantitative easing is just an asset swap:
When the Fed creates $85 billion, it uses this money to buy bonds . . . . When the Fed creates and gives $85 billion in reserves to its member banks, it removes $85 billion worth of assets (bonds) from the balance sheets of those same member banks. The result is that no new net financial assets enter the economy. . . .
It's much more accurate to think of the Fed's QE program as an asset swap. In fact it's even more accurate to think of it as a liquidity swap. . . . In this context liquidity refers to the ease with which money can be used.
Bonds are more cumbersome to spend than cash, but they still represent purchasing power. Government securities that can be quickly converted into cash or that are near maturity are considered a form of "near money." When the Fed buys the bonds, it is simply converting this less-liquid money back into more-liquid money. As Warren Mosler and John Carney explain on CNBC.com:
Quantitative easing is about the Fed buying Treasury securities. When you (voluntarily) sell them to the Fed, at current market prices, the Fed just shifts your dollars from your securities account to your bank's reserve account, all at the Fed. So why should that do anything to the economy? You have the same amount of dollars, and you could have shifted them in the same market place any time you wanted in any case.
The QE liquidity swap does not increase the circulating money supply. The money supply increased when the bonds were issued - when the debt was incurred and the government spent the funds.
Adding to the federal debt beyond its current level (i.e. by funding infrastructure with new QE that is not repaid with taxes) would increase the money competing for goods and services. But the economy actually needs that increased "demand" in order to promote full employment (one of the Fed's mandates). Demand (money) precedes supply (goods and services). The money has to be out there searching for goods and services before employers will add more workers to create this increased supply. Money can be added to the point of full productive capacity (full use of workers, supplies and machines) before adding more will drive up prices. And as Richard Duncan observes, we are a long way from full productive capacity now.
Whether full productive capacity would exhaust the earth's resources is another question, but there are many ways to put people to work that either don't use physical resources (e.g. education, art, social service, environmental cleanup) or that actually make resource use more efficient (investment in improved infrastructure, sustainable energy, research and development).
Time to Reset
Back to Donald Trump. Besides his experience with bankruptcy, Trump, along with Bernie Sanders on the left, is unique in not being beholden to big money. Sanders does not take it, and Trump does not need it. If either candidate makes it to the White House, he will be in a position to stand up to Wall Street and do what is right for the country. And that includes restoring the power to issue the national money supply to the people of the nation through their representative government.

When the global economic crisis hit in 2008, Iceland suffered terribly--perhaps more than any other country. The savings of 50,000 people were wiped out, plunging Icelanders into debt and placing 25 percent of its homeowners in mortgage default.
Now, less than a decade later, the nation's economy is booming. And this year it will become the first culturally European country that faced collapse to beat its pre-crisis peak of economic output.
That's because it took a different approach. Instead of imposing devastating austerity measures and bailing out its banks, Iceland let its banks go bust and focused on social welfare policies. In March, the International Monetary Fund announced that the country had achieved economic recovery "without compromising its welfare model" of universal health care and education.
Iceland allowed those responsible for the crisis--its bankers--to be prosecuted as criminals. Again, a sharp contrast to the United States and elsewhere in Europe, where CEOs escaped punishment.
"Why should we have a part of our society that is not being policed or without responsibility?" asked special prosecutor Olafur Hauksson in the wake of the collapse. "It is dangerous that someone is too big to investigate--it gives a sense there is a safe haven."
By refusing to allow its currency, the krona, to suffer ultra-low inflation to protect the assets of the rich--as in the rest of the West--Iceland let the krona tumble. The resulting inflation and higher prices have helped its export industries, unlike what happened in many European Union countries, which are contending with ongoing deflation.
On Monday, Iceland's Finance Minister Bjarni Benediktsson announced the introduction of a 39 percent tax on creditors seeking to reclaim assets from the country's failed banks. As The Guardian explains, this is "an attempt to prevent foreign investors rushing en masse to withdraw billions currently frozen in Iceland's financial system."
This tax has been introduced as the country winds down capital controls imposed in response to the crisis. Again flouting free market orthodoxy, this move restricts Icelanders' ability to move their money out of the country in order to protect the krona. Initially intended to expire after six months, the controls have been in place for more than six years.
As a result, it's estimated that about 1,200 billion Icelandic krona have been frozen--the equivalent of $9 billion. If capital controls were removed, Iceland could face a spate of bankruptcies and problems with liquidity. "There is not sufficient foreign currency to release 1,200bn [krona] in foreign currency," The Guardian quoted Benedikt Gislason, an adviser to the government, as saying. "The Icelandic economy would not survive."
All of these actions have, unsurprisingly, drawn the ire of other countries--in ideological and measurable ways. By refusing to honor bank guarantees given by British and Dutch investors in Icesave--a subsidiary of one of Iceland's main banks, Landsbanki--Iceland created enemies of its European neighbors. But it has now repaid 85 percent of U.K. claims, and the Icelandic finance minister announced recently that all will be settled by the end of the year.
When asked why Iceland was enjoying such a strong recovery while everyone else is still mired in debt, President Olafur Ragnar Grimmson said in 2013:
"Why are the banks considered to be the holy churches of the modern economy? Why are private banks not like airlines and telecommunication companies and allowed to go bankrupt if they have been run in an irresponsible way? The theory that you have to bail out banks is a theory that you allow bankers enjoy for their own profit, their success, and then let ordinary people bear their failure through taxes and austerity. People in enlightened democracies are not going to accept that in the long run."
There you have it. Instead of conceding to the crooks who made the mess, Iceland listened to its people. And the data speaks for itself.
Ex-US Treasury Secretary Timothy Geithner, President Barack Obama's key economic adviser since 2009, is joining private-equity firm Warburg Pincus, according to a statement on Saturday.
Geithner, who has spent the last 26 years in 'public service', will become president at the Wall Street-based corporate buyout firm starting on March 1st, according to a press release today from Warburg Pincus.
When Geithner left his post with the Treasury Department in January 2013, Matt Taibbi told Democracy Now: "He's the architect of "too big to fail. When this all blows up -- and it's going to blow up, for sure, because things can't continue the way they are right now -- people are going to look back in history, and they're going to say, "Who was to blame for this?" And Timothy Geithner is going to be the guy who designed this entire system."
Politico reports:
Private-equity firms in the financial sector played a leading role in the 2012 presidential campaign, with Democrats criticizing Republican candidate Mitt Romney over deals involving his firm, Bain Capital, that led to layoffs at different companies.
For instance, in May 2012 the Obama campaign ran an ad concerning Bain's role in the struggles of American Pad and Paper that featured former employees of the company criticizing Romney.
Defenders of the industry argue it can help turn around struggling companies, but its critics, as the 2012 campaign showed, point to instances where these leveraged buyouts and the efforts to nurse a company back to health can often lead to large layoffs.
* * *
Romney Economics: Job Loss and Bankruptcy at AmpadLearn more: https://www.romneyeconomics.com With American Pad & Paper (Ampad), Mitt Romney and his partners took a small ...