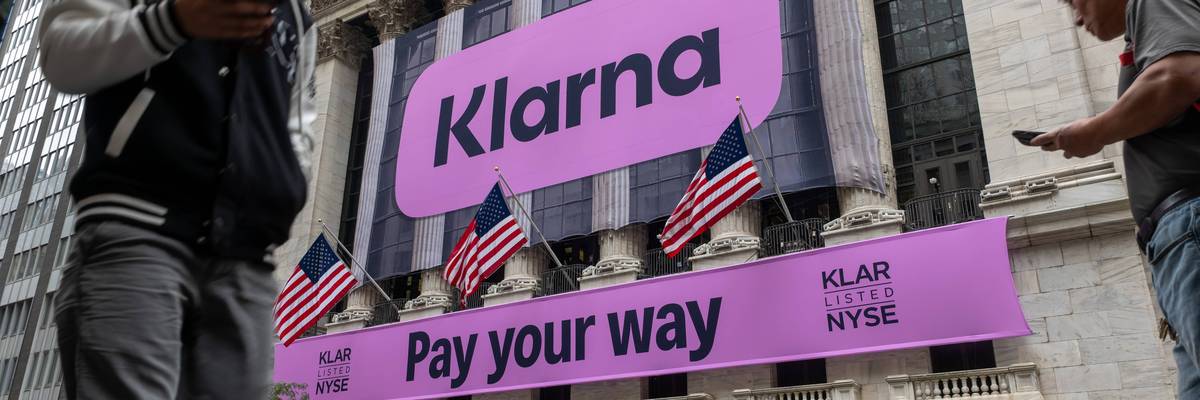
A banner for the online lender Klarna is displayed at the New York Stock Exchange on September 10, 2025 in New York City.
In Trump's Economy, Companies Offer 'Buy Now, Pay Later' for Utilities as Costs Surge
Lending apps are offering credit to consumers struggling to afford basic necessities, including electricity, broadband, groceries, and more as prices rise.
Companies that provide "buy now, pay later" loans are increasingly offering their products to Americans struggling to afford utilities and other necessities as costs rise across the US economy, with President Donald Trump's illegal war on Iran pushing up energy prices while wage growth slows.
The New York Times reported Monday that "the lending apps Flex and Zip allow customers to take out loans to pay for their broadband, electricity, health insurance, mobile phone service, mortgage, and water bills," while Affirm "has started providing some tenants loans to extend their monthly rent payment for a few weeks." On the homepage of its website, Affirm is currently promoting its product for school supplies as prices for basic items surge.
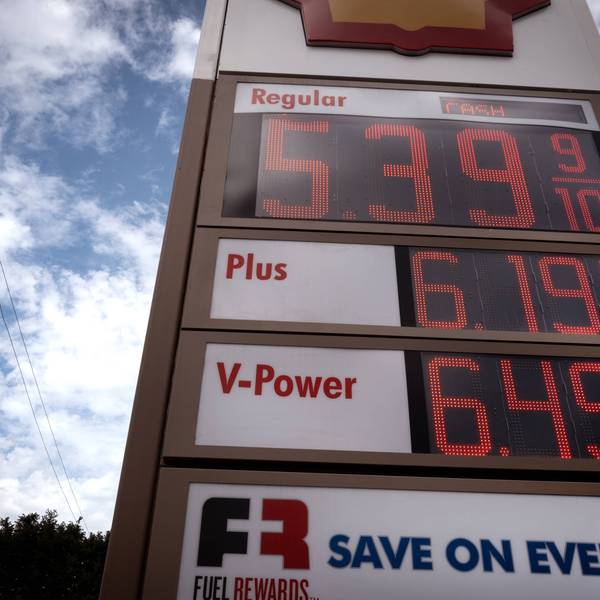
Despite Trump's pledge to cut household electricity costs in half and "bring down the prices of all goods," federal data shows electricity prices are up 18% since the start of the president's second White House term. On Monday, the average price for a gallon of gas in the US reached $4.06—the highest ever recorded for mid-August.
Recent polling by Data for Progress shows that 38% of "buy now, pay later" users have turned to the product to cover gasoline costs. Nearly half—46%—have used it for groceries, 42% for medical or dental care, 39% for utility bills, and 22% for childcare.
Last month, the advocacy group Protect Borrowers released a detailed report showing that buy now, pay later lenders are "touting shiny and oftentimes deceptive offers of zero-interest, fee-free installment loans to millions of Americans struggling with the rapidly rising costs of groceries, rent, utility bills, takeout, new clothes, medical care, and more."
"Leading BNPL lenders currently include Affirm, Klarna, Afterpay, PayPal, Synchrony, Splitit, Sezzle, and Zip, but more are popping up by the day, largely funded by private equity firms and venture capitalists looking to cash in on families’ financial desperation," the report states. "BNPL loans are packed to the brim with financing fees, late fees, and other junk fees. Many BNPL loans feature late fees of $7 to $8 per missed payment, up to an aggregate cap of 25% of the purchase price. Additional fees may be charged for financing, if the user does not set a bank account as the default method of payment, reschedules an upcoming payment, or has non-sufficient funds or a bounced payment."
The Times pointed to June Federal Reserve research showing that Americans collectively spent $160 billion through buy now, pay later programs last year, nearly twice what US consumers spent in 2023.
"That’s still a fraction of the more than $3 trillion US shoppers spend annually on consumer credit cards," the Times noted. "But the industry continues to expand by double-digit rates each year."
Jennifer Zhang, a policy analyst at Protect Borrowers, has called on the US Congress to enact "sweeping protections" that "end deceptive pricing, bring down the cost of BNPL debt, ban predatory practices that harm consumers, and empower Americans to enforce their rights under the law."
"BNPL loans are expensive and risky, and often worsen financial outcomes for borrowers who come to rely on them to make ends meet. However, millions of Americans are being driven into these debt products just as they’re trying to get by. Prices are soaring and show no signs of coming down anytime soon," Zhang wrote. "Americans need help."
We are at a crossroads
This country and this world are at a monumental crossroads. In a few short weeks, US voters will have an opportunity to beat back the forces of fascism and confront the billionaires who are rigging the economy, our media system, and our democracy, making it increasingly impossible for ordinary people to get by. We’re not just talking about the election. We’re talking about what must be done once these fascist elements are vanquished from power. We need a bolder set of solutions than what either major party has so far been willing to offer and a working-class movement ready to fight like hell for it. Trump didn't emerge from nowhere. The conditions that fueled MAGA authoritarianism were created by decades of radical neoliberal economic policies and a corrupt political system dominated by corporate interests. They slashed taxes on the super-rich, promising that the benefits would trickle down. They said giveaways to the corporate titans would make life more affordable for the rest of us. It was all bullshit. And when a bitter, betrayed populace searches for someone to blame, right-wing demagogues have little trouble finding scapegoats. People know when they're being lied to, but you won't hear any of this from the corporate media. Only independent journalism—powered and funded by people who believe in building a better world—can deliver truly trustworthy daily news. Our Fall Campaign is underway, and we need your help. To power our newsroom through the rest of the year, we need to raise $125,000 by midnight on October 31. So if you share our vision, please contribute whatever you can to sustain our work. |
Companies that provide "buy now, pay later" loans are increasingly offering their products to Americans struggling to afford utilities and other necessities as costs rise across the US economy, with President Donald Trump's illegal war on Iran pushing up energy prices while wage growth slows.
The New York Times reported Monday that "the lending apps Flex and Zip allow customers to take out loans to pay for their broadband, electricity, health insurance, mobile phone service, mortgage, and water bills," while Affirm "has started providing some tenants loans to extend their monthly rent payment for a few weeks." On the homepage of its website, Affirm is currently promoting its product for school supplies as prices for basic items surge.
Despite Trump's pledge to cut household electricity costs in half and "bring down the prices of all goods," federal data shows electricity prices are up 18% since the start of the president's second White House term. On Monday, the average price for a gallon of gas in the US reached $4.06—the highest ever recorded for mid-August.
Recent polling by Data for Progress shows that 38% of "buy now, pay later" users have turned to the product to cover gasoline costs. Nearly half—46%—have used it for groceries, 42% for medical or dental care, 39% for utility bills, and 22% for childcare.
Last month, the advocacy group Protect Borrowers released a detailed report showing that buy now, pay later lenders are "touting shiny and oftentimes deceptive offers of zero-interest, fee-free installment loans to millions of Americans struggling with the rapidly rising costs of groceries, rent, utility bills, takeout, new clothes, medical care, and more."
"Leading BNPL lenders currently include Affirm, Klarna, Afterpay, PayPal, Synchrony, Splitit, Sezzle, and Zip, but more are popping up by the day, largely funded by private equity firms and venture capitalists looking to cash in on families’ financial desperation," the report states. "BNPL loans are packed to the brim with financing fees, late fees, and other junk fees. Many BNPL loans feature late fees of $7 to $8 per missed payment, up to an aggregate cap of 25% of the purchase price. Additional fees may be charged for financing, if the user does not set a bank account as the default method of payment, reschedules an upcoming payment, or has non-sufficient funds or a bounced payment."
The Times pointed to June Federal Reserve research showing that Americans collectively spent $160 billion through buy now, pay later programs last year, nearly twice what US consumers spent in 2023.
"That’s still a fraction of the more than $3 trillion US shoppers spend annually on consumer credit cards," the Times noted. "But the industry continues to expand by double-digit rates each year."
Jennifer Zhang, a policy analyst at Protect Borrowers, has called on the US Congress to enact "sweeping protections" that "end deceptive pricing, bring down the cost of BNPL debt, ban predatory practices that harm consumers, and empower Americans to enforce their rights under the law."
"BNPL loans are expensive and risky, and often worsen financial outcomes for borrowers who come to rely on them to make ends meet. However, millions of Americans are being driven into these debt products just as they’re trying to get by. Prices are soaring and show no signs of coming down anytime soon," Zhang wrote. "Americans need help."