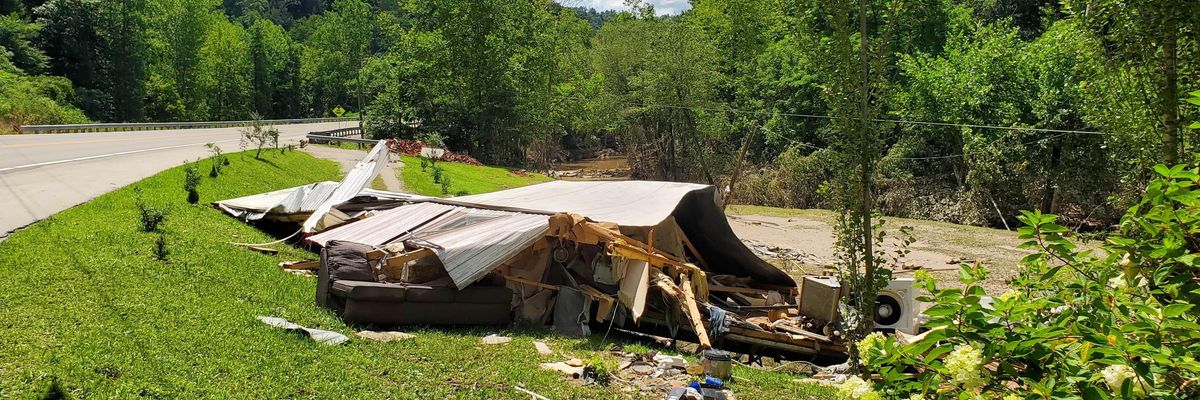
Photo taken on July 30, 2022 shows a house destroyed by heavy rain-caused flooding in Central Appalachia in Kentucky, the United States. The death toll from the heavy rain-caused flooding hitting eastern Kentucky rose to at least 25, including four children from one family, Kentucky Governor Andy Beshear confirmed Saturday. (Photo: Wang Changzheng/Xinhua via Getty Images)
What Insurance Tells Us About Our (In)Capacity for Climate Resilience
In a western country, because of climate change impacts and escalating costs of living, property insurance has become unaffordable for most, or no longer available.
Insurance is a key safety net of western modern life, and many take the insurance of property for granted. House and contents insurance, it is envisaged, will be there if disaster strikes. However, a lack of meaningful action to mitigate climate change is putting this sense of security at risk. For households, there is growing uncertainty about what the future may hold. There are examples, worldwide, of insurers withdrawing from certain markets and households being less and less likely to be able to access or afford property insurance.
If insurance is going to help ease difficulties and vulnerabilities going forward, then it urgently needs to be rethought. Key to this is the idea of socialised insurance based on solidaristic notions of shared responsibility.
Of all the businesses and groups affected by climate change, the insurance sector must be on the ball about climate change impacts and risks. Surely? Their survival depends knowing what's coming and maintaining a customer base, so surely, they have a firm handle on what's going on and what to expect? But pinning down what insurers know is tricky, if not impossible. The data they collect gives them their commercial edge, and they don't often see sharing it as in their interests.
In this article, we unpack some of what we do know. In short, what insurance tells us about society's (in)capacity for climate resilience, is complex. It includes many apparent contradictions. Insurance is inherently solidaristic in that it spreads risk; but it also compounds existing inequities. An affluent customer base is essential for insurance sales; but we are witnessing the erosion of this affluence, and associated privilege, as climate-ecological impacts bear down on us. Some insurers are experimenting with new modes of insurance for this new climate reality, but are stymied by limited elasticity in governmental responses.
Because insurance of property varies between countries and regions, the observations we make here are generalised and relate to broad patterns and trends, not specifics. They are based, in part, on the insights of 24 social scientists that are contained with a new open access book, "Climate, Society, and Elemental Insurance: Capacities and limitations." To distil these insights, and draw out key dynamics, a hypothetical scenario is useful.
The hypothetical: In a western country, because of climate change impacts and escalating costs of living, property insurance has become unaffordable for most, or no longer available. This poses a problem for the national government, which is expected to be the insurer of last resort, both financially and in maintaining social cohesion and thus, national security. Insurers have been experimenting for some time with index insurance in poorer regions, such as the Caribbean, and offer this western country's government a package that guarantees substantial insurance payouts following large-scale disasters or specified extreme weather events. These payouts are designed to enable continuance of the nation state and, as this is also conditional on the distribution of food and essential supplies to the population, some form of social stability.
This is what happens on-the-ground following a cyclonic storm that rips through two of the largest population centres, including the capital city, and surrounding rural areas. With the insurance payout in hand, the first response of the government is to secure its seat of power because, logically, without this centralised organising capacity, collective recovery cannot occur (we will leave aside, albeit naively, the impetus of power to secure itself for its own sake and not for the sake of others). Resources then begin to flow to affected populations, prioritised around shoring up the centralised organising capacity of the nation state. In other words, as major transport systems are re-established and then supplies are distributed, those with power and responsibility receive priority.
Then comes everyone else, but the obstacles to equitable distribution are huge. Scattered, informal settlements have sprung up across the region following a decade of rolling natural disasters and a loss of access to insurance. Even within the cities, areas of disadvantage and socio-economic hardship have become characterised by reduced living conditions and poor building standards (think Grenfell Tower). The impact of the cyclone has rendered entire suburbs inaccessible, unsafe, and inhospitable. Those best equipped to self-organise are those who retain some level of social status and security, and it is those same people who reap the most benefits from distribution of supplies purchased through insurance payout. Some of this money is also used to police those less well off, again, in the name of social cohesion, but this acts to further isolate an already battered and bruised portion of the population, and the gap between rich and poor widens. Again.
Some may see this scenario as far-fetched, yet it is based on real-life events that are unfolding in real-time, some of which are covered in more detail in our free book, "Climate, Society and Elemental Insurance." One of the reasons why more attention is being paid to insurance affordability and availability is that, gradually, the illusion of security sustained by western privilege and wealth is shattering. There is no longer a sense of certainty and safety, and insurance is being leaned on in the hope that it will keep doing what many have assumed it has always done--acted as a reassuring safety net through thick and thin. What this assumption fails to recognise is that insurance has never been a sure-fire backstop for all. It has always been a fragile privilege that has sustained countries and populations, such as one depicted in this scenario, and an equally fragile democracy.
If insurance is going to help ease difficulties and vulnerabilities going forward, then it urgently needs to be rethought. Key to this is the idea of socialised insurance based on solidaristic notions of shared responsibility. In other words, there is a need to create resilience frameworks based not on individualised ideas of risk and responsibility, but on a collective understanding of the public good. Social cohesion can see us through many things that an individual insurance policy cannot.
We are at a crossroads
This country and this world are at a monumental crossroads. In a few short weeks, US voters will have an opportunity to beat back the forces of fascism and confront the billionaires who are rigging the economy, our media system, and our democracy, making it increasingly impossible for ordinary people to get by. We’re not just talking about the election. We’re talking about what must be done once these fascist elements are vanquished from power. We need a bolder set of solutions than what either major party has so far been willing to offer and a working-class movement ready to fight like hell for it. Trump didn't emerge from nowhere. The conditions that fueled MAGA authoritarianism were created by decades of radical neoliberal economic policies and a corrupt political system dominated by corporate interests. They slashed taxes on the super-rich, promising that the benefits would trickle down. They said giveaways to the corporate titans would make life more affordable for the rest of us. It was all bullshit. And when a bitter, betrayed populace searches for someone to blame, right-wing demagogues have little trouble finding scapegoats. People know when they're being lied to, but you won't hear any of this from the corporate media. Only independent journalism—powered and funded by people who believe in building a better world—can deliver truly trustworthy daily news. Our Fall Campaign is underway, and we need your help. To power our newsroom through the rest of the year, we need to raise $125,000 by midnight on October 31. So if you share our vision, please contribute whatever you can to sustain our work. |
Insurance is a key safety net of western modern life, and many take the insurance of property for granted. House and contents insurance, it is envisaged, will be there if disaster strikes. However, a lack of meaningful action to mitigate climate change is putting this sense of security at risk. For households, there is growing uncertainty about what the future may hold. There are examples, worldwide, of insurers withdrawing from certain markets and households being less and less likely to be able to access or afford property insurance.
If insurance is going to help ease difficulties and vulnerabilities going forward, then it urgently needs to be rethought. Key to this is the idea of socialised insurance based on solidaristic notions of shared responsibility.
Of all the businesses and groups affected by climate change, the insurance sector must be on the ball about climate change impacts and risks. Surely? Their survival depends knowing what's coming and maintaining a customer base, so surely, they have a firm handle on what's going on and what to expect? But pinning down what insurers know is tricky, if not impossible. The data they collect gives them their commercial edge, and they don't often see sharing it as in their interests.
In this article, we unpack some of what we do know. In short, what insurance tells us about society's (in)capacity for climate resilience, is complex. It includes many apparent contradictions. Insurance is inherently solidaristic in that it spreads risk; but it also compounds existing inequities. An affluent customer base is essential for insurance sales; but we are witnessing the erosion of this affluence, and associated privilege, as climate-ecological impacts bear down on us. Some insurers are experimenting with new modes of insurance for this new climate reality, but are stymied by limited elasticity in governmental responses.
Because insurance of property varies between countries and regions, the observations we make here are generalised and relate to broad patterns and trends, not specifics. They are based, in part, on the insights of 24 social scientists that are contained with a new open access book, "Climate, Society, and Elemental Insurance: Capacities and limitations." To distil these insights, and draw out key dynamics, a hypothetical scenario is useful.
The hypothetical: In a western country, because of climate change impacts and escalating costs of living, property insurance has become unaffordable for most, or no longer available. This poses a problem for the national government, which is expected to be the insurer of last resort, both financially and in maintaining social cohesion and thus, national security. Insurers have been experimenting for some time with index insurance in poorer regions, such as the Caribbean, and offer this western country's government a package that guarantees substantial insurance payouts following large-scale disasters or specified extreme weather events. These payouts are designed to enable continuance of the nation state and, as this is also conditional on the distribution of food and essential supplies to the population, some form of social stability.
This is what happens on-the-ground following a cyclonic storm that rips through two of the largest population centres, including the capital city, and surrounding rural areas. With the insurance payout in hand, the first response of the government is to secure its seat of power because, logically, without this centralised organising capacity, collective recovery cannot occur (we will leave aside, albeit naively, the impetus of power to secure itself for its own sake and not for the sake of others). Resources then begin to flow to affected populations, prioritised around shoring up the centralised organising capacity of the nation state. In other words, as major transport systems are re-established and then supplies are distributed, those with power and responsibility receive priority.
Then comes everyone else, but the obstacles to equitable distribution are huge. Scattered, informal settlements have sprung up across the region following a decade of rolling natural disasters and a loss of access to insurance. Even within the cities, areas of disadvantage and socio-economic hardship have become characterised by reduced living conditions and poor building standards (think Grenfell Tower). The impact of the cyclone has rendered entire suburbs inaccessible, unsafe, and inhospitable. Those best equipped to self-organise are those who retain some level of social status and security, and it is those same people who reap the most benefits from distribution of supplies purchased through insurance payout. Some of this money is also used to police those less well off, again, in the name of social cohesion, but this acts to further isolate an already battered and bruised portion of the population, and the gap between rich and poor widens. Again.
Some may see this scenario as far-fetched, yet it is based on real-life events that are unfolding in real-time, some of which are covered in more detail in our free book, "Climate, Society and Elemental Insurance." One of the reasons why more attention is being paid to insurance affordability and availability is that, gradually, the illusion of security sustained by western privilege and wealth is shattering. There is no longer a sense of certainty and safety, and insurance is being leaned on in the hope that it will keep doing what many have assumed it has always done--acted as a reassuring safety net through thick and thin. What this assumption fails to recognise is that insurance has never been a sure-fire backstop for all. It has always been a fragile privilege that has sustained countries and populations, such as one depicted in this scenario, and an equally fragile democracy.
If insurance is going to help ease difficulties and vulnerabilities going forward, then it urgently needs to be rethought. Key to this is the idea of socialised insurance based on solidaristic notions of shared responsibility. In other words, there is a need to create resilience frameworks based not on individualised ideas of risk and responsibility, but on a collective understanding of the public good. Social cohesion can see us through many things that an individual insurance policy cannot.