SUBSCRIBE TO OUR FREE NEWSLETTER
Daily news & progressive opinion—funded by the people, not the corporations—delivered straight to your inbox.
5
#000000
#FFFFFF
To donate by check, phone, or other method, see our More Ways to Give page.
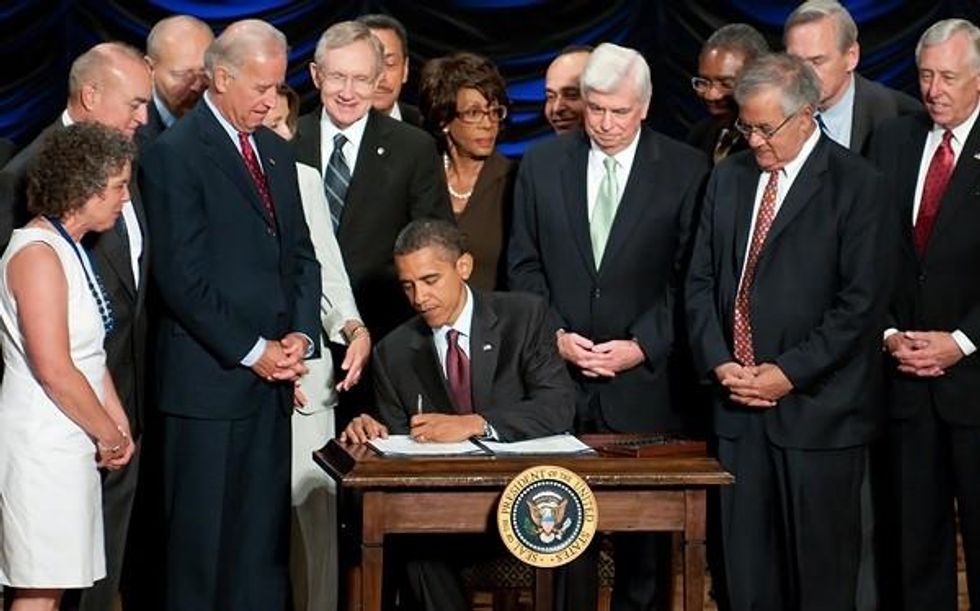
Two years ago, when he signed the Dodd-Frank Wall Street Reform and Consumer Protection Act, President Barack Obama bragged that he'd dealt a crushing blow to the extravagant financial corruption that had caused the global economic crash in 2008. "These reforms represent the strongest consumer financial protections in history," the president told an adoring crowd in downtown D.C. on July 21st, 2010. "In history."
This was supposed to be the big one. At 2,300 pages, the new law ostensibly rewrote the rules for Wall Street. It was going to put an end to predatory lending in the mortgage markets, crack down on hidden fees and penalties in credit contracts, and create a powerful new Consumer Financial Protection Bureau to safeguard ordinary consumers. Big banks would be banned from gambling with taxpayer money, and a new set of rules would limit speculators from making the kind of crazy-ass bets that cause wild spikes in the price of food and energy. There would be no more AIGs, and the world would never again face a financial apocalypse when a bank like Lehman Brothers went bankrupt.
Most importantly, even if any of that fiendish crap ever did happen again, Dodd-Frank guaranteed we wouldn't be expected to pay for it. "The American people will never again be asked to foot the bill for Wall Street's mistakes," Obama promised. "There will be no more taxpayer-funded bailouts. Period."
Two years later, Dodd-Frank is groaning on its deathbed. The giant reform bill turned out to be like the fish reeled in by Hemingway's Old Man - no sooner caught than set upon by sharks that strip it to nothing long before it ever reaches the shore. In a furious below-the-radar effort at gutting the law - roundly despised by Washington's Wall Street paymasters - a troop of water-carrying Eric Cantor Republicans are speeding nine separate bills through the House, all designed to roll back the few genuinely toothy portions left in Dodd-Frank. With the Quislingian covert assistance of Democrats, both in Congress and in the White House, those bills could pass through the House and the Senate with little or no debate, with simple floor votes - by a process usually reserved for things like the renaming of post offices or a nonbinding resolution celebrating Amelia Earhart's birthday.
The fate of Dodd-Frank over the past two years is an object lesson in the government's inability to institute even the simplest and most obvious reforms, especially if those reforms happen to clash with powerful financial interests. From the moment it was signed into law, lobbyists and lawyers have fought regulators over every line in the rulemaking process. Congressmen and presidents may be able to get a law passed once in a while - but they can no longer make sure it stays passed. You win the modern financial-regulation game by filing the most motions, attending the most hearings, giving the most money to the most politicians and, above all, by keeping at it, day after day, year after fiscal year, until stealing is legal again. "It's like a scorched-earth policy," says Michael Greenberger, a former regulator who was heavily involved with the drafting of Dodd-Frank. "It requires constant combat. And it never, ever ends."
That the banks have just about succeeded in strangling Dodd-Frank is probably not news to most Americans - it's how they succeeded that's the scary part. The banks followed a five-point strategy that offers a dependable blueprint for defeating any regulation - and for guaranteeing that when it comes to the economy, might will always equal right.
STEP 1: STRANGLE IT IN THE WOMB
The first advantage the banks had lay in the fact that for all Obama's bluster, Dodd-Frank was never such a badass law to begin with. In fact, Obama's initial response to the devastating financial events of 2008 represented a major departure from the historical precedent his own party had set during the 1930s, when President Franklin D. Roosevelt launched an audacious rewrite of the rules governing the American economy following the Great Crash of 1929.
Upon entering office, FDR was in exactly the same position Obama found himself in after his inauguration in 2009. Then, as now, the American economy was in tatters after the bursting of a massive financial bubble, brought on when speculators borrowed huge sums and gambled on unregistered securities in largely unregulated exchanges. This mania for instant riches led to an explosion of Wall Street fraud and manipulation, creating a mountain of illusory growth divorced from the real-world economy: Of the $50 billion in securities sold in America in the 1920s, half turned out to be worthless.
Roosevelt's response to all of this was to pass a number of sweeping new laws that focused on a single theme: protecting consumers by forcing the business of Wall Street into the light. The Securities Act of 1933 required all publicly traded companies to register themselves and offer prospectuses to investors; the Securities Exchange Act of 1934 forced publicly traded companies to make regular financial disclosures; and the Commodity Exchange Act of 1936 required all commodities and futures to be traded on organized exchanges. FDR also created the FDIC to protect bank depositors (through an insurance fund paid for by the banks themselves) and passed the Glass-Steagall Act to separate insurance companies, investment banks and commercial banks. Post-New Deal, if you put money in a bank, you knew it was safe, and if you bought stock, you knew what you were buying.
This reform strategy worked for more than half a century - and it offered Obama a clear outline of how to respond to the crash he faced. What made 2008 possible was that Wall Street had moved its speculative frenzy away from the regulated exchange system created by FDR, and into darker, less-regulated markets that had coalesced around brand-new financial innovations like credit default swaps and collateralized-debt obligations. It wasn't that the old system had broken down; Wall Street had just moved the playground.
All Obama needed to do to rescue the economy and protect consumers was to make sure that the new playground had some rules. That meant moving swaps and other derivatives onto open exchanges, making sure that federally insured banks that dabbled in those dangerous markets retained more capital, and coming up with some kind of plan to prevent the next AIG or Lehman Brothers disaster - i.e., a plan for unwinding failing companies that wouldn't require federal bailouts.
Two years ago, when he signed the Dodd-Frank Wall Street Reform and Consumer Protection Act, President Barack Obama bragged that he'd dealt a crushing blow to the extravagant financial corruption that had caused the global economic crash in 2008. "These reforms represent the strongest consumer financial protections in history," the president told an adoring crowd in downtown D.C. on July 21st, 2010. "In history."
This was supposed to be the big one. At 2,300 pages, the new law ostensibly rewrote the rules for Wall Street. It was going to put an end to predatory lending in the mortgage markets, crack down on hidden fees and penalties in credit contracts, and create a powerful new Consumer Financial Protection Bureau to safeguard ordinary consumers. Big banks would be banned from gambling with taxpayer money, and a new set of rules would limit speculators from making the kind of crazy-ass bets that cause wild spikes in the price of food and energy. There would be no more AIGs, and the world would never again face a financial apocalypse when a bank like Lehman Brothers went bankrupt.
Most importantly, even if any of that fiendish crap ever did happen again, Dodd-Frank guaranteed we wouldn't be expected to pay for it. "The American people will never again be asked to foot the bill for Wall Street's mistakes," Obama promised. "There will be no more taxpayer-funded bailouts. Period."
Two years later, Dodd-Frank is groaning on its deathbed. The giant reform bill turned out to be like the fish reeled in by Hemingway's Old Man - no sooner caught than set upon by sharks that strip it to nothing long before it ever reaches the shore. In a furious below-the-radar effort at gutting the law - roundly despised by Washington's Wall Street paymasters - a troop of water-carrying Eric Cantor Republicans are speeding nine separate bills through the House, all designed to roll back the few genuinely toothy portions left in Dodd-Frank. With the Quislingian covert assistance of Democrats, both in Congress and in the White House, those bills could pass through the House and the Senate with little or no debate, with simple floor votes - by a process usually reserved for things like the renaming of post offices or a nonbinding resolution celebrating Amelia Earhart's birthday.
The fate of Dodd-Frank over the past two years is an object lesson in the government's inability to institute even the simplest and most obvious reforms, especially if those reforms happen to clash with powerful financial interests. From the moment it was signed into law, lobbyists and lawyers have fought regulators over every line in the rulemaking process. Congressmen and presidents may be able to get a law passed once in a while - but they can no longer make sure it stays passed. You win the modern financial-regulation game by filing the most motions, attending the most hearings, giving the most money to the most politicians and, above all, by keeping at it, day after day, year after fiscal year, until stealing is legal again. "It's like a scorched-earth policy," says Michael Greenberger, a former regulator who was heavily involved with the drafting of Dodd-Frank. "It requires constant combat. And it never, ever ends."
That the banks have just about succeeded in strangling Dodd-Frank is probably not news to most Americans - it's how they succeeded that's the scary part. The banks followed a five-point strategy that offers a dependable blueprint for defeating any regulation - and for guaranteeing that when it comes to the economy, might will always equal right.
STEP 1: STRANGLE IT IN THE WOMB
The first advantage the banks had lay in the fact that for all Obama's bluster, Dodd-Frank was never such a badass law to begin with. In fact, Obama's initial response to the devastating financial events of 2008 represented a major departure from the historical precedent his own party had set during the 1930s, when President Franklin D. Roosevelt launched an audacious rewrite of the rules governing the American economy following the Great Crash of 1929.
Upon entering office, FDR was in exactly the same position Obama found himself in after his inauguration in 2009. Then, as now, the American economy was in tatters after the bursting of a massive financial bubble, brought on when speculators borrowed huge sums and gambled on unregistered securities in largely unregulated exchanges. This mania for instant riches led to an explosion of Wall Street fraud and manipulation, creating a mountain of illusory growth divorced from the real-world economy: Of the $50 billion in securities sold in America in the 1920s, half turned out to be worthless.
Roosevelt's response to all of this was to pass a number of sweeping new laws that focused on a single theme: protecting consumers by forcing the business of Wall Street into the light. The Securities Act of 1933 required all publicly traded companies to register themselves and offer prospectuses to investors; the Securities Exchange Act of 1934 forced publicly traded companies to make regular financial disclosures; and the Commodity Exchange Act of 1936 required all commodities and futures to be traded on organized exchanges. FDR also created the FDIC to protect bank depositors (through an insurance fund paid for by the banks themselves) and passed the Glass-Steagall Act to separate insurance companies, investment banks and commercial banks. Post-New Deal, if you put money in a bank, you knew it was safe, and if you bought stock, you knew what you were buying.
This reform strategy worked for more than half a century - and it offered Obama a clear outline of how to respond to the crash he faced. What made 2008 possible was that Wall Street had moved its speculative frenzy away from the regulated exchange system created by FDR, and into darker, less-regulated markets that had coalesced around brand-new financial innovations like credit default swaps and collateralized-debt obligations. It wasn't that the old system had broken down; Wall Street had just moved the playground.
All Obama needed to do to rescue the economy and protect consumers was to make sure that the new playground had some rules. That meant moving swaps and other derivatives onto open exchanges, making sure that federally insured banks that dabbled in those dangerous markets retained more capital, and coming up with some kind of plan to prevent the next AIG or Lehman Brothers disaster - i.e., a plan for unwinding failing companies that wouldn't require federal bailouts.
Two years ago, when he signed the Dodd-Frank Wall Street Reform and Consumer Protection Act, President Barack Obama bragged that he'd dealt a crushing blow to the extravagant financial corruption that had caused the global economic crash in 2008. "These reforms represent the strongest consumer financial protections in history," the president told an adoring crowd in downtown D.C. on July 21st, 2010. "In history."
This was supposed to be the big one. At 2,300 pages, the new law ostensibly rewrote the rules for Wall Street. It was going to put an end to predatory lending in the mortgage markets, crack down on hidden fees and penalties in credit contracts, and create a powerful new Consumer Financial Protection Bureau to safeguard ordinary consumers. Big banks would be banned from gambling with taxpayer money, and a new set of rules would limit speculators from making the kind of crazy-ass bets that cause wild spikes in the price of food and energy. There would be no more AIGs, and the world would never again face a financial apocalypse when a bank like Lehman Brothers went bankrupt.
Most importantly, even if any of that fiendish crap ever did happen again, Dodd-Frank guaranteed we wouldn't be expected to pay for it. "The American people will never again be asked to foot the bill for Wall Street's mistakes," Obama promised. "There will be no more taxpayer-funded bailouts. Period."
Two years later, Dodd-Frank is groaning on its deathbed. The giant reform bill turned out to be like the fish reeled in by Hemingway's Old Man - no sooner caught than set upon by sharks that strip it to nothing long before it ever reaches the shore. In a furious below-the-radar effort at gutting the law - roundly despised by Washington's Wall Street paymasters - a troop of water-carrying Eric Cantor Republicans are speeding nine separate bills through the House, all designed to roll back the few genuinely toothy portions left in Dodd-Frank. With the Quislingian covert assistance of Democrats, both in Congress and in the White House, those bills could pass through the House and the Senate with little or no debate, with simple floor votes - by a process usually reserved for things like the renaming of post offices or a nonbinding resolution celebrating Amelia Earhart's birthday.
The fate of Dodd-Frank over the past two years is an object lesson in the government's inability to institute even the simplest and most obvious reforms, especially if those reforms happen to clash with powerful financial interests. From the moment it was signed into law, lobbyists and lawyers have fought regulators over every line in the rulemaking process. Congressmen and presidents may be able to get a law passed once in a while - but they can no longer make sure it stays passed. You win the modern financial-regulation game by filing the most motions, attending the most hearings, giving the most money to the most politicians and, above all, by keeping at it, day after day, year after fiscal year, until stealing is legal again. "It's like a scorched-earth policy," says Michael Greenberger, a former regulator who was heavily involved with the drafting of Dodd-Frank. "It requires constant combat. And it never, ever ends."
That the banks have just about succeeded in strangling Dodd-Frank is probably not news to most Americans - it's how they succeeded that's the scary part. The banks followed a five-point strategy that offers a dependable blueprint for defeating any regulation - and for guaranteeing that when it comes to the economy, might will always equal right.
STEP 1: STRANGLE IT IN THE WOMB
The first advantage the banks had lay in the fact that for all Obama's bluster, Dodd-Frank was never such a badass law to begin with. In fact, Obama's initial response to the devastating financial events of 2008 represented a major departure from the historical precedent his own party had set during the 1930s, when President Franklin D. Roosevelt launched an audacious rewrite of the rules governing the American economy following the Great Crash of 1929.
Upon entering office, FDR was in exactly the same position Obama found himself in after his inauguration in 2009. Then, as now, the American economy was in tatters after the bursting of a massive financial bubble, brought on when speculators borrowed huge sums and gambled on unregistered securities in largely unregulated exchanges. This mania for instant riches led to an explosion of Wall Street fraud and manipulation, creating a mountain of illusory growth divorced from the real-world economy: Of the $50 billion in securities sold in America in the 1920s, half turned out to be worthless.
Roosevelt's response to all of this was to pass a number of sweeping new laws that focused on a single theme: protecting consumers by forcing the business of Wall Street into the light. The Securities Act of 1933 required all publicly traded companies to register themselves and offer prospectuses to investors; the Securities Exchange Act of 1934 forced publicly traded companies to make regular financial disclosures; and the Commodity Exchange Act of 1936 required all commodities and futures to be traded on organized exchanges. FDR also created the FDIC to protect bank depositors (through an insurance fund paid for by the banks themselves) and passed the Glass-Steagall Act to separate insurance companies, investment banks and commercial banks. Post-New Deal, if you put money in a bank, you knew it was safe, and if you bought stock, you knew what you were buying.
This reform strategy worked for more than half a century - and it offered Obama a clear outline of how to respond to the crash he faced. What made 2008 possible was that Wall Street had moved its speculative frenzy away from the regulated exchange system created by FDR, and into darker, less-regulated markets that had coalesced around brand-new financial innovations like credit default swaps and collateralized-debt obligations. It wasn't that the old system had broken down; Wall Street had just moved the playground.
All Obama needed to do to rescue the economy and protect consumers was to make sure that the new playground had some rules. That meant moving swaps and other derivatives onto open exchanges, making sure that federally insured banks that dabbled in those dangerous markets retained more capital, and coming up with some kind of plan to prevent the next AIG or Lehman Brothers disaster - i.e., a plan for unwinding failing companies that wouldn't require federal bailouts.