The Trump administration on Wednesday announced new proposed rules for the Affordable Care Act (ACA), or Obamacare--and while they "don't amount to sweeping changes," the tweaks are predicted to raise costs for consumers while benefiting insurance companies and further undermining the critical healthcare law.
A proposal from the Health and Human Services Department (HHS) "would change the rules for insurers that sell coverage through the Affordable Care Act's exchanges or directly to individuals," as the Huffington Post explained. Among other things, HHS seeks to "dramatically" shorten the 2018 open enrollment period and tighten enrollment eligibility "to deter people from waiting to sign up for insurance until they get sick or otherwise need health services," CNBC reported.
The Washington Post added that "the changes would eliminate federal reviews of whether health plans in the ACA marketplaces have enough doctors and other providers of care, delegating the task to states."
Additionally, the proposal "would water down the standards for what coverage insurers provide," according to HuffPo.
Business Insider explains: "Essentially, the ACA established minimum standards for coverage (here's a full breakdown from CMS) in order to be certified on the bronze, silver, and gold plan levels. The new rule would allow insurers to cover slightly fewer areas of health and still be at a certain metal level."
The nonpartisan Center for Budget and Policy Priorities (CBPP) offered further analysis:
The proposed rule allows individual-market insurers to offer plans with higher deductibles and out-of-pocket costs, but lower premiums, than they're now allowed to offer. That's because it allows plans with lower "actuarial value." Actuarial value is the share of a typical consumer's medical costs that the plan covers, as opposed to what the consumer pays directly through deductibles, copays, and coinsurance. For example, in a silver plan with an actuarial value of 70 percent, the plan picks up 70 percent of a typical consumer's costs for covered benefits, while the consumer would expect to pay 30 percent of costs out of pocket.
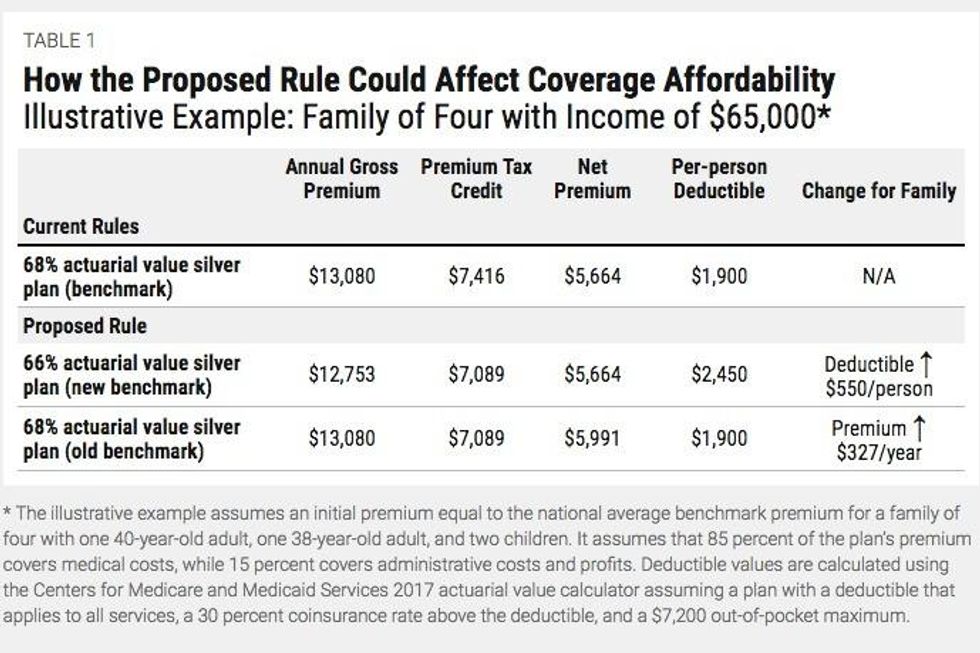
To help consumers understand and compare plans, marketplace health plans are tiered by actuarial value: 60 percent (bronze), 70 percent (silver), 80 percent (gold), and 90 percent (platinum). Current rules allow insurers to still meet their actuarial value standards if they deviate by a "de minimis" 2 percentage points from these standard values. The proposed rule would allow plans with actuarial values as much as 4 percentage points below the standard values. That would allow bronze plans with higher deductibles than any current marketplace plans. It also would allow silver plans with actuarial values as low as 66 percent. By allowing for such silver plans, the rule would reduce the size of premium tax credits for millions of families.
This CBPP chart lays out the potential impact for a family of four with $65,000 of income:
In essence, Wednesday's HHS announcement begins to outline what one commentator referred to as "Trumpcare," the hallmarks of which will be "lower enrollment [and] higher costs for consumers."
Center for American Progress vice president for health policy Topher Spiro laid out his full argument in a series of tweets:
Ron Pollack, executive director of the advocacy group Families USA, told NBC News that depressing enrollment is exactly what President Donald Trump and the GOP are after.
"The Trump administration is deliberately trying to sabotage the Affordable Care Act, especially by making it much more difficult for people to enroll in coverage. By making it harder to enroll, they are creating their own 'death spiral' that would deter young adults from gaining coverage, thereby driving up costs for everyone," Pollack said, referencing a remark made Wednesday by Aetna CEO Mark Bertolini.
What's more, Families USA wrote in a blog post: "In an effort to suppress meaningful comments from consumer groups and other stakeholders, the administration has provided only a 21-day comment period, an unprecedented departure from standard comment periods for rules of this significance."
The group is encouraging its members and concerned constituents to take action by submitting comments during the public comment period (through March 7), and amplifying the message that "this rule will harm consumers" and "will not stabilize the market as intended."
In a separate move that experts also said could undermine the ACA, the Internal Revenue Service (IRS) said Wednesday it would "ease up on the [ACA's] requirement that everyone have healthcare or pay a penalty," as Yahoo! Finance reported.
Andy Slavitt, who was the top official for the Centers for Medicare and Medicaid Services under former President Barack Obama, noted online that "non-enforcement pushes premiums higher."
The Libertarian publication Reason described the IRS' move as a "major blow" to Obamacare, writing that "the change may signal that the Trump administration intends to water down enforcement of the health law's most controversial requirement, even if those steps are seemingly small. The Trump administration may not be tearing Obamacare down entirely, but it appears to be taking steps to weaken the law, however subtly, one line at a time."
And with some suggesting that Wednesday's developments may be "a preview of GOP Obamacare replacements," it's time (again) to listen to those who see a better solution.
"The only replacement plan that a majority of Americans and an overwhelming majority of those who identify themselves as Democrats support is the Medicare-for-all model," wrote healthcare advocate and Common Dreams contributor Donna Smith on Wednesday. "No games. No political posturing. No higher profits for the already profitable insurance giants. Sick people need healthcare. The nation needs sound healthcare policy. Let's get on with it."
The Trump administration on Wednesday announced new proposed rules for the Affordable Care Act (ACA), or Obamacare--and while they "don't amount to sweeping changes," the tweaks are predicted to raise costs for consumers while benefiting insurance companies and further undermining the critical healthcare law.
A proposal from the Health and Human Services Department (HHS) "would change the rules for insurers that sell coverage through the Affordable Care Act's exchanges or directly to individuals," as the Huffington Post explained. Among other things, HHS seeks to "dramatically" shorten the 2018 open enrollment period and tighten enrollment eligibility "to deter people from waiting to sign up for insurance until they get sick or otherwise need health services," CNBC reported.
The Washington Post added that "the changes would eliminate federal reviews of whether health plans in the ACA marketplaces have enough doctors and other providers of care, delegating the task to states."
Additionally, the proposal "would water down the standards for what coverage insurers provide," according to HuffPo.
Business Insider explains: "Essentially, the ACA established minimum standards for coverage (here's a full breakdown from CMS) in order to be certified on the bronze, silver, and gold plan levels. The new rule would allow insurers to cover slightly fewer areas of health and still be at a certain metal level."
The nonpartisan Center for Budget and Policy Priorities (CBPP) offered further analysis:
The proposed rule allows individual-market insurers to offer plans with higher deductibles and out-of-pocket costs, but lower premiums, than they're now allowed to offer. That's because it allows plans with lower "actuarial value." Actuarial value is the share of a typical consumer's medical costs that the plan covers, as opposed to what the consumer pays directly through deductibles, copays, and coinsurance. For example, in a silver plan with an actuarial value of 70 percent, the plan picks up 70 percent of a typical consumer's costs for covered benefits, while the consumer would expect to pay 30 percent of costs out of pocket.
To help consumers understand and compare plans, marketplace health plans are tiered by actuarial value: 60 percent (bronze), 70 percent (silver), 80 percent (gold), and 90 percent (platinum). Current rules allow insurers to still meet their actuarial value standards if they deviate by a "de minimis" 2 percentage points from these standard values. The proposed rule would allow plans with actuarial values as much as 4 percentage points below the standard values. That would allow bronze plans with higher deductibles than any current marketplace plans. It also would allow silver plans with actuarial values as low as 66 percent. By allowing for such silver plans, the rule would reduce the size of premium tax credits for millions of families.
This CBPP chart lays out the potential impact for a family of four with $65,000 of income:
In essence, Wednesday's HHS announcement begins to outline what one commentator referred to as "Trumpcare," the hallmarks of which will be "lower enrollment [and] higher costs for consumers."
Center for American Progress vice president for health policy Topher Spiro laid out his full argument in a series of tweets:
Ron Pollack, executive director of the advocacy group Families USA, told NBC News that depressing enrollment is exactly what President Donald Trump and the GOP are after.
"The Trump administration is deliberately trying to sabotage the Affordable Care Act, especially by making it much more difficult for people to enroll in coverage. By making it harder to enroll, they are creating their own 'death spiral' that would deter young adults from gaining coverage, thereby driving up costs for everyone," Pollack said, referencing a remark made Wednesday by Aetna CEO Mark Bertolini.
What's more, Families USA wrote in a blog post: "In an effort to suppress meaningful comments from consumer groups and other stakeholders, the administration has provided only a 21-day comment period, an unprecedented departure from standard comment periods for rules of this significance."
The group is encouraging its members and concerned constituents to take action by submitting comments during the public comment period (through March 7), and amplifying the message that "this rule will harm consumers" and "will not stabilize the market as intended."
In a separate move that experts also said could undermine the ACA, the Internal Revenue Service (IRS) said Wednesday it would "ease up on the [ACA's] requirement that everyone have healthcare or pay a penalty," as Yahoo! Finance reported.
Andy Slavitt, who was the top official for the Centers for Medicare and Medicaid Services under former President Barack Obama, noted online that "non-enforcement pushes premiums higher."
The Libertarian publication Reason described the IRS' move as a "major blow" to Obamacare, writing that "the change may signal that the Trump administration intends to water down enforcement of the health law's most controversial requirement, even if those steps are seemingly small. The Trump administration may not be tearing Obamacare down entirely, but it appears to be taking steps to weaken the law, however subtly, one line at a time."
And with some suggesting that Wednesday's developments may be "a preview of GOP Obamacare replacements," it's time (again) to listen to those who see a better solution.
"The only replacement plan that a majority of Americans and an overwhelming majority of those who identify themselves as Democrats support is the Medicare-for-all model," wrote healthcare advocate and Common Dreams contributor Donna Smith on Wednesday. "No games. No political posturing. No higher profits for the already profitable insurance giants. Sick people need healthcare. The nation needs sound healthcare policy. Let's get on with it."