SUBSCRIBE TO OUR FREE NEWSLETTER
Daily news & progressive opinion—funded by the people, not the corporations—delivered straight to your inbox.
5
#000000
#FFFFFF
To donate by check, phone, or other method, see our More Ways to Give page.
Daily news & progressive opinion—funded by the people, not the corporations—delivered straight to your inbox.
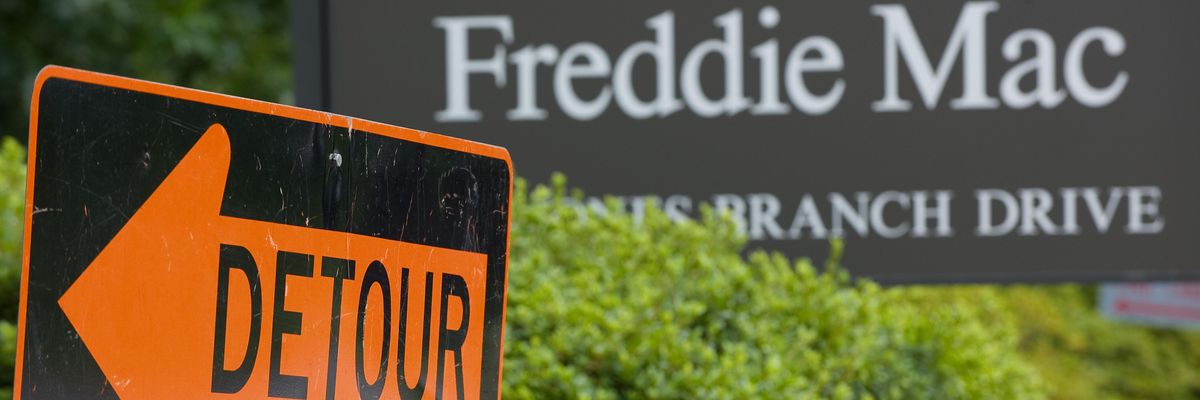
A "detour" sign is posted at the main entrance to the Freddie Mac headquarters on July 14, 2008 in McLean, Virginia.
The basic story here is that in order to give donors in the financial industry still more money, Trump is planning to privatize a perfectly well-functioning public system for securitizing mortgages.
In Washington no bad idea stays dead long. Therefore it should not be surprising that U.S. President Donald Trump is planning to move forward with plans to privatize Fannie Mae and Freddie Mac, the mortgage giants that have been in government conservatorship for almost two decades.
As with many of the moves undertaken by Trump, it is not clear what problem this is meant to solve. For the period they have been in conservatorship, Fannie and Freddie have been securitizing mortgages at a low cost and have not faced any substantial management problems.
There is of course one problem that privatizing Fannie and Freddie would solve. This is yet one more way that the financial industry can run up some profits and high pay for top executives at the expense of the rest of us.
The Congressional Budget Office calculated that having private institutions, rather than Fannie and Freddie in their current form, would add roughly 20 basis points, 0.2% to the cost of securitizing mortgages. With around $1 trillion in mortgages being securitized each year, that comes to $2 billion annually. That is not huge in the context of the federal budget (0.03%), but it is four times the annual appropriation for the Corporation for Public Broadcasting that got Trump so upset.
Trump is giving a green light to his finance buddies to find every more creative ways to rip off businesses and ordinary people.
And in the case of privatizing Fannie and Freddie, we literally get nothing for it except a less efficient mechanism for securitizing mortgages. This is similar to the plans for privatizing Social Security. We have an extremely efficient public system, but many people in the Trump administration see the opportunity to make trillions of dollars in fees by turning it into a private system.
As with a privatized Social Security system, we would also be exposing ourselves to needless risk by privatizing Fannie and Freddie. The basic problem is that we would be allowing a private corporation to operate with a government guarantee against losses. This guarantee gives a private securitizer an enormous incentive to securitize bad mortgages in order to increase volume and make more profits. That was the story of the housing bubble and the subsequent collapse and financial crisis in 2008-09.
If a private securitizer is carefully regulated, it can limit the risk of reckless lending. But does anyone believe that the Trump administration is going to have careful regulation of the financial industry?
The basic story here is that in order to give donors in the financial industry still more money, Trump is planning to privatize a perfectly well-functioning public system for securitizing mortgages. This move will almost certainly increase the cost of mortgages for homebuyers, the only question is by how much. And it raises the risk for future financial crises and government bailouts.
Making the financial sector less efficient in order to hand money to contributors is very much front and center in the Trump administration. This is the same story with his decision to promote crypto currency, which is making Trump and his friends tens of billions of dollars; as opposed to letting the Federal Reserve Board issue a digital currency, which would save us tens of billions in bank and credit card fees.
The evisceration of the Consumer Financial Protection Bureau follows the same pattern. Trump is giving a green light to his finance buddies to find every more creative ways to rip off businesses and ordinary people.
That’s how we should understand the drive to privatize Fannie and Freddie. How could anyone oppose it?
This country and this world are at a monumental crossroads. US voters have an opportunity to beat back the forces of fascism and confront the billionaires who are rigging the economy, our media system, and our democracy, making it increasingly impossible for ordinary people to get by. We’re not just talking about the election. We’re talking about what must be done once these fascist elements are vanquished from power. We need a bolder set of solutions than what either major party has so far been willing to offer and a working-class movement ready to fight like hell for it. Trump didn't emerge from nowhere. The conditions that fueled MAGA authoritarianism were created by decades of radical neoliberal economic policies and a corrupt political system dominated by corporate interests. They slashed taxes on the super-rich, promising that the benefits would trickle down. They said giveaways to the corporate titans would make life more affordable for the rest of us. It was all bullshit. And when a bitter, betrayed populace searches for someone to blame, right-wing demagogues have little trouble finding scapegoats. People know when they're being lied to, but you won't hear any of this from the corporate media. Only independent journalism—powered and funded by people who believe in building a better world—can deliver truly trustworthy daily news. If you share our vision, please contribute whatever you can to sustain our work. |
In Washington no bad idea stays dead long. Therefore it should not be surprising that U.S. President Donald Trump is planning to move forward with plans to privatize Fannie Mae and Freddie Mac, the mortgage giants that have been in government conservatorship for almost two decades.
As with many of the moves undertaken by Trump, it is not clear what problem this is meant to solve. For the period they have been in conservatorship, Fannie and Freddie have been securitizing mortgages at a low cost and have not faced any substantial management problems.
There is of course one problem that privatizing Fannie and Freddie would solve. This is yet one more way that the financial industry can run up some profits and high pay for top executives at the expense of the rest of us.
The Congressional Budget Office calculated that having private institutions, rather than Fannie and Freddie in their current form, would add roughly 20 basis points, 0.2% to the cost of securitizing mortgages. With around $1 trillion in mortgages being securitized each year, that comes to $2 billion annually. That is not huge in the context of the federal budget (0.03%), but it is four times the annual appropriation for the Corporation for Public Broadcasting that got Trump so upset.
Trump is giving a green light to his finance buddies to find every more creative ways to rip off businesses and ordinary people.
And in the case of privatizing Fannie and Freddie, we literally get nothing for it except a less efficient mechanism for securitizing mortgages. This is similar to the plans for privatizing Social Security. We have an extremely efficient public system, but many people in the Trump administration see the opportunity to make trillions of dollars in fees by turning it into a private system.
As with a privatized Social Security system, we would also be exposing ourselves to needless risk by privatizing Fannie and Freddie. The basic problem is that we would be allowing a private corporation to operate with a government guarantee against losses. This guarantee gives a private securitizer an enormous incentive to securitize bad mortgages in order to increase volume and make more profits. That was the story of the housing bubble and the subsequent collapse and financial crisis in 2008-09.
If a private securitizer is carefully regulated, it can limit the risk of reckless lending. But does anyone believe that the Trump administration is going to have careful regulation of the financial industry?
The basic story here is that in order to give donors in the financial industry still more money, Trump is planning to privatize a perfectly well-functioning public system for securitizing mortgages. This move will almost certainly increase the cost of mortgages for homebuyers, the only question is by how much. And it raises the risk for future financial crises and government bailouts.
Making the financial sector less efficient in order to hand money to contributors is very much front and center in the Trump administration. This is the same story with his decision to promote crypto currency, which is making Trump and his friends tens of billions of dollars; as opposed to letting the Federal Reserve Board issue a digital currency, which would save us tens of billions in bank and credit card fees.
The evisceration of the Consumer Financial Protection Bureau follows the same pattern. Trump is giving a green light to his finance buddies to find every more creative ways to rip off businesses and ordinary people.
That’s how we should understand the drive to privatize Fannie and Freddie. How could anyone oppose it?
In Washington no bad idea stays dead long. Therefore it should not be surprising that U.S. President Donald Trump is planning to move forward with plans to privatize Fannie Mae and Freddie Mac, the mortgage giants that have been in government conservatorship for almost two decades.
As with many of the moves undertaken by Trump, it is not clear what problem this is meant to solve. For the period they have been in conservatorship, Fannie and Freddie have been securitizing mortgages at a low cost and have not faced any substantial management problems.
There is of course one problem that privatizing Fannie and Freddie would solve. This is yet one more way that the financial industry can run up some profits and high pay for top executives at the expense of the rest of us.
The Congressional Budget Office calculated that having private institutions, rather than Fannie and Freddie in their current form, would add roughly 20 basis points, 0.2% to the cost of securitizing mortgages. With around $1 trillion in mortgages being securitized each year, that comes to $2 billion annually. That is not huge in the context of the federal budget (0.03%), but it is four times the annual appropriation for the Corporation for Public Broadcasting that got Trump so upset.
Trump is giving a green light to his finance buddies to find every more creative ways to rip off businesses and ordinary people.
And in the case of privatizing Fannie and Freddie, we literally get nothing for it except a less efficient mechanism for securitizing mortgages. This is similar to the plans for privatizing Social Security. We have an extremely efficient public system, but many people in the Trump administration see the opportunity to make trillions of dollars in fees by turning it into a private system.
As with a privatized Social Security system, we would also be exposing ourselves to needless risk by privatizing Fannie and Freddie. The basic problem is that we would be allowing a private corporation to operate with a government guarantee against losses. This guarantee gives a private securitizer an enormous incentive to securitize bad mortgages in order to increase volume and make more profits. That was the story of the housing bubble and the subsequent collapse and financial crisis in 2008-09.
If a private securitizer is carefully regulated, it can limit the risk of reckless lending. But does anyone believe that the Trump administration is going to have careful regulation of the financial industry?
The basic story here is that in order to give donors in the financial industry still more money, Trump is planning to privatize a perfectly well-functioning public system for securitizing mortgages. This move will almost certainly increase the cost of mortgages for homebuyers, the only question is by how much. And it raises the risk for future financial crises and government bailouts.
Making the financial sector less efficient in order to hand money to contributors is very much front and center in the Trump administration. This is the same story with his decision to promote crypto currency, which is making Trump and his friends tens of billions of dollars; as opposed to letting the Federal Reserve Board issue a digital currency, which would save us tens of billions in bank and credit card fees.
The evisceration of the Consumer Financial Protection Bureau follows the same pattern. Trump is giving a green light to his finance buddies to find every more creative ways to rip off businesses and ordinary people.
That’s how we should understand the drive to privatize Fannie and Freddie. How could anyone oppose it?