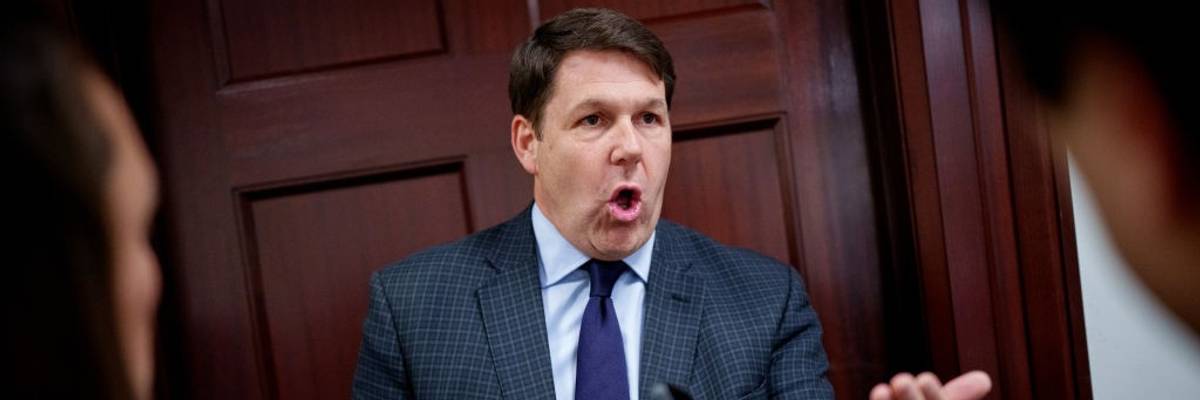
U.S. House Budget Committee Chairman Jodey Arrington (R-Texas) speaks to reporters before a House Republican caucus meeting at the U.S. Capitol on February 25, 2025 in Washington, D.C.
A House Tax Break Would Help the Rich at the Expense of the Rest
Extending or increasing a deduction for pass-through businesses is likely to exacerbate economic inequality, while delivering no economic benefits in the long run.
House Republicans’ tax plan would expand a tax break in the 2017 tax reform for “pass-through” businesses that has overwhelmingly benefited high earners. “Pass-throughs” are entities structured so that profits are not taxed at the business level but instead at the owners’ individual income tax rate.
The 2017 Tax Cuts and Jobs Act introduced a 20% deduction for Qualified Business Income (QBI) for pass-through businesses. House Republicans want to extend this tax break and increase it to 23%.
Contrary to proponents’ claims that the QBI deduction stimulates economic growth, economic research suggests a more nuanced and challenging reality. Recent analysis from our team at American University’s Institute for Macroeconomic and Policy Analysis (IMPA) reveals that extending or increasing the QBI is likely to exacerbate economic inequality, while delivering no economic benefits in the long run.
Extending the QBI deduction would systematically redistribute economic resources in ways that amplify existing inequalities.
Importantly, extending the QBI deduction would reduce government revenue significantly—by approximately 1.9% annually in the long run. Permanently increasing it would reduce revenue by 2.2% annually. These revenue losses represent a substantial fiscal challenge that cannot be overlooked.
Understanding Pass-Through Businesses
Traditional C corporations must pay the federal corporate income tax. Shareholders then pay individual income taxes on any profits distributed as dividends. In contrast, sole proprietorships, S corporations, and partnerships, as well as certain other types of businesses, are called “pass-throughs” because the businesses themselves do not pay taxes; instead, profits are passed through to individual owners, who then are taxed at their own individual tax rate. The QBI deduction reduces the amount of income from pass-throughs that is taxed.
According to Internal Revenue Service data, the number of nonfarm businesses organized as pass-throughs grew by 15% between 1980 and 2015, at which time more than 95% of all businesses were pass-throughs. But pass-through income is highly concentrated among top earners. Congressional Budget Office data show that, while income from pass-through businesses represents more than 20% of total household income for the top 1%, it accounts for merely 3% of income for the bottom 80% of households.
Think high-powered law firm partners or private equity fund executives. Without this tax break, they might owe the top marginal income tax rate of 37%. Under the current Republican proposal, they would owe just a 28.49% pass-through rate.
How Would Extending the QBI Deduction Affect the Economy?
Economic theory suggests that such tax deductions on business income have very little direct effects on real business activity if investment costs can be deducted from taxable income. And that is the case for pass-throughs. Because they can use accelerated depreciation provisions, taxes on their business income don’t change their investment decisions.
It’s not just theory: A recent study using tax record data finds no clear impact on investment, wages, or employment among pass-throughs that got an earlier tax break. A separate study found no impact on wages.
Even if tax breaks for businesses have no effect on individual business decisions, they can have negative effects on the economy as a whole. For example, such tax breaks reduce government revenue. If the revenue shortfall is financed by government borrowing, it can crowd out private investment. If the revenue shortfall is matched by reduced spending on public investment, such as scientific research, it is likely to reduce our standard of living in the long run. Such tax breaks also increase the after-tax required return to investors, which could cause businesses to distribute more profit, leaving less for investment.
We find that extending the QBI deduction would decrease government revenue by about 1.6% annually after 10 years and 1.9% in the long run.
Finally, such tax breaks increase after-tax profits and the market value of businesses, which raises the wealth of already-wealthy owners.
Our estimates using the IMPA macroeconomic policy model confirm that making the QBI deduction permanent would not boost economic activity, as is commonly claimed. Instead, we find that there would be a small decrease in GDP of 0.07% in the long run. Increasing the deduction to 23% would magnify the negative impact on economic activity.
Extending the QBI deduction would systematically redistribute economic resources in ways that amplify existing inequalities. Extending the QBI deduction would increase the share of the wealth owned by the top 1% by approximately 1.1%, while the bottom 50% would see their share fall by approximately 2.4%. Increasing the deduction, of course, redistributes even more wealth from the lower half of the distribution to the top.
Finally, we find that extending the QBI deduction would decrease government revenue by about 1.6% annually after 10 years and 1.9% in the long run. Increasing it permanently to 23% would reduce revenue 2.2% in the long run. How much is that? In the 2023 budget, 2% was enough to cover about three-quarters of the annual cost of the Supplemental Nutrition Assistance Program (SNAP). Or it would support 12 years of cancer research at 2023 levels.
To sum it up: QBI deduction costs taxpayers a lot, does not stimulate growth, and has regressive distributional consequences. There is no economic justification for its continuation.
We are at a crossroads
This country and this world are at a monumental crossroads. In a few short weeks, US voters will have an opportunity to beat back the forces of fascism and confront the billionaires who are rigging the economy, our media system, and our democracy, making it increasingly impossible for ordinary people to get by. We’re not just talking about the election. We’re talking about what must be done once these fascist elements are vanquished from power. We need a bolder set of solutions than what either major party has so far been willing to offer and a working-class movement ready to fight like hell for it. Trump didn't emerge from nowhere. The conditions that fueled MAGA authoritarianism were created by decades of radical neoliberal economic policies and a corrupt political system dominated by corporate interests. They slashed taxes on the super-rich, promising that the benefits would trickle down. They said giveaways to the corporate titans would make life more affordable for the rest of us. It was all bullshit. And when a bitter, betrayed populace searches for someone to blame, right-wing demagogues have little trouble finding scapegoats. People know when they're being lied to, but you won't hear any of this from the corporate media. Only independent journalism—powered and funded by people who believe in building a better world—can deliver truly trustworthy daily news. Our Fall Campaign is underway, and we need your help. To power our newsroom through the rest of the year, we need to raise $125,000 by midnight on October 31. So if you share our vision, please contribute whatever you can to sustain our work. |
House Republicans’ tax plan would expand a tax break in the 2017 tax reform for “pass-through” businesses that has overwhelmingly benefited high earners. “Pass-throughs” are entities structured so that profits are not taxed at the business level but instead at the owners’ individual income tax rate.
The 2017 Tax Cuts and Jobs Act introduced a 20% deduction for Qualified Business Income (QBI) for pass-through businesses. House Republicans want to extend this tax break and increase it to 23%.
Contrary to proponents’ claims that the QBI deduction stimulates economic growth, economic research suggests a more nuanced and challenging reality. Recent analysis from our team at American University’s Institute for Macroeconomic and Policy Analysis (IMPA) reveals that extending or increasing the QBI is likely to exacerbate economic inequality, while delivering no economic benefits in the long run.
Extending the QBI deduction would systematically redistribute economic resources in ways that amplify existing inequalities.
Importantly, extending the QBI deduction would reduce government revenue significantly—by approximately 1.9% annually in the long run. Permanently increasing it would reduce revenue by 2.2% annually. These revenue losses represent a substantial fiscal challenge that cannot be overlooked.
Understanding Pass-Through Businesses
Traditional C corporations must pay the federal corporate income tax. Shareholders then pay individual income taxes on any profits distributed as dividends. In contrast, sole proprietorships, S corporations, and partnerships, as well as certain other types of businesses, are called “pass-throughs” because the businesses themselves do not pay taxes; instead, profits are passed through to individual owners, who then are taxed at their own individual tax rate. The QBI deduction reduces the amount of income from pass-throughs that is taxed.
According to Internal Revenue Service data, the number of nonfarm businesses organized as pass-throughs grew by 15% between 1980 and 2015, at which time more than 95% of all businesses were pass-throughs. But pass-through income is highly concentrated among top earners. Congressional Budget Office data show that, while income from pass-through businesses represents more than 20% of total household income for the top 1%, it accounts for merely 3% of income for the bottom 80% of households.
Think high-powered law firm partners or private equity fund executives. Without this tax break, they might owe the top marginal income tax rate of 37%. Under the current Republican proposal, they would owe just a 28.49% pass-through rate.
How Would Extending the QBI Deduction Affect the Economy?
Economic theory suggests that such tax deductions on business income have very little direct effects on real business activity if investment costs can be deducted from taxable income. And that is the case for pass-throughs. Because they can use accelerated depreciation provisions, taxes on their business income don’t change their investment decisions.
It’s not just theory: A recent study using tax record data finds no clear impact on investment, wages, or employment among pass-throughs that got an earlier tax break. A separate study found no impact on wages.
Even if tax breaks for businesses have no effect on individual business decisions, they can have negative effects on the economy as a whole. For example, such tax breaks reduce government revenue. If the revenue shortfall is financed by government borrowing, it can crowd out private investment. If the revenue shortfall is matched by reduced spending on public investment, such as scientific research, it is likely to reduce our standard of living in the long run. Such tax breaks also increase the after-tax required return to investors, which could cause businesses to distribute more profit, leaving less for investment.
We find that extending the QBI deduction would decrease government revenue by about 1.6% annually after 10 years and 1.9% in the long run.
Finally, such tax breaks increase after-tax profits and the market value of businesses, which raises the wealth of already-wealthy owners.
Our estimates using the IMPA macroeconomic policy model confirm that making the QBI deduction permanent would not boost economic activity, as is commonly claimed. Instead, we find that there would be a small decrease in GDP of 0.07% in the long run. Increasing the deduction to 23% would magnify the negative impact on economic activity.
Extending the QBI deduction would systematically redistribute economic resources in ways that amplify existing inequalities. Extending the QBI deduction would increase the share of the wealth owned by the top 1% by approximately 1.1%, while the bottom 50% would see their share fall by approximately 2.4%. Increasing the deduction, of course, redistributes even more wealth from the lower half of the distribution to the top.
Finally, we find that extending the QBI deduction would decrease government revenue by about 1.6% annually after 10 years and 1.9% in the long run. Increasing it permanently to 23% would reduce revenue 2.2% in the long run. How much is that? In the 2023 budget, 2% was enough to cover about three-quarters of the annual cost of the Supplemental Nutrition Assistance Program (SNAP). Or it would support 12 years of cancer research at 2023 levels.
To sum it up: QBI deduction costs taxpayers a lot, does not stimulate growth, and has regressive distributional consequences. There is no economic justification for its continuation.
- As GOP Pushes Tax Giveaways for the Rich, Sanders Launches 'National Tour to Fight Oligarchy' ›
- Well, That Was Quick: Trump's Total Betrayal of Working People Is Now Complete ›
- Tax the Rich and Pay Public School Teachers More—It's Only Fair ›
- 'Not a Good Deal for Working Families': Sanders Votes No on Tax Bill ›
- 'We Are Not Taxing the Very Wealthy Enough': Runaway Inequality About to Get Worse ›