SUBSCRIBE TO OUR FREE NEWSLETTER
Daily news & progressive opinion—funded by the people, not the corporations—delivered straight to your inbox.
5
#000000
#FFFFFF
To donate by check, phone, or other method, see our More Ways to Give page.
Daily news & progressive opinion—funded by the people, not the corporations—delivered straight to your inbox.
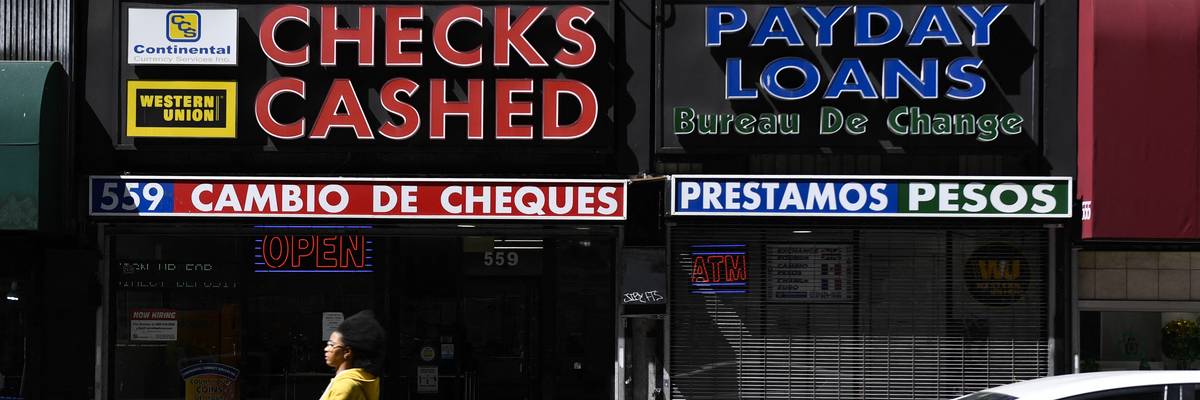
A person rides a scooter past a check cashing and payday loans store on March 11, 2022 in downtown Los Angeles, California.
"A policy of 'hear no evil, see no evil, punish no evil' is a sure-fire way to promote lawless behavior," said one advocate.
"Regulatory relief for small loan providers" was how the Trump administration described its decision not to prioritize enforcing a rule meant to protect people who are financially struggling from predatory payday lenders—but one consumer protection advocate said Monday that the announcement signals a policy that that is certain to "promote lawless behavior" by corporations.
The Consumer Financial Protection Bureau (CFPB), whose actions aimed at protecting working families and consumers from big banks and other corporations have been attacked for years by Republicans, announced last Friday that under the Trump administration, it will not enforce a rule meant to safeguard people from fees they accrue when payday lenders repeatedly attempt to debit their accounts.
Part of the 2017 payday loan rule, the bounced payment rule was set to go into effect on Sunday—barring payday lenders, "buy now, pay later" (BNPL) lending services, and other predatory lenders from continuing to make attempts to debit bank accounts after a loan customer's payment bounced twice. The lenders would be required under the rule to gain the customer's permission after two failed attempts to retrieve the payment.
When the CFPB announced last year that the rule was set to go into effect on March 30, 2025, it noted that it had "found one instance of a lender making 11 failed withdrawal attempts in one day"—subjecting the consumer to "a pile of junk fees" including nonsufficient (NSF) funds fees, overdraft charges, and others.
Adam Rust, director of financial services for the Consumer Federation of America, said Monday that the CFPB had "sided with bottom-feeder payday lenders at the expense of vulnerable borrowers struggling to make ends meet."
"The CFPB is designed to be a law enforcement agency," said Rust. "A policy of 'hear no evil, see no evil, punish no evil' is a surefire way to promote lawless behavior."
The agency said it would also not enforce rules applying to vehicle title loans, which can have high interest rates and are banned or limited in at least 30 states.
Lauren Saunders, associate director of the National Consumer Law Center, noted that former CFPB Director Kathy Kraninger, the U.S. Supreme Court, and the 5th Circuit previously upheld "the bare minimum protection against multiple NSF fees on unaffordable loans."
"It's outrageous that the CFPB will not enforce the law that prohibits payday lenders and other 200% APR lenders from continually debiting people's accounts, subjecting them to multiple NSF and overdraft fees," said Saunders. "Buy now, pay later lenders that make unaffordable loans should not be allowed to keep hitting your bank account after payments bounce twice. It's unconscionable to have greater protections for payday lenders than for people struggling to afford basic necessities."
A Pew survey in 2013 revealed that 1-in-4 payday loan customers faced an overdraft fee due to the lender's attempt to collect a payment from an account with insufficient funds.
The CFPB said it was contemplating "issuing a notice of proposed rulemaking to narrow the scope of the rule."
"By allowing payday lenders to repeatedly debit borrowers' empty bank accounts," Nadine Chabrier of the Center for Responsible Lending told Consumer Affairs, "the CFPB's political leadership is giving a free pass for payday lenders to kick people when they're down."
This country and this world are at a monumental crossroads. US voters have an opportunity to beat back the forces of fascism and confront the billionaires who are rigging the economy, our media system, and our democracy, making it increasingly impossible for ordinary people to get by. We’re not just talking about the election. We’re talking about what must be done once these fascist elements are vanquished from power. We need a bolder set of solutions than what either major party has so far been willing to offer and a working-class movement ready to fight like hell for it. Trump didn't emerge from nowhere. The conditions that fueled MAGA authoritarianism were created by decades of radical neoliberal economic policies and a corrupt political system dominated by corporate interests. They slashed taxes on the super-rich, promising that the benefits would trickle down. They said giveaways to the corporate titans would make life more affordable for the rest of us. It was all bullshit. And when a bitter, betrayed populace searches for someone to blame, right-wing demagogues have little trouble finding scapegoats. People know when they're being lied to, but you won't hear any of this from the corporate media. Only independent journalism—powered and funded by people who believe in building a better world—can deliver truly trustworthy daily news. If you share our vision, please contribute whatever you can to sustain our work. |
"Regulatory relief for small loan providers" was how the Trump administration described its decision not to prioritize enforcing a rule meant to protect people who are financially struggling from predatory payday lenders—but one consumer protection advocate said Monday that the announcement signals a policy that that is certain to "promote lawless behavior" by corporations.
The Consumer Financial Protection Bureau (CFPB), whose actions aimed at protecting working families and consumers from big banks and other corporations have been attacked for years by Republicans, announced last Friday that under the Trump administration, it will not enforce a rule meant to safeguard people from fees they accrue when payday lenders repeatedly attempt to debit their accounts.
Part of the 2017 payday loan rule, the bounced payment rule was set to go into effect on Sunday—barring payday lenders, "buy now, pay later" (BNPL) lending services, and other predatory lenders from continuing to make attempts to debit bank accounts after a loan customer's payment bounced twice. The lenders would be required under the rule to gain the customer's permission after two failed attempts to retrieve the payment.
When the CFPB announced last year that the rule was set to go into effect on March 30, 2025, it noted that it had "found one instance of a lender making 11 failed withdrawal attempts in one day"—subjecting the consumer to "a pile of junk fees" including nonsufficient (NSF) funds fees, overdraft charges, and others.
Adam Rust, director of financial services for the Consumer Federation of America, said Monday that the CFPB had "sided with bottom-feeder payday lenders at the expense of vulnerable borrowers struggling to make ends meet."
"The CFPB is designed to be a law enforcement agency," said Rust. "A policy of 'hear no evil, see no evil, punish no evil' is a surefire way to promote lawless behavior."
The agency said it would also not enforce rules applying to vehicle title loans, which can have high interest rates and are banned or limited in at least 30 states.
Lauren Saunders, associate director of the National Consumer Law Center, noted that former CFPB Director Kathy Kraninger, the U.S. Supreme Court, and the 5th Circuit previously upheld "the bare minimum protection against multiple NSF fees on unaffordable loans."
"It's outrageous that the CFPB will not enforce the law that prohibits payday lenders and other 200% APR lenders from continually debiting people's accounts, subjecting them to multiple NSF and overdraft fees," said Saunders. "Buy now, pay later lenders that make unaffordable loans should not be allowed to keep hitting your bank account after payments bounce twice. It's unconscionable to have greater protections for payday lenders than for people struggling to afford basic necessities."
A Pew survey in 2013 revealed that 1-in-4 payday loan customers faced an overdraft fee due to the lender's attempt to collect a payment from an account with insufficient funds.
The CFPB said it was contemplating "issuing a notice of proposed rulemaking to narrow the scope of the rule."
"By allowing payday lenders to repeatedly debit borrowers' empty bank accounts," Nadine Chabrier of the Center for Responsible Lending told Consumer Affairs, "the CFPB's political leadership is giving a free pass for payday lenders to kick people when they're down."
"Regulatory relief for small loan providers" was how the Trump administration described its decision not to prioritize enforcing a rule meant to protect people who are financially struggling from predatory payday lenders—but one consumer protection advocate said Monday that the announcement signals a policy that that is certain to "promote lawless behavior" by corporations.
The Consumer Financial Protection Bureau (CFPB), whose actions aimed at protecting working families and consumers from big banks and other corporations have been attacked for years by Republicans, announced last Friday that under the Trump administration, it will not enforce a rule meant to safeguard people from fees they accrue when payday lenders repeatedly attempt to debit their accounts.
Part of the 2017 payday loan rule, the bounced payment rule was set to go into effect on Sunday—barring payday lenders, "buy now, pay later" (BNPL) lending services, and other predatory lenders from continuing to make attempts to debit bank accounts after a loan customer's payment bounced twice. The lenders would be required under the rule to gain the customer's permission after two failed attempts to retrieve the payment.
When the CFPB announced last year that the rule was set to go into effect on March 30, 2025, it noted that it had "found one instance of a lender making 11 failed withdrawal attempts in one day"—subjecting the consumer to "a pile of junk fees" including nonsufficient (NSF) funds fees, overdraft charges, and others.
Adam Rust, director of financial services for the Consumer Federation of America, said Monday that the CFPB had "sided with bottom-feeder payday lenders at the expense of vulnerable borrowers struggling to make ends meet."
"The CFPB is designed to be a law enforcement agency," said Rust. "A policy of 'hear no evil, see no evil, punish no evil' is a surefire way to promote lawless behavior."
The agency said it would also not enforce rules applying to vehicle title loans, which can have high interest rates and are banned or limited in at least 30 states.
Lauren Saunders, associate director of the National Consumer Law Center, noted that former CFPB Director Kathy Kraninger, the U.S. Supreme Court, and the 5th Circuit previously upheld "the bare minimum protection against multiple NSF fees on unaffordable loans."
"It's outrageous that the CFPB will not enforce the law that prohibits payday lenders and other 200% APR lenders from continually debiting people's accounts, subjecting them to multiple NSF and overdraft fees," said Saunders. "Buy now, pay later lenders that make unaffordable loans should not be allowed to keep hitting your bank account after payments bounce twice. It's unconscionable to have greater protections for payday lenders than for people struggling to afford basic necessities."
A Pew survey in 2013 revealed that 1-in-4 payday loan customers faced an overdraft fee due to the lender's attempt to collect a payment from an account with insufficient funds.
The CFPB said it was contemplating "issuing a notice of proposed rulemaking to narrow the scope of the rule."
"By allowing payday lenders to repeatedly debit borrowers' empty bank accounts," Nadine Chabrier of the Center for Responsible Lending told Consumer Affairs, "the CFPB's political leadership is giving a free pass for payday lenders to kick people when they're down."