SUBSCRIBE TO OUR FREE NEWSLETTER
Daily news & progressive opinion—funded by the people, not the corporations—delivered straight to your inbox.
5
#000000
#FFFFFF
To donate by check, phone, or other method, see our More Ways to Give page.
Daily news & progressive opinion—funded by the people, not the corporations—delivered straight to your inbox.
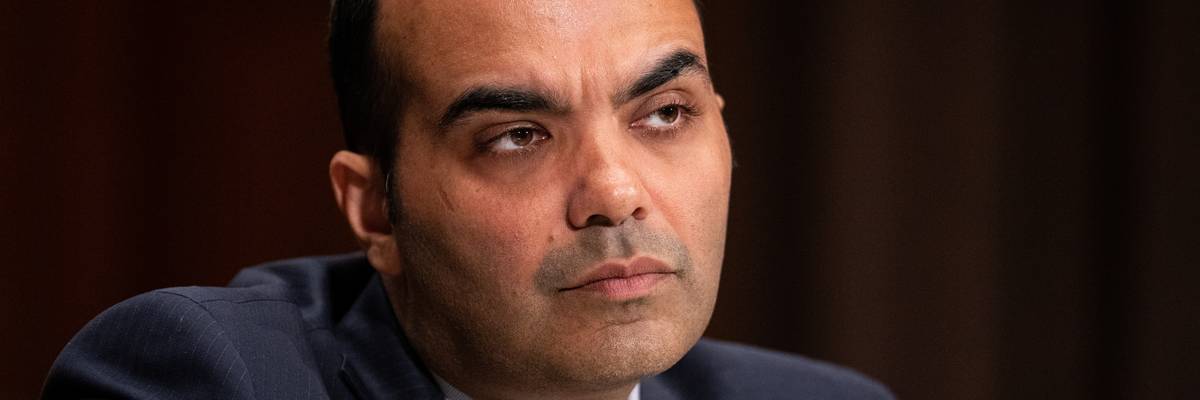
Consumer Financial Protection Bureau Director Rohit Chopra testifies in Washington, D.C. on June 12, 2024.
"The CFPB's actions will help workers know what they are getting with these products and prevent race-to-the-bottom business practices," said the director of the bureau.
With inflation rising in recent years, driven by corporate greed according to numerous analyses, the number of people in the U.S. who have relied on paycheck advance products has skyrocketed—but a rule introduced Thursday by the Consumer Financial Protection Bureau is aimed at ensuring that lenders who provide these products are transparent with financially struggling workers about the fees they can incur.
The CFPB proposed a rule clarifying that paycheck advances, sometimes marketed as "earned wage" products, are consumer loans and are therefore subject to the Truth in Lending Act.
The federal law requires lenders to disclose all fees, interest, and total costs consumers will incur before they use the product.
According to a study released by the CFPB as it announced the new proposed rule, the number of paycheck advance transactions processed by employer-partnered firms ballooned by 90% from 2021-22. More than 7 million workers used paycheck advances to access $22 million over that time period in order to pay for their housing, utilities, and other essentials.
The study notes that "the mismatch between when a family receives income and when a family must make payments for expenses" is a major driver of demand for consumer credit and other products like paycheck advances.
"To reduce their costs, employers have a strong incentive to delay the payment of compensation to workers, which drives demand for short-term credit," reads the analysis.
As such, said Rohit Chopra, director of the CFPB, paycheck advances "are often marketed to and designed for employers, rather than employees."
"The CFPB's interpretive rule will level the playing field and promote competition among short-term small-dollar lenders."
"The CFPB's actions will help workers know what they are getting with these products and prevent race-to-the-bottom business practices," he said.
Th bureau's report focuses on employer-sponsored paycheck advances, which have been increasingly used over and over by the same workers. Employees took out an average of 27 paycheck advance loans per year, according to the CFPB, with the average transaction totaling $106.
"The share of workers in our sample using the product at least once a month increased from 41% in 2021 to nearly 50% in 2022," wrote the CFPB.
The bureau noted that while employers sometimes make paycheck advances fee-free for their employees, workers usually pay fees themselves, including expedited service fees and "tips" that the online services request when completing the transaction.
In the sample the CFPB reviewed, employers paid for less than 5% of the fees incurred by workers
"Across our sample of surveyed companies, in 2021 and 2022, roughly 90% of workers paid at least one earned wage product-related fee," said the bureau. "Among the companies in our sample that collect fees, the average cost per transaction ranged from $0.61 to $4.70. When workers paid a fee, the average size was approximately $3.18. Workers paid an average of $68.88 per year in fees."
Some services provide subscriptions for workers who used paycheck advances regularly; those who utilize them can pay as much as $14.99 per month in subscription fees, according to the CFPB.
"In recent years, workers have seen big increases in wages, but junk fees and high rates on financial products not only chip away at these gains—they take advantage of workers," acting Labor Secretary Julie Su said in a statement.
Adam Rust, director of financial services for the Consumer Federation of America, said the proposed rule shows that "an advance on wages is still a loan that has to be repaid, and no amount of hair-splitting can change it."
"Workers have always relied on wages to repay advances from lenders," said Rust. "Policymakers should be skeptical whenever lenders insist on regulatory exemptions from rules that apply to their competitors. The CFPB's interpretive rule will level the playing field and promote competition among short-term small-dollar lenders."
The CFPB is among several federal agencies that right-wing operatives, many of whom worked in the Trump administration, have pledged to abolish under the policy agenda Project 2025.
Under the Biden administration, in addition to taking aim at paycheck advances, the CFPB has proposed a rule to cap credit card late fees at $8, a move that would save Americans $10 billion per year; prevented discrimination by small business lenders; and fined Wells Fargo $3.7 billion for illegal activity.
This country and this world are at a monumental crossroads. US voters have an opportunity to beat back the forces of fascism and confront the billionaires who are rigging the economy, our media system, and our democracy, making it increasingly impossible for ordinary people to get by. We’re not just talking about the election. We’re talking about what must be done once these fascist elements are vanquished from power. We need a bolder set of solutions than what either major party has so far been willing to offer and a working-class movement ready to fight like hell for it. Trump didn't emerge from nowhere. The conditions that fueled MAGA authoritarianism were created by decades of radical neoliberal economic policies and a corrupt political system dominated by corporate interests. They slashed taxes on the super-rich, promising that the benefits would trickle down. They said giveaways to the corporate titans would make life more affordable for the rest of us. It was all bullshit. And when a bitter, betrayed populace searches for someone to blame, right-wing demagogues have little trouble finding scapegoats. People know when they're being lied to, but you won't hear any of this from the corporate media. Only independent journalism—powered and funded by people who believe in building a better world—can deliver truly trustworthy daily news. If you share our vision, please contribute whatever you can to sustain our work. |
With inflation rising in recent years, driven by corporate greed according to numerous analyses, the number of people in the U.S. who have relied on paycheck advance products has skyrocketed—but a rule introduced Thursday by the Consumer Financial Protection Bureau is aimed at ensuring that lenders who provide these products are transparent with financially struggling workers about the fees they can incur.
The CFPB proposed a rule clarifying that paycheck advances, sometimes marketed as "earned wage" products, are consumer loans and are therefore subject to the Truth in Lending Act.
The federal law requires lenders to disclose all fees, interest, and total costs consumers will incur before they use the product.
According to a study released by the CFPB as it announced the new proposed rule, the number of paycheck advance transactions processed by employer-partnered firms ballooned by 90% from 2021-22. More than 7 million workers used paycheck advances to access $22 million over that time period in order to pay for their housing, utilities, and other essentials.
The study notes that "the mismatch between when a family receives income and when a family must make payments for expenses" is a major driver of demand for consumer credit and other products like paycheck advances.
"To reduce their costs, employers have a strong incentive to delay the payment of compensation to workers, which drives demand for short-term credit," reads the analysis.
As such, said Rohit Chopra, director of the CFPB, paycheck advances "are often marketed to and designed for employers, rather than employees."
"The CFPB's interpretive rule will level the playing field and promote competition among short-term small-dollar lenders."
"The CFPB's actions will help workers know what they are getting with these products and prevent race-to-the-bottom business practices," he said.
Th bureau's report focuses on employer-sponsored paycheck advances, which have been increasingly used over and over by the same workers. Employees took out an average of 27 paycheck advance loans per year, according to the CFPB, with the average transaction totaling $106.
"The share of workers in our sample using the product at least once a month increased from 41% in 2021 to nearly 50% in 2022," wrote the CFPB.
The bureau noted that while employers sometimes make paycheck advances fee-free for their employees, workers usually pay fees themselves, including expedited service fees and "tips" that the online services request when completing the transaction.
In the sample the CFPB reviewed, employers paid for less than 5% of the fees incurred by workers
"Across our sample of surveyed companies, in 2021 and 2022, roughly 90% of workers paid at least one earned wage product-related fee," said the bureau. "Among the companies in our sample that collect fees, the average cost per transaction ranged from $0.61 to $4.70. When workers paid a fee, the average size was approximately $3.18. Workers paid an average of $68.88 per year in fees."
Some services provide subscriptions for workers who used paycheck advances regularly; those who utilize them can pay as much as $14.99 per month in subscription fees, according to the CFPB.
"In recent years, workers have seen big increases in wages, but junk fees and high rates on financial products not only chip away at these gains—they take advantage of workers," acting Labor Secretary Julie Su said in a statement.
Adam Rust, director of financial services for the Consumer Federation of America, said the proposed rule shows that "an advance on wages is still a loan that has to be repaid, and no amount of hair-splitting can change it."
"Workers have always relied on wages to repay advances from lenders," said Rust. "Policymakers should be skeptical whenever lenders insist on regulatory exemptions from rules that apply to their competitors. The CFPB's interpretive rule will level the playing field and promote competition among short-term small-dollar lenders."
The CFPB is among several federal agencies that right-wing operatives, many of whom worked in the Trump administration, have pledged to abolish under the policy agenda Project 2025.
Under the Biden administration, in addition to taking aim at paycheck advances, the CFPB has proposed a rule to cap credit card late fees at $8, a move that would save Americans $10 billion per year; prevented discrimination by small business lenders; and fined Wells Fargo $3.7 billion for illegal activity.
With inflation rising in recent years, driven by corporate greed according to numerous analyses, the number of people in the U.S. who have relied on paycheck advance products has skyrocketed—but a rule introduced Thursday by the Consumer Financial Protection Bureau is aimed at ensuring that lenders who provide these products are transparent with financially struggling workers about the fees they can incur.
The CFPB proposed a rule clarifying that paycheck advances, sometimes marketed as "earned wage" products, are consumer loans and are therefore subject to the Truth in Lending Act.
The federal law requires lenders to disclose all fees, interest, and total costs consumers will incur before they use the product.
According to a study released by the CFPB as it announced the new proposed rule, the number of paycheck advance transactions processed by employer-partnered firms ballooned by 90% from 2021-22. More than 7 million workers used paycheck advances to access $22 million over that time period in order to pay for their housing, utilities, and other essentials.
The study notes that "the mismatch between when a family receives income and when a family must make payments for expenses" is a major driver of demand for consumer credit and other products like paycheck advances.
"To reduce their costs, employers have a strong incentive to delay the payment of compensation to workers, which drives demand for short-term credit," reads the analysis.
As such, said Rohit Chopra, director of the CFPB, paycheck advances "are often marketed to and designed for employers, rather than employees."
"The CFPB's interpretive rule will level the playing field and promote competition among short-term small-dollar lenders."
"The CFPB's actions will help workers know what they are getting with these products and prevent race-to-the-bottom business practices," he said.
Th bureau's report focuses on employer-sponsored paycheck advances, which have been increasingly used over and over by the same workers. Employees took out an average of 27 paycheck advance loans per year, according to the CFPB, with the average transaction totaling $106.
"The share of workers in our sample using the product at least once a month increased from 41% in 2021 to nearly 50% in 2022," wrote the CFPB.
The bureau noted that while employers sometimes make paycheck advances fee-free for their employees, workers usually pay fees themselves, including expedited service fees and "tips" that the online services request when completing the transaction.
In the sample the CFPB reviewed, employers paid for less than 5% of the fees incurred by workers
"Across our sample of surveyed companies, in 2021 and 2022, roughly 90% of workers paid at least one earned wage product-related fee," said the bureau. "Among the companies in our sample that collect fees, the average cost per transaction ranged from $0.61 to $4.70. When workers paid a fee, the average size was approximately $3.18. Workers paid an average of $68.88 per year in fees."
Some services provide subscriptions for workers who used paycheck advances regularly; those who utilize them can pay as much as $14.99 per month in subscription fees, according to the CFPB.
"In recent years, workers have seen big increases in wages, but junk fees and high rates on financial products not only chip away at these gains—they take advantage of workers," acting Labor Secretary Julie Su said in a statement.
Adam Rust, director of financial services for the Consumer Federation of America, said the proposed rule shows that "an advance on wages is still a loan that has to be repaid, and no amount of hair-splitting can change it."
"Workers have always relied on wages to repay advances from lenders," said Rust. "Policymakers should be skeptical whenever lenders insist on regulatory exemptions from rules that apply to their competitors. The CFPB's interpretive rule will level the playing field and promote competition among short-term small-dollar lenders."
The CFPB is among several federal agencies that right-wing operatives, many of whom worked in the Trump administration, have pledged to abolish under the policy agenda Project 2025.
Under the Biden administration, in addition to taking aim at paycheck advances, the CFPB has proposed a rule to cap credit card late fees at $8, a move that would save Americans $10 billion per year; prevented discrimination by small business lenders; and fined Wells Fargo $3.7 billion for illegal activity.