SUBSCRIBE TO OUR FREE NEWSLETTER
Daily news & progressive opinion—funded by the people, not the corporations—delivered straight to your inbox.
5
#000000
#FFFFFF
To donate by check, phone, or other method, see our More Ways to Give page.
Daily news & progressive opinion—funded by the people, not the corporations—delivered straight to your inbox.
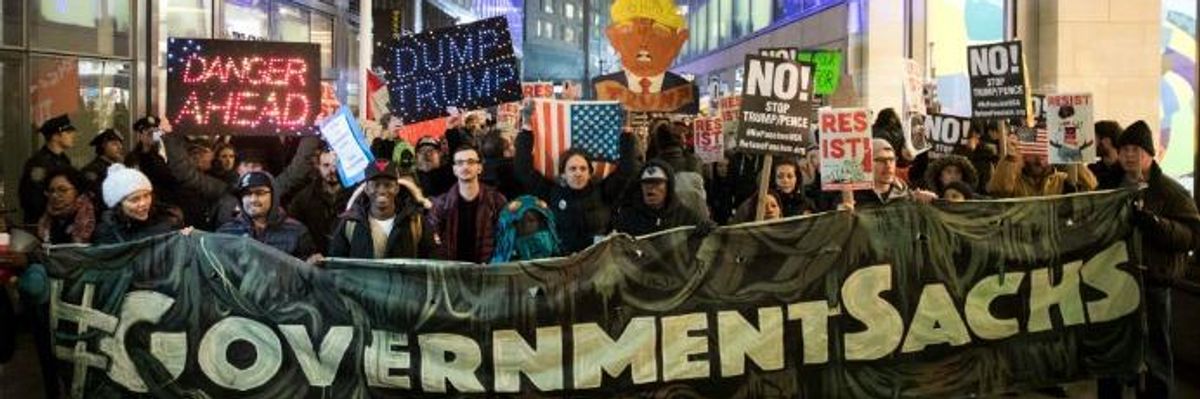
Activists rally against President Donald Trump's reported plans to loosen Wall Street Regulations and repeal the Dodd-Frank Act outside of Goldman Sachs headquarters in Lower Manhattan, February 7, 2017 in New York City. (Photo by Drew Angerer/Getty Images)
As most Americans report that they have seen little to no paycheck boost thanks to the Trump-GOP tax cuts, the very biggest Wall Street banks are reporting quite the opposite: record profits.
Thanks to the Republican law's drastic reduction of the corporate tax rate from 35 percent to 21 percent, the combined earnings of Goldman Sachs, JP Morgan Chase, Citigroup, and Wells Fargo "increased by more than $2.5 billion" in just the first three months of 2018, the Wall Street Journal found in an analysis of bank earnings reports on Tuesday.
"Months after the Republican tax bill passed, we're watching corporations do exactly what they told us they'd do all along: rather than raising wages and creating jobs, they're rewarding their investors and execs with billions of dollars."
--Sen. Sherrod Brown
"Without the tax savings resulting from the new lower corporate tax rate, Wells Fargo's earnings would have declined from a year ago instead of increasing, and much of the year-over-year growth at Citigroup and Bank of America would be gone," the Journal noted. "Losing the tax bump would have cut the earnings growth of JPMorgan to 28 percent from 35 percent; for Goldman, growth would have shrunk by at least a quarter."
Joining the profit bonanza on Wednesday was Morgan Stanley, which posted record quarterly earnings and a 40 percent profit jump thanks in large part to lower taxes.
The Wall Street earnings reports rolled in just as President Donald Trump was using the occasion of Tax Day to proclaim that ordinary Americans are "winning" thanks to the plan he signed into law last December.
But the numbers show that any benefits American workers may be seeing from the $1.5 trillion in tax cuts are far outweighed by the soaring paychecks of investors and corporate fat cats.
"Tax cut riches have gone to execs and investors over workers by [a] nearly 3-to-1 margin," CNBC found in an analysis published on Tuesday.
Chad Bolt, associate policy director at Indivisible, noted that Wall Street's soaring profits alongside meager worker gains should hardly be surprising, given that the Trump-GOP tax plan "was always a scam on the American people."
Bolt also points to the fact that Republicans--with the help of many Democrats--are currently attempting to ram through a bank deregulation bill that will push Wall Street earnings even higher while drastically increasing the risk of another financial meltdown.
"Months after the Republican tax bill passed, we're watching corporations do exactly what they told us they'd do all along: rather than raising wages and creating jobs, they're rewarding their investors and execs with billions of dollars, right now in the form of stock buybacks," Sen. Sherrod Brown (D-Ohio) noted in a tweet on Tuesday. "Make no mistake: this so-called 'tax cut' was never about helping middle class families."
This country and this world are at a monumental crossroads. US voters have an opportunity to beat back the forces of fascism and confront the billionaires who are rigging the economy, our media system, and our democracy, making it increasingly impossible for ordinary people to get by. We’re not just talking about the election. We’re talking about what must be done once these fascist elements are vanquished from power. We need a bolder set of solutions than what either major party has so far been willing to offer and a working-class movement ready to fight like hell for it. Trump didn't emerge from nowhere. The conditions that fueled MAGA authoritarianism were created by decades of radical neoliberal economic policies and a corrupt political system dominated by corporate interests. They slashed taxes on the super-rich, promising that the benefits would trickle down. They said giveaways to the corporate titans would make life more affordable for the rest of us. It was all bullshit. And when a bitter, betrayed populace searches for someone to blame, right-wing demagogues have little trouble finding scapegoats. People know when they're being lied to, but you won't hear any of this from the corporate media. Only independent journalism—powered and funded by people who believe in building a better world—can deliver truly trustworthy daily news. If you share our vision, please contribute whatever you can to sustain our work. |
As most Americans report that they have seen little to no paycheck boost thanks to the Trump-GOP tax cuts, the very biggest Wall Street banks are reporting quite the opposite: record profits.
Thanks to the Republican law's drastic reduction of the corporate tax rate from 35 percent to 21 percent, the combined earnings of Goldman Sachs, JP Morgan Chase, Citigroup, and Wells Fargo "increased by more than $2.5 billion" in just the first three months of 2018, the Wall Street Journal found in an analysis of bank earnings reports on Tuesday.
"Months after the Republican tax bill passed, we're watching corporations do exactly what they told us they'd do all along: rather than raising wages and creating jobs, they're rewarding their investors and execs with billions of dollars."
--Sen. Sherrod Brown
"Without the tax savings resulting from the new lower corporate tax rate, Wells Fargo's earnings would have declined from a year ago instead of increasing, and much of the year-over-year growth at Citigroup and Bank of America would be gone," the Journal noted. "Losing the tax bump would have cut the earnings growth of JPMorgan to 28 percent from 35 percent; for Goldman, growth would have shrunk by at least a quarter."
Joining the profit bonanza on Wednesday was Morgan Stanley, which posted record quarterly earnings and a 40 percent profit jump thanks in large part to lower taxes.
The Wall Street earnings reports rolled in just as President Donald Trump was using the occasion of Tax Day to proclaim that ordinary Americans are "winning" thanks to the plan he signed into law last December.
But the numbers show that any benefits American workers may be seeing from the $1.5 trillion in tax cuts are far outweighed by the soaring paychecks of investors and corporate fat cats.
"Tax cut riches have gone to execs and investors over workers by [a] nearly 3-to-1 margin," CNBC found in an analysis published on Tuesday.
Chad Bolt, associate policy director at Indivisible, noted that Wall Street's soaring profits alongside meager worker gains should hardly be surprising, given that the Trump-GOP tax plan "was always a scam on the American people."
Bolt also points to the fact that Republicans--with the help of many Democrats--are currently attempting to ram through a bank deregulation bill that will push Wall Street earnings even higher while drastically increasing the risk of another financial meltdown.
"Months after the Republican tax bill passed, we're watching corporations do exactly what they told us they'd do all along: rather than raising wages and creating jobs, they're rewarding their investors and execs with billions of dollars, right now in the form of stock buybacks," Sen. Sherrod Brown (D-Ohio) noted in a tweet on Tuesday. "Make no mistake: this so-called 'tax cut' was never about helping middle class families."
As most Americans report that they have seen little to no paycheck boost thanks to the Trump-GOP tax cuts, the very biggest Wall Street banks are reporting quite the opposite: record profits.
Thanks to the Republican law's drastic reduction of the corporate tax rate from 35 percent to 21 percent, the combined earnings of Goldman Sachs, JP Morgan Chase, Citigroup, and Wells Fargo "increased by more than $2.5 billion" in just the first three months of 2018, the Wall Street Journal found in an analysis of bank earnings reports on Tuesday.
"Months after the Republican tax bill passed, we're watching corporations do exactly what they told us they'd do all along: rather than raising wages and creating jobs, they're rewarding their investors and execs with billions of dollars."
--Sen. Sherrod Brown
"Without the tax savings resulting from the new lower corporate tax rate, Wells Fargo's earnings would have declined from a year ago instead of increasing, and much of the year-over-year growth at Citigroup and Bank of America would be gone," the Journal noted. "Losing the tax bump would have cut the earnings growth of JPMorgan to 28 percent from 35 percent; for Goldman, growth would have shrunk by at least a quarter."
Joining the profit bonanza on Wednesday was Morgan Stanley, which posted record quarterly earnings and a 40 percent profit jump thanks in large part to lower taxes.
The Wall Street earnings reports rolled in just as President Donald Trump was using the occasion of Tax Day to proclaim that ordinary Americans are "winning" thanks to the plan he signed into law last December.
But the numbers show that any benefits American workers may be seeing from the $1.5 trillion in tax cuts are far outweighed by the soaring paychecks of investors and corporate fat cats.
"Tax cut riches have gone to execs and investors over workers by [a] nearly 3-to-1 margin," CNBC found in an analysis published on Tuesday.
Chad Bolt, associate policy director at Indivisible, noted that Wall Street's soaring profits alongside meager worker gains should hardly be surprising, given that the Trump-GOP tax plan "was always a scam on the American people."
Bolt also points to the fact that Republicans--with the help of many Democrats--are currently attempting to ram through a bank deregulation bill that will push Wall Street earnings even higher while drastically increasing the risk of another financial meltdown.
"Months after the Republican tax bill passed, we're watching corporations do exactly what they told us they'd do all along: rather than raising wages and creating jobs, they're rewarding their investors and execs with billions of dollars, right now in the form of stock buybacks," Sen. Sherrod Brown (D-Ohio) noted in a tweet on Tuesday. "Make no mistake: this so-called 'tax cut' was never about helping middle class families."