SUBSCRIBE TO OUR FREE NEWSLETTER
Daily news & progressive opinion—funded by the people, not the corporations—delivered straight to your inbox.
5
#000000
#FFFFFF
To donate by check, phone, or other method, see our More Ways to Give page.
Daily news & progressive opinion—funded by the people, not the corporations—delivered straight to your inbox.
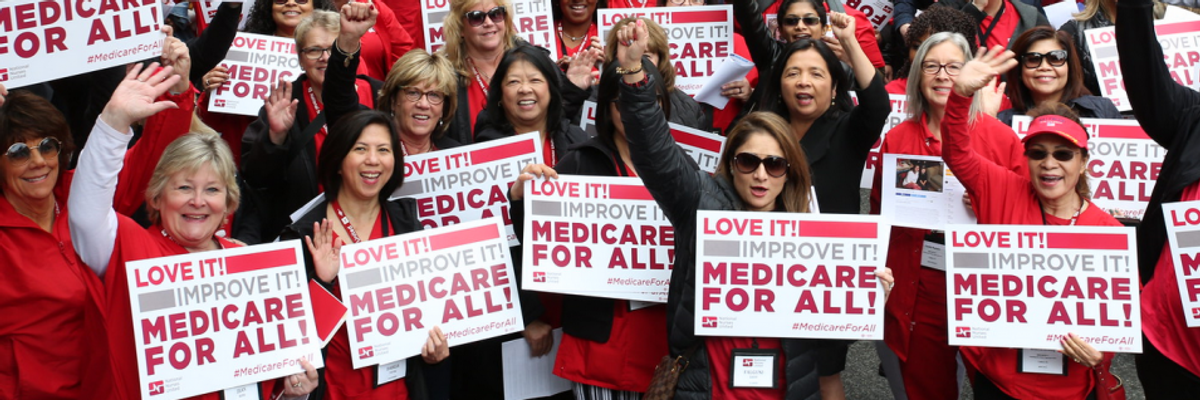
A comprehensive policy solution would be to extend Medicare and Medicaid to all those suffering job losses during the pandemic period, with the federal government funding this expansion.(Photo: NNU/flickr/cc)
Since the economic fallout of the coronavirus shock began in early March, the number of workers laid-off or furloughed--as measured by new claims for unemployment insurance (UI)--has skyrocketed. We have used data from states that track UI claims by industry to get a rough estimate of how many workers are at high risk of losing their employer-provided health insurance (EPHI) over this as well.
The methodology is described in this blog post, and the underlying data (which has begun to include more and more states tracking UI claims by industry) can be found here. Table 1 below shows UI claims by industry across states that collect this data, and also shows employer-provided health insurance (EPHI) coverage rates in those industries in 2018. As of April 30, just under 28 million workers had been laid off or furloughed since early March. We find that this translates into likely EPHI losses of 12.7 million.
Because the United States is unique among rich countries in tying health insurance benefits to employment, many of the newly unemployed will suddenly face prohibitively costly insurance options. A comprehensive policy solution would be to extend Medicare and Medicaid to all those suffering job losses during the pandemic period, with the federal government funding this expansion. It has been proposed that the federal government pay for all of COBRA coverage so that workers who are laid off or furloughed may continue their employer-provided coverage. While this policy proposal will help many workers continue coverage, in some states it will not help workers from small businesses with fewer than 20 employees, who are not eligible for COBRA.
The linkage between specific jobs and the availability of health insurance is a prime source of inefficiency and inequity in the U.S. health system. It is especially terrifying for workers to lose their health insurance as a result of, and during, an ongoing pandemic.
We additionally allocate EPHI losses across states, taking account of each states' industry mix (again, the precise methodology for this calculation can be found here). The map below shows these losses allocated across states.
This country and this world are at a monumental crossroads. US voters have an opportunity to beat back the forces of fascism and confront the billionaires who are rigging the economy, our media system, and our democracy, making it increasingly impossible for ordinary people to get by. We’re not just talking about the election. We’re talking about what must be done once these fascist elements are vanquished from power. We need a bolder set of solutions than what either major party has so far been willing to offer and a working-class movement ready to fight like hell for it. Trump didn't emerge from nowhere. The conditions that fueled MAGA authoritarianism were created by decades of radical neoliberal economic policies and a corrupt political system dominated by corporate interests. They slashed taxes on the super-rich, promising that the benefits would trickle down. They said giveaways to the corporate titans would make life more affordable for the rest of us. It was all bullshit. And when a bitter, betrayed populace searches for someone to blame, right-wing demagogues have little trouble finding scapegoats. People know when they're being lied to, but you won't hear any of this from the corporate media. Only independent journalism—powered and funded by people who believe in building a better world—can deliver truly trustworthy daily news. If you share our vision, please contribute whatever you can to sustain our work. |
Since the economic fallout of the coronavirus shock began in early March, the number of workers laid-off or furloughed--as measured by new claims for unemployment insurance (UI)--has skyrocketed. We have used data from states that track UI claims by industry to get a rough estimate of how many workers are at high risk of losing their employer-provided health insurance (EPHI) over this as well.
The methodology is described in this blog post, and the underlying data (which has begun to include more and more states tracking UI claims by industry) can be found here. Table 1 below shows UI claims by industry across states that collect this data, and also shows employer-provided health insurance (EPHI) coverage rates in those industries in 2018. As of April 30, just under 28 million workers had been laid off or furloughed since early March. We find that this translates into likely EPHI losses of 12.7 million.
Because the United States is unique among rich countries in tying health insurance benefits to employment, many of the newly unemployed will suddenly face prohibitively costly insurance options. A comprehensive policy solution would be to extend Medicare and Medicaid to all those suffering job losses during the pandemic period, with the federal government funding this expansion. It has been proposed that the federal government pay for all of COBRA coverage so that workers who are laid off or furloughed may continue their employer-provided coverage. While this policy proposal will help many workers continue coverage, in some states it will not help workers from small businesses with fewer than 20 employees, who are not eligible for COBRA.
The linkage between specific jobs and the availability of health insurance is a prime source of inefficiency and inequity in the U.S. health system. It is especially terrifying for workers to lose their health insurance as a result of, and during, an ongoing pandemic.
We additionally allocate EPHI losses across states, taking account of each states' industry mix (again, the precise methodology for this calculation can be found here). The map below shows these losses allocated across states.
Since the economic fallout of the coronavirus shock began in early March, the number of workers laid-off or furloughed--as measured by new claims for unemployment insurance (UI)--has skyrocketed. We have used data from states that track UI claims by industry to get a rough estimate of how many workers are at high risk of losing their employer-provided health insurance (EPHI) over this as well.
The methodology is described in this blog post, and the underlying data (which has begun to include more and more states tracking UI claims by industry) can be found here. Table 1 below shows UI claims by industry across states that collect this data, and also shows employer-provided health insurance (EPHI) coverage rates in those industries in 2018. As of April 30, just under 28 million workers had been laid off or furloughed since early March. We find that this translates into likely EPHI losses of 12.7 million.
Because the United States is unique among rich countries in tying health insurance benefits to employment, many of the newly unemployed will suddenly face prohibitively costly insurance options. A comprehensive policy solution would be to extend Medicare and Medicaid to all those suffering job losses during the pandemic period, with the federal government funding this expansion. It has been proposed that the federal government pay for all of COBRA coverage so that workers who are laid off or furloughed may continue their employer-provided coverage. While this policy proposal will help many workers continue coverage, in some states it will not help workers from small businesses with fewer than 20 employees, who are not eligible for COBRA.
The linkage between specific jobs and the availability of health insurance is a prime source of inefficiency and inequity in the U.S. health system. It is especially terrifying for workers to lose their health insurance as a result of, and during, an ongoing pandemic.
We additionally allocate EPHI losses across states, taking account of each states' industry mix (again, the precise methodology for this calculation can be found here). The map below shows these losses allocated across states.