The Barclays interest-rate scandal, HSBC's openness to money laundering by Mexican drug traffickers, the epic blunders at JPMorgan Chase -- at this point, four years after Wall Street wrecked the global economy, does anyone really believe we can regulate the big banks? And if we broke them up, would they really stay broken up?
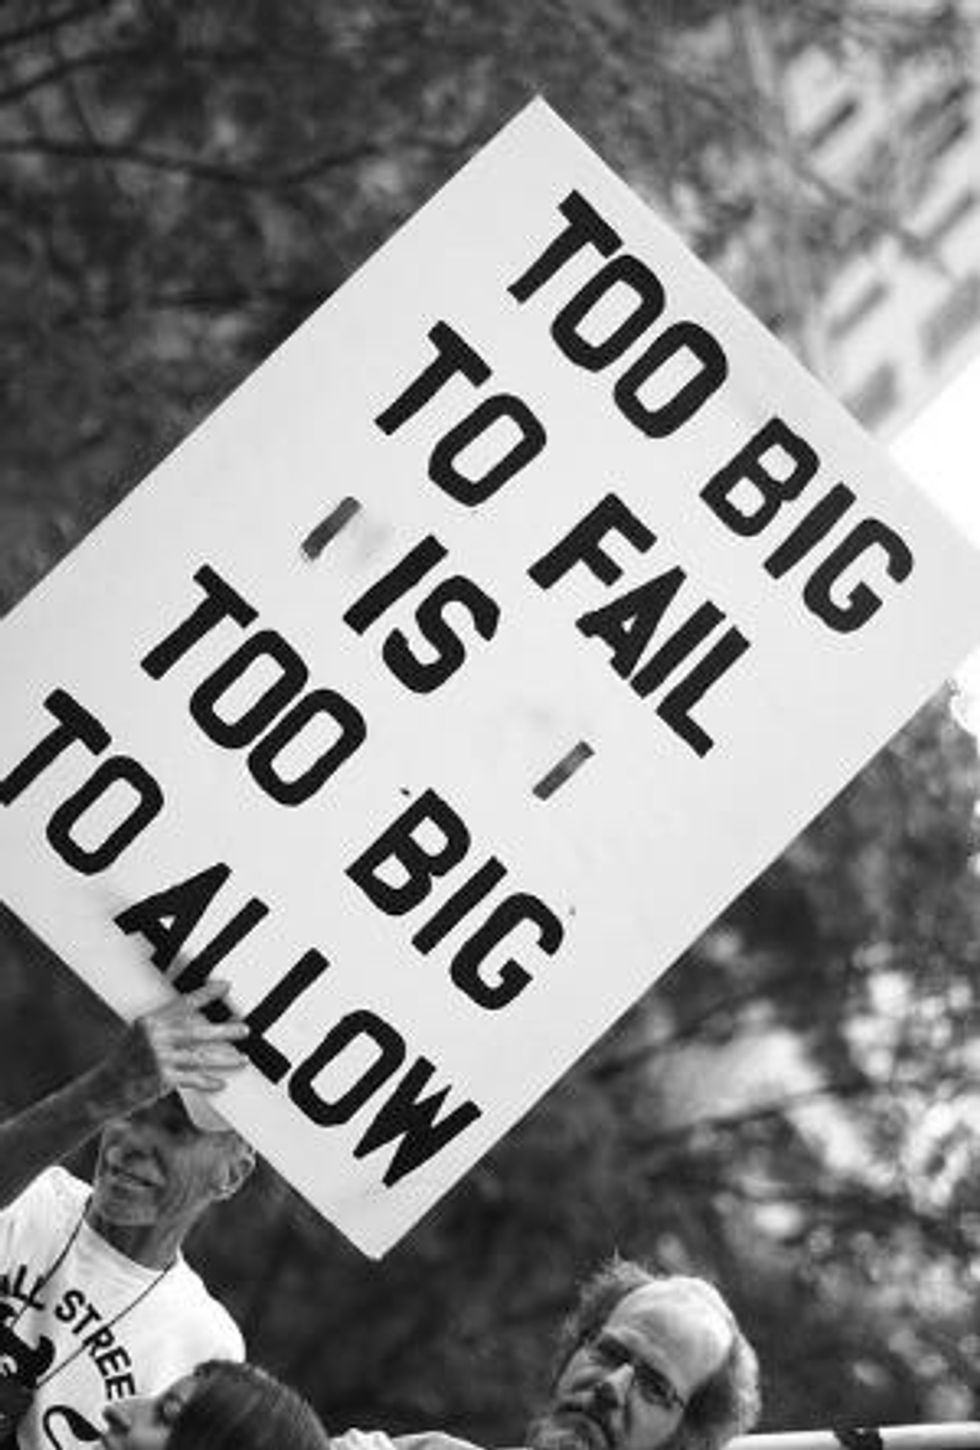
Most liberals in Washington -- President Obama included -- keep hoping the banks can be more tightly controlled but otherwise left as is. That's the theory behind the two-year-old Dodd-Frank law, which Republicans and Wall Street are still working to eviscerate.
Some economists in and around the University of Chicago, who founded the modern conservative tradition, had a surprisingly different take: When it comes to the really big fish in the economic pond, some felt, the only way to preserve competition was to nationalize the largest ones, which defied regulation.
This notion seems counterintuitive: after all, the school's founders provided the intellectual framework for the laissez-faire turn against market regulation over the last half-century. But for them, "bigness" and competition could easily become mutually exclusive. One of the most important Chicago School leaders, Henry C. Simons, judged in 1934 that "the corporation is simply running away with our economic (and political) system."
Simons (a hero of the libertarian idol Milton Friedman) was skeptical of enormity. "Few of our gigantic corporations," he wrote, "can be defended on the ground that their present size is necessary to reasonably full exploitation of production economies."
The central problem, then as now, was that very large corporations could easily undermine regulatory and antitrust strategies. The Nobel laureate George J. Stigler demonstrated how regulation was commonly "designed and operated primarily for" the benefit of the industries involved. And numerous conservatives, including Simons, concluded that large corporate players could thwart antitrust "break-them-up" efforts -- a view Friedman came to share.
Simons did not shrink from the obvious conclusion: "Every industry should be either effectively competitive or socialized." If other remedies were unworkable, "The state should face the necessity of actually taking over, owning, and managing directly" all "industries in which it is impossible to maintain effectively competitive conditions."
At the height of the Depression, eight major economists (including Frank H. Knight) put forward a "Chicago Plan" that called for outright ownership of Federal Reserve Banks, the nationalization of money creation, and the transformation of banks into highly restricted savings-and-loan-like institutions.
To be sure, Simons later revised some of his views, and in the main he and others weren't focused on financial crises. After all, in the mid-20th century, banks were far less concentrated than they are today, when the five biggest -- JPMorgan Chase, Bank of America, Citigroup, Wells Fargo and Goldman Sachs -- dominate the industry, with combined assets amounting to more than half of the nation's economy.
It's also true that not all Chicago School economists (not to mention their descendants) agreed with Simons, especially on the controversial issue of nationalization. But the logic of his argument remains: With high-paid lobbyists contesting every proposed regulation, it is increasingly clear that big banks can never be effectively controlled as private businesses. If an enterprise (or five of them) is so large and so concentrated that competition and regulation are impossible, the most market-friendly step is to nationalize its functions.
What about breaking up the banks, as many on the left favor? Recent history confirms another Chicago School judgment: while a breakup might work in the short term, the most likely course is what happened with Standard Oil and AT&T, which were broken up, only to essentially recombine a few decades later.
Nationalization isn't as difficult as it sounds. We tend to forget that we did, in fact, nationalize General Motors in 2009; the government still owns a controlling share of its stock. We also essentially nationalized the American International Group, one of the largest insurance companies in the world, and the government still owns roughly 60 percent of its stock.
Of course, it would probably take another financial meltdown to make banking nationalization politically tenable. But given how the sector has behaved since the last crisis, a repetition seems inevitable, and sooner rather than later. When it comes, we would do well to keep the work of Henry C. Simons and his acolytes in mind when we contemplate how to rebuild a more equitable economy.
The Barclays interest-rate scandal, HSBC's openness to money laundering by Mexican drug traffickers, the epic blunders at JPMorgan Chase -- at this point, four years after Wall Street wrecked the global economy, does anyone really believe we can regulate the big banks? And if we broke them up, would they really stay broken up?
Most liberals in Washington -- President Obama included -- keep hoping the banks can be more tightly controlled but otherwise left as is. That's the theory behind the two-year-old Dodd-Frank law, which Republicans and Wall Street are still working to eviscerate.
Some economists in and around the University of Chicago, who founded the modern conservative tradition, had a surprisingly different take: When it comes to the really big fish in the economic pond, some felt, the only way to preserve competition was to nationalize the largest ones, which defied regulation.
This notion seems counterintuitive: after all, the school's founders provided the intellectual framework for the laissez-faire turn against market regulation over the last half-century. But for them, "bigness" and competition could easily become mutually exclusive. One of the most important Chicago School leaders, Henry C. Simons, judged in 1934 that "the corporation is simply running away with our economic (and political) system."
Simons (a hero of the libertarian idol Milton Friedman) was skeptical of enormity. "Few of our gigantic corporations," he wrote, "can be defended on the ground that their present size is necessary to reasonably full exploitation of production economies."
The central problem, then as now, was that very large corporations could easily undermine regulatory and antitrust strategies. The Nobel laureate George J. Stigler demonstrated how regulation was commonly "designed and operated primarily for" the benefit of the industries involved. And numerous conservatives, including Simons, concluded that large corporate players could thwart antitrust "break-them-up" efforts -- a view Friedman came to share.
Simons did not shrink from the obvious conclusion: "Every industry should be either effectively competitive or socialized." If other remedies were unworkable, "The state should face the necessity of actually taking over, owning, and managing directly" all "industries in which it is impossible to maintain effectively competitive conditions."
At the height of the Depression, eight major economists (including Frank H. Knight) put forward a "Chicago Plan" that called for outright ownership of Federal Reserve Banks, the nationalization of money creation, and the transformation of banks into highly restricted savings-and-loan-like institutions.
To be sure, Simons later revised some of his views, and in the main he and others weren't focused on financial crises. After all, in the mid-20th century, banks were far less concentrated than they are today, when the five biggest -- JPMorgan Chase, Bank of America, Citigroup, Wells Fargo and Goldman Sachs -- dominate the industry, with combined assets amounting to more than half of the nation's economy.
It's also true that not all Chicago School economists (not to mention their descendants) agreed with Simons, especially on the controversial issue of nationalization. But the logic of his argument remains: With high-paid lobbyists contesting every proposed regulation, it is increasingly clear that big banks can never be effectively controlled as private businesses. If an enterprise (or five of them) is so large and so concentrated that competition and regulation are impossible, the most market-friendly step is to nationalize its functions.
What about breaking up the banks, as many on the left favor? Recent history confirms another Chicago School judgment: while a breakup might work in the short term, the most likely course is what happened with Standard Oil and AT&T, which were broken up, only to essentially recombine a few decades later.
Nationalization isn't as difficult as it sounds. We tend to forget that we did, in fact, nationalize General Motors in 2009; the government still owns a controlling share of its stock. We also essentially nationalized the American International Group, one of the largest insurance companies in the world, and the government still owns roughly 60 percent of its stock.
Of course, it would probably take another financial meltdown to make banking nationalization politically tenable. But given how the sector has behaved since the last crisis, a repetition seems inevitable, and sooner rather than later. When it comes, we would do well to keep the work of Henry C. Simons and his acolytes in mind when we contemplate how to rebuild a more equitable economy.