SUBSCRIBE TO OUR FREE NEWSLETTER
Daily news & progressive opinion—funded by the people, not the corporations—delivered straight to your inbox.
5
#000000
#FFFFFF
To donate by check, phone, or other method, see our More Ways to Give page.
Daily news & progressive opinion—funded by the people, not the corporations—delivered straight to your inbox.
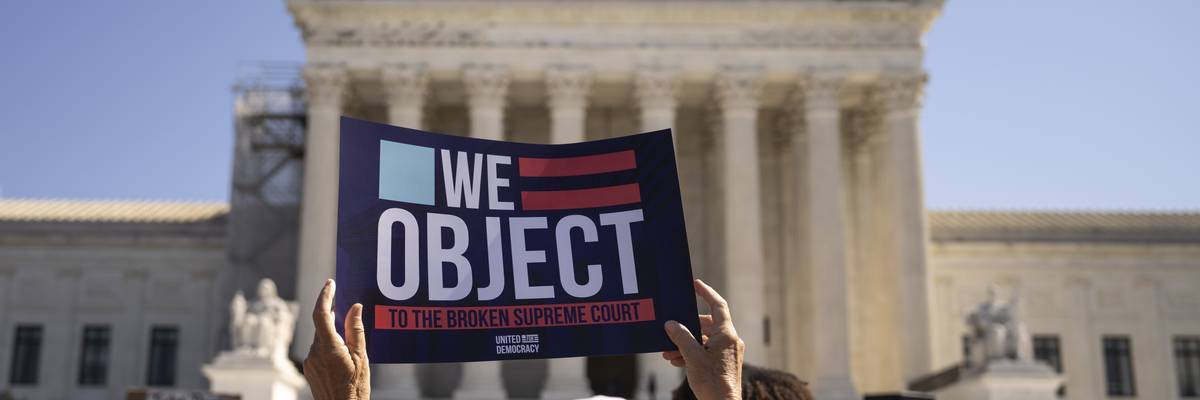
A person holds up a sign reading “We object” in front of the Supreme Court building.
The Moore’s real fight seems to be about progressive tax policies that have not even been enacted, proposals that would finally tax the unrealized capital gains of the extremely wealthy in an adequate way.
On Tuesday, the U.S. Supreme Court will begin hearing oral arguments in Moore vs. United States, which could become the most important tax case in a century. A broad ruling could destabilize our tax system, enrich many profitable corporations, and widen existing economic and racial inequalities.
The case tests whether the plaintiffs, Charles and Kathleen Moore, must pay taxes on their profits as partial owners of a multinational corporation, as required by 2017’s Tax Cuts and Jobs Act. A finding for the plaintiffs could lead the courts to strike down many tax laws that have been in place for decades. Their argument was rejected by other courts, but the Supreme Court nonetheless agreed to hear the case.
The Moores are asking for a ruling that would make it nearly impossible for Congress to tax income that is not “realized,” a term with a hazy definition that generally means a taxpayer has received money or some other type of payment through some transaction. The idea that only “realized” income should be taxed might even seem intuitive to many people who are not aware that such a rule could be used to nullify many provisions in effect today that prevent the wealthy from dodging taxes.
Most of us receive income from a job and pay taxes on that income every year while the richest among us are able shape their income into unrealized gains that are not taxed.
Since the late 1960s, special rules have declared that certain types of income that are easy to shift across borders through paper transactions are taxable when reported by American-owned foreign corporations. The logic employed by the Moores and their allies would call into question these rules, potentially opening the floodgates to offshore tax dodging on a scale never seen before.
There are many other examples of the pandemonium the Moores are inviting. The interest paid on bonds is income subject to tax annually, but what happens if someone tries to avoid this tax by purchasing a bond that pays no interest until it is redeemed after several years? Can the bondholder put off paying tax for years (possibly even forever) by choosing one type of bond over another, even when the income ultimately generated is the same? The tax code has rules that prevent this kind of tax avoidance, but if the Moores convince the Court that income cannot be taxed without realization, these rules may be eventually struck down as well on the same grounds.
Even more alarming are the consequences for “pass-through” businesses, which do not pay the corporate income tax because their profits are “passed through” to the individual owners and reported on their personal income tax returns, even when the profits are not actually paid out to the owners but retained by the business. Lawmakers reasoned that these businesses did not need to pay corporate income tax given that their profits would be subject to personal income tax, but a ruling in favor of the Moores might suggest that they often can be subject to no tax at all.
What motivates the Moores and the right-wing organizations supporting them? Their real fight seems to be about progressive tax policies that have not even been enacted, proposals that would finally tax the unrealized capital gains of the extremely wealthy in an adequate way. These proposals, from President Joe Biden and from some congressional Democrats, could potentially end the special treatment billionaires have long received under our tax system, a result the Moores and their supporters apparently find unacceptable.
A capital gain is generally an increase in the value of an asset. If the owner sells that asset and collects a profit because the asset has appreciated since it was acquired, that profit is considered a realized capital gain. If the owner does not sell the asset, that increase in its value is an unrealized capital gain.
Economists consider both to be income, but tax rules usually only consider realized gains, and not unrealized gains, to be income. As a result, billionaires like Elon Musk and Jeff Bezos can arrange to have most of their income each year in the form of unrealized gains that are not taxed.
All of this may seem mindbogglingly arcane, but the upshot is that most of us receive income from a job and pay taxes on that income every year while the richest among us are able shape their income into unrealized gains that are not taxed. Blowing apart many existing parts of a tax code is a price the plaintiffs seem willing to pay in return for preserving the system that allows the wealthiest to avoid paying taxes in the same way that ordinary Americans do.
This country and this world are at a monumental crossroads. US voters have an opportunity to beat back the forces of fascism and confront the billionaires who are rigging the economy, our media system, and our democracy, making it increasingly impossible for ordinary people to get by. We’re not just talking about the election. We’re talking about what must be done once these fascist elements are vanquished from power. We need a bolder set of solutions than what either major party has so far been willing to offer and a working-class movement ready to fight like hell for it. Trump didn't emerge from nowhere. The conditions that fueled MAGA authoritarianism were created by decades of radical neoliberal economic policies and a corrupt political system dominated by corporate interests. They slashed taxes on the super-rich, promising that the benefits would trickle down. They said giveaways to the corporate titans would make life more affordable for the rest of us. It was all bullshit. And when a bitter, betrayed populace searches for someone to blame, right-wing demagogues have little trouble finding scapegoats. People know when they're being lied to, but you won't hear any of this from the corporate media. Only independent journalism—powered and funded by people who believe in building a better world—can deliver truly trustworthy daily news. If you share our vision, please contribute whatever you can to sustain our work. |
On Tuesday, the U.S. Supreme Court will begin hearing oral arguments in Moore vs. United States, which could become the most important tax case in a century. A broad ruling could destabilize our tax system, enrich many profitable corporations, and widen existing economic and racial inequalities.
The case tests whether the plaintiffs, Charles and Kathleen Moore, must pay taxes on their profits as partial owners of a multinational corporation, as required by 2017’s Tax Cuts and Jobs Act. A finding for the plaintiffs could lead the courts to strike down many tax laws that have been in place for decades. Their argument was rejected by other courts, but the Supreme Court nonetheless agreed to hear the case.
The Moores are asking for a ruling that would make it nearly impossible for Congress to tax income that is not “realized,” a term with a hazy definition that generally means a taxpayer has received money or some other type of payment through some transaction. The idea that only “realized” income should be taxed might even seem intuitive to many people who are not aware that such a rule could be used to nullify many provisions in effect today that prevent the wealthy from dodging taxes.
Most of us receive income from a job and pay taxes on that income every year while the richest among us are able shape their income into unrealized gains that are not taxed.
Since the late 1960s, special rules have declared that certain types of income that are easy to shift across borders through paper transactions are taxable when reported by American-owned foreign corporations. The logic employed by the Moores and their allies would call into question these rules, potentially opening the floodgates to offshore tax dodging on a scale never seen before.
There are many other examples of the pandemonium the Moores are inviting. The interest paid on bonds is income subject to tax annually, but what happens if someone tries to avoid this tax by purchasing a bond that pays no interest until it is redeemed after several years? Can the bondholder put off paying tax for years (possibly even forever) by choosing one type of bond over another, even when the income ultimately generated is the same? The tax code has rules that prevent this kind of tax avoidance, but if the Moores convince the Court that income cannot be taxed without realization, these rules may be eventually struck down as well on the same grounds.
Even more alarming are the consequences for “pass-through” businesses, which do not pay the corporate income tax because their profits are “passed through” to the individual owners and reported on their personal income tax returns, even when the profits are not actually paid out to the owners but retained by the business. Lawmakers reasoned that these businesses did not need to pay corporate income tax given that their profits would be subject to personal income tax, but a ruling in favor of the Moores might suggest that they often can be subject to no tax at all.
What motivates the Moores and the right-wing organizations supporting them? Their real fight seems to be about progressive tax policies that have not even been enacted, proposals that would finally tax the unrealized capital gains of the extremely wealthy in an adequate way. These proposals, from President Joe Biden and from some congressional Democrats, could potentially end the special treatment billionaires have long received under our tax system, a result the Moores and their supporters apparently find unacceptable.
A capital gain is generally an increase in the value of an asset. If the owner sells that asset and collects a profit because the asset has appreciated since it was acquired, that profit is considered a realized capital gain. If the owner does not sell the asset, that increase in its value is an unrealized capital gain.
Economists consider both to be income, but tax rules usually only consider realized gains, and not unrealized gains, to be income. As a result, billionaires like Elon Musk and Jeff Bezos can arrange to have most of their income each year in the form of unrealized gains that are not taxed.
All of this may seem mindbogglingly arcane, but the upshot is that most of us receive income from a job and pay taxes on that income every year while the richest among us are able shape their income into unrealized gains that are not taxed. Blowing apart many existing parts of a tax code is a price the plaintiffs seem willing to pay in return for preserving the system that allows the wealthiest to avoid paying taxes in the same way that ordinary Americans do.
On Tuesday, the U.S. Supreme Court will begin hearing oral arguments in Moore vs. United States, which could become the most important tax case in a century. A broad ruling could destabilize our tax system, enrich many profitable corporations, and widen existing economic and racial inequalities.
The case tests whether the plaintiffs, Charles and Kathleen Moore, must pay taxes on their profits as partial owners of a multinational corporation, as required by 2017’s Tax Cuts and Jobs Act. A finding for the plaintiffs could lead the courts to strike down many tax laws that have been in place for decades. Their argument was rejected by other courts, but the Supreme Court nonetheless agreed to hear the case.
The Moores are asking for a ruling that would make it nearly impossible for Congress to tax income that is not “realized,” a term with a hazy definition that generally means a taxpayer has received money or some other type of payment through some transaction. The idea that only “realized” income should be taxed might even seem intuitive to many people who are not aware that such a rule could be used to nullify many provisions in effect today that prevent the wealthy from dodging taxes.
Most of us receive income from a job and pay taxes on that income every year while the richest among us are able shape their income into unrealized gains that are not taxed.
Since the late 1960s, special rules have declared that certain types of income that are easy to shift across borders through paper transactions are taxable when reported by American-owned foreign corporations. The logic employed by the Moores and their allies would call into question these rules, potentially opening the floodgates to offshore tax dodging on a scale never seen before.
There are many other examples of the pandemonium the Moores are inviting. The interest paid on bonds is income subject to tax annually, but what happens if someone tries to avoid this tax by purchasing a bond that pays no interest until it is redeemed after several years? Can the bondholder put off paying tax for years (possibly even forever) by choosing one type of bond over another, even when the income ultimately generated is the same? The tax code has rules that prevent this kind of tax avoidance, but if the Moores convince the Court that income cannot be taxed without realization, these rules may be eventually struck down as well on the same grounds.
Even more alarming are the consequences for “pass-through” businesses, which do not pay the corporate income tax because their profits are “passed through” to the individual owners and reported on their personal income tax returns, even when the profits are not actually paid out to the owners but retained by the business. Lawmakers reasoned that these businesses did not need to pay corporate income tax given that their profits would be subject to personal income tax, but a ruling in favor of the Moores might suggest that they often can be subject to no tax at all.
What motivates the Moores and the right-wing organizations supporting them? Their real fight seems to be about progressive tax policies that have not even been enacted, proposals that would finally tax the unrealized capital gains of the extremely wealthy in an adequate way. These proposals, from President Joe Biden and from some congressional Democrats, could potentially end the special treatment billionaires have long received under our tax system, a result the Moores and their supporters apparently find unacceptable.
A capital gain is generally an increase in the value of an asset. If the owner sells that asset and collects a profit because the asset has appreciated since it was acquired, that profit is considered a realized capital gain. If the owner does not sell the asset, that increase in its value is an unrealized capital gain.
Economists consider both to be income, but tax rules usually only consider realized gains, and not unrealized gains, to be income. As a result, billionaires like Elon Musk and Jeff Bezos can arrange to have most of their income each year in the form of unrealized gains that are not taxed.
All of this may seem mindbogglingly arcane, but the upshot is that most of us receive income from a job and pay taxes on that income every year while the richest among us are able shape their income into unrealized gains that are not taxed. Blowing apart many existing parts of a tax code is a price the plaintiffs seem willing to pay in return for preserving the system that allows the wealthiest to avoid paying taxes in the same way that ordinary Americans do.