SUBSCRIBE TO OUR FREE NEWSLETTER
Daily news & progressive opinion—funded by the people, not the corporations—delivered straight to your inbox.
5
#000000
#FFFFFF
To donate by check, phone, or other method, see our More Ways to Give page.
Daily news & progressive opinion—funded by the people, not the corporations—delivered straight to your inbox.
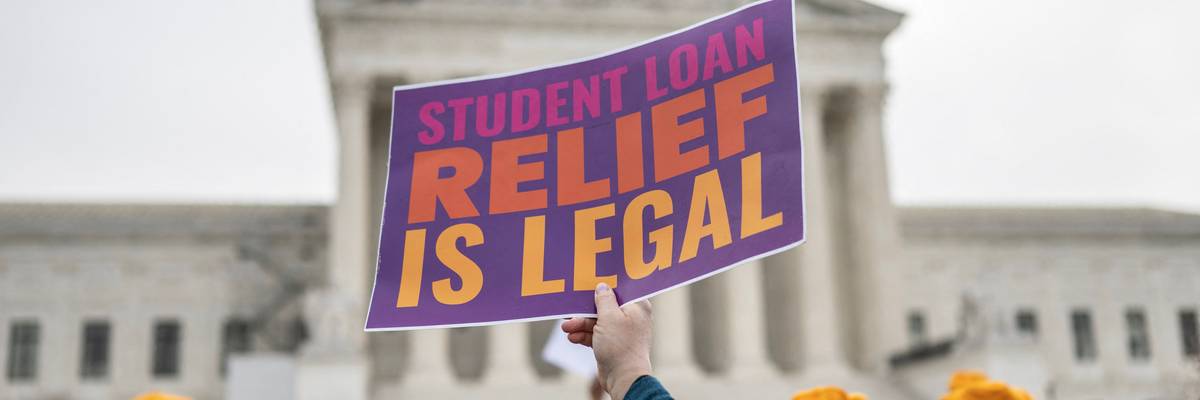
Activists and students protest in front of the Supreme Court during a rally for student debt cancellation in Washington, D.C. on February 28, 2023.
The clock is ticking. Young borrowers must not lose out on urgently-needed debt relief should November bring a new administration.
Exactly one year ago, President Joe Biden stood before the American people after the politicized U.S. Supreme Court ripped away critical student debt relief from 40 million borrowers. The President reaffirmed his commitment to cancel student debt and pledged to use different authority under the Higher Education Act. Since then, President Biden has worked arduously to deliver debt relief to nearly 5 million student loan borrowers by making critical fixes to loan relief programs. But now, in nearly identically timed releases, federal judges in Kansas and Missouri issued a pair of injunctions blocking portions of the new Saving on a Valuable Education repayment plan (the SAVE plan)—making President Biden’s promise of relief more critical than ever.
Biden’s fixes to Public Service Loan Forgiveness and the Income-Driven Repayment Account Adjustment gave millions of borrowers the relief they should have received all along. And this cancellation has been life-changing for the borrowers who have been trapped in the broken student loan system for decades. But one fix that still remains elusive is the crushing burden that student loan debt is putting on our nation's youngest borrowers.
If this rule is pushed to the next Administration, young borrowers may be cut out of relief entirely.
Young people have not had decades to experience runaway interest or pay into the wrong payment plan, but they are being devastated by the student loan crisis nonetheless. For borrowers who are just starting out in their careers, their student debt is inhibiting their ability to start a family, buy a home, save for retirement, or start a business. Student debt is exacerbating racial and economic inequities and widening the racial wealth gap, worsening economic insecurity for people with disabilities, and increasing health disparities and the mental health crisis. And after this week’s rulings, these young borrowers may not even have the benefit of affordable payments and the guarantee of a light at the end of the tunnel.
A recent poll found that at least two-thirds of the youngest voters consider cancelling student loan debt to be an important issue in the upcoming election. It is no wonder why. In fact, younger voters are also far more likely to connect student debt relief with a stronger U.S. economy no matter their political affiliation—even Gen Z and Millennial Republican voters believe action to cancel student debt will help the economy by a 2:1 margin.
And yet, these are the last borrowers to see relief. Earlier this year, a U.S. Department of Education committee held a series of meetings to create a hardship rule for student debt relief. The committee came to consensus on a proposal to provide the Secretary with broad authority and flexibility to cancel debt for borrowers most likely to face difficulties repaying their student loans. It would allow the Secretary to consider a wide-ranging list of factors when considering whether a borrower is experiencing hardship. If enacted, this rule has the potential to unlock economic mobility for millions of young borrowers, workers, and families.
Despite the fact that the committee reached consensus in February, the Administration has yet to publish the proposed rule on hardship. It is no secret that time is running out for the Administration to finish its regulatory agenda. If this rule is pushed to the next Administration, young borrowers may be cut out of relief entirely.
It has been a year since the Supreme Court callously ripped vital relief from tens of millions. Providing relief to young borrowers must be a priority—the Administration cannot allow young student loan borrowers to be a victim of the clock.
This country and this world are at a monumental crossroads. US voters have an opportunity to beat back the forces of fascism and confront the billionaires who are rigging the economy, our media system, and our democracy, making it increasingly impossible for ordinary people to get by. We’re not just talking about the election. We’re talking about what must be done once these fascist elements are vanquished from power. We need a bolder set of solutions than what either major party has so far been willing to offer and a working-class movement ready to fight like hell for it. Trump didn't emerge from nowhere. The conditions that fueled MAGA authoritarianism were created by decades of radical neoliberal economic policies and a corrupt political system dominated by corporate interests. They slashed taxes on the super-rich, promising that the benefits would trickle down. They said giveaways to the corporate titans would make life more affordable for the rest of us. It was all bullshit. And when a bitter, betrayed populace searches for someone to blame, right-wing demagogues have little trouble finding scapegoats. People know when they're being lied to, but you won't hear any of this from the corporate media. Only independent journalism—powered and funded by people who believe in building a better world—can deliver truly trustworthy daily news. If you share our vision, please contribute whatever you can to sustain our work. |
Exactly one year ago, President Joe Biden stood before the American people after the politicized U.S. Supreme Court ripped away critical student debt relief from 40 million borrowers. The President reaffirmed his commitment to cancel student debt and pledged to use different authority under the Higher Education Act. Since then, President Biden has worked arduously to deliver debt relief to nearly 5 million student loan borrowers by making critical fixes to loan relief programs. But now, in nearly identically timed releases, federal judges in Kansas and Missouri issued a pair of injunctions blocking portions of the new Saving on a Valuable Education repayment plan (the SAVE plan)—making President Biden’s promise of relief more critical than ever.
Biden’s fixes to Public Service Loan Forgiveness and the Income-Driven Repayment Account Adjustment gave millions of borrowers the relief they should have received all along. And this cancellation has been life-changing for the borrowers who have been trapped in the broken student loan system for decades. But one fix that still remains elusive is the crushing burden that student loan debt is putting on our nation's youngest borrowers.
If this rule is pushed to the next Administration, young borrowers may be cut out of relief entirely.
Young people have not had decades to experience runaway interest or pay into the wrong payment plan, but they are being devastated by the student loan crisis nonetheless. For borrowers who are just starting out in their careers, their student debt is inhibiting their ability to start a family, buy a home, save for retirement, or start a business. Student debt is exacerbating racial and economic inequities and widening the racial wealth gap, worsening economic insecurity for people with disabilities, and increasing health disparities and the mental health crisis. And after this week’s rulings, these young borrowers may not even have the benefit of affordable payments and the guarantee of a light at the end of the tunnel.
A recent poll found that at least two-thirds of the youngest voters consider cancelling student loan debt to be an important issue in the upcoming election. It is no wonder why. In fact, younger voters are also far more likely to connect student debt relief with a stronger U.S. economy no matter their political affiliation—even Gen Z and Millennial Republican voters believe action to cancel student debt will help the economy by a 2:1 margin.
And yet, these are the last borrowers to see relief. Earlier this year, a U.S. Department of Education committee held a series of meetings to create a hardship rule for student debt relief. The committee came to consensus on a proposal to provide the Secretary with broad authority and flexibility to cancel debt for borrowers most likely to face difficulties repaying their student loans. It would allow the Secretary to consider a wide-ranging list of factors when considering whether a borrower is experiencing hardship. If enacted, this rule has the potential to unlock economic mobility for millions of young borrowers, workers, and families.
Despite the fact that the committee reached consensus in February, the Administration has yet to publish the proposed rule on hardship. It is no secret that time is running out for the Administration to finish its regulatory agenda. If this rule is pushed to the next Administration, young borrowers may be cut out of relief entirely.
It has been a year since the Supreme Court callously ripped vital relief from tens of millions. Providing relief to young borrowers must be a priority—the Administration cannot allow young student loan borrowers to be a victim of the clock.
Exactly one year ago, President Joe Biden stood before the American people after the politicized U.S. Supreme Court ripped away critical student debt relief from 40 million borrowers. The President reaffirmed his commitment to cancel student debt and pledged to use different authority under the Higher Education Act. Since then, President Biden has worked arduously to deliver debt relief to nearly 5 million student loan borrowers by making critical fixes to loan relief programs. But now, in nearly identically timed releases, federal judges in Kansas and Missouri issued a pair of injunctions blocking portions of the new Saving on a Valuable Education repayment plan (the SAVE plan)—making President Biden’s promise of relief more critical than ever.
Biden’s fixes to Public Service Loan Forgiveness and the Income-Driven Repayment Account Adjustment gave millions of borrowers the relief they should have received all along. And this cancellation has been life-changing for the borrowers who have been trapped in the broken student loan system for decades. But one fix that still remains elusive is the crushing burden that student loan debt is putting on our nation's youngest borrowers.
If this rule is pushed to the next Administration, young borrowers may be cut out of relief entirely.
Young people have not had decades to experience runaway interest or pay into the wrong payment plan, but they are being devastated by the student loan crisis nonetheless. For borrowers who are just starting out in their careers, their student debt is inhibiting their ability to start a family, buy a home, save for retirement, or start a business. Student debt is exacerbating racial and economic inequities and widening the racial wealth gap, worsening economic insecurity for people with disabilities, and increasing health disparities and the mental health crisis. And after this week’s rulings, these young borrowers may not even have the benefit of affordable payments and the guarantee of a light at the end of the tunnel.
A recent poll found that at least two-thirds of the youngest voters consider cancelling student loan debt to be an important issue in the upcoming election. It is no wonder why. In fact, younger voters are also far more likely to connect student debt relief with a stronger U.S. economy no matter their political affiliation—even Gen Z and Millennial Republican voters believe action to cancel student debt will help the economy by a 2:1 margin.
And yet, these are the last borrowers to see relief. Earlier this year, a U.S. Department of Education committee held a series of meetings to create a hardship rule for student debt relief. The committee came to consensus on a proposal to provide the Secretary with broad authority and flexibility to cancel debt for borrowers most likely to face difficulties repaying their student loans. It would allow the Secretary to consider a wide-ranging list of factors when considering whether a borrower is experiencing hardship. If enacted, this rule has the potential to unlock economic mobility for millions of young borrowers, workers, and families.
Despite the fact that the committee reached consensus in February, the Administration has yet to publish the proposed rule on hardship. It is no secret that time is running out for the Administration to finish its regulatory agenda. If this rule is pushed to the next Administration, young borrowers may be cut out of relief entirely.
It has been a year since the Supreme Court callously ripped vital relief from tens of millions. Providing relief to young borrowers must be a priority—the Administration cannot allow young student loan borrowers to be a victim of the clock.