SUBSCRIBE TO OUR FREE NEWSLETTER
Daily news & progressive opinion—funded by the people, not the corporations—delivered straight to your inbox.
5
#000000
#FFFFFF
To donate by check, phone, or other method, see our More Ways to Give page.
Daily news & progressive opinion—funded by the people, not the corporations—delivered straight to your inbox.
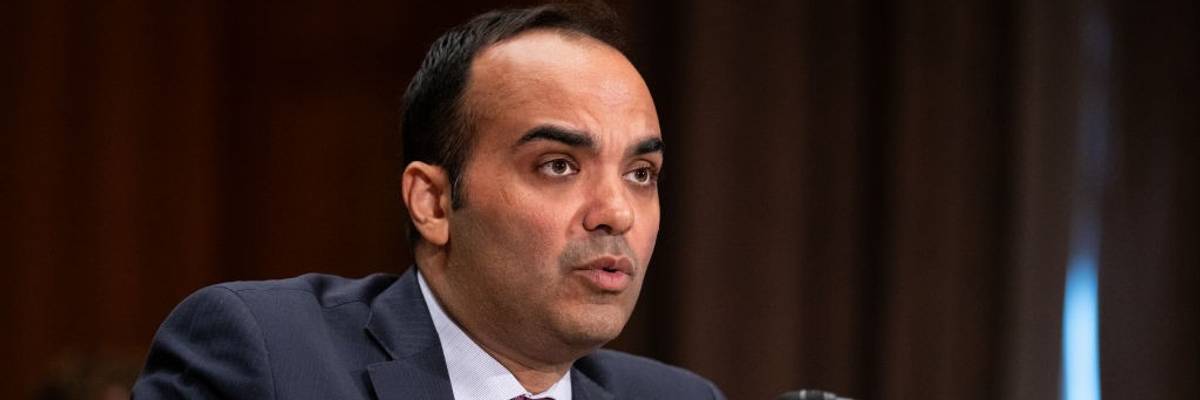
Rohit Chopra, director of the Consumer Financial Protection Bureau, testifies during a Senate Banking, Housing, and Urban Affairs Committee hearing on June 12, 2024.
"If Chopra continues to make life miserable for financial operators and oligarchs—Big Tech has been one of his main concerns—the pressure to dump him will grow," wrote one journalist.
The editorial board of The Wall Street Journal vented its frustration Thursday that Rohit Chopra, the director of the Consumer Financial Protection Bureau, is still in his post at the end of the first week of U.S. President Donald Trump's second White House term.
"Why Is Rohit Chopra Still Employed at the CFPB?" reads the headline of an editorial the Journal published late Thursday, hours after the Chopra-led bureau announced that it is opening a docket for public comment on credit card interest rates and other terms.
"Americans owe well over $1 trillion in credit card debt, and many feel crushed by sky-high interest and fees," Chopra wrote in a social media post Thursday morning.
Morgan Harper, director of policy and advocacy at the American Economic Liberties Project, said in a statement that "the only groups opposing this effort are big banks and credit card companies, which would rather see the agency sit idly by as they rake in excess profits from consumers through fees and interest rates that often surpass 30%."
Chopra was chosen by former President Joe Biden to lead the CFPB, a frequent target of attacks from Republicans and Trump allies, including billionaire Elon Musk. During his first White House stint, Trump attempted to gut the CFPB by installing an opponent of the bureau to lead it.
But while Chopra has packed up his office in Washington, D.C., Trump has yet to fire the CFPB chief—a fact that is reportedly making Wall Street nervous.
"It's just amusing that the time hasn't come yet. Amid all the other wreckage, watching Wall Street squirm a bit is at least a tiny bit of solace."
The Journal's editorial board, a reliable mouthpiece for big business, complained Thursday that Chopra "has spent his tenure advancing progressive hobbyhorses, including rules that ban medical debt on consumer credit reports and cap bank overdraft fees."
The editorial goes on to claim, citing anonymous sources, that Chopra has "sought to ingratiate himself with [Vice President] JD Vance in hopes of serving out his term," which officially ends in October 2026.
News reports suggest that Trump's team has "struggled to make selections to replace" Chopra—a difficulty that one watchdog said is unsurprising.
"Being the hatchet person for the sort of chiselers and grifters that the CFPB fights against is not exactly a fun job—especially as some elements within MAGA could potentially call you out," Jeff Hauser of the Revolving Door Project told The American Prospect.
In a column on Friday, the Prospect's David Dayen wrote that Chopra's continued presence at the helm of the CFPB is "freaking Wall Street out."
"Though it was expected that he would be quickly let go, his office continues to be active," Dayen noted. "On Tuesday, CFPB announced a settlement with Argus Information and Advisory Services, a TransUnion subsidiary, CFPB contractor, and serial violator of several financial and data privacy laws. Argus agreed to not seek any contracts with CFPB for five years. Then on Thursday, CFPB released a report showing growing instances of auto repossessions, well above the pre-pandemic level."
Over the past four years, the Chopra-led CFPB "managed to put over $6 billion back into the pockets of Americans," according to the Consumer Federation of America.
But Dayen wrote that "if Chopra continues to make life miserable for financial operators and oligarchs—Big Tech has been one of his main concerns—the pressure to dump him will grow."
"It's just amusing that the time hasn't come yet," Dayen added. "Amid all the other wreckage, watching Wall Street squirm a bit is at least a tiny bit of solace."
This country and this world are at a monumental crossroads. US voters have an opportunity to beat back the forces of fascism and confront the billionaires who are rigging the economy, our media system, and our democracy, making it increasingly impossible for ordinary people to get by. We’re not just talking about the election. We’re talking about what must be done once these fascist elements are vanquished from power. We need a bolder set of solutions than what either major party has so far been willing to offer and a working-class movement ready to fight like hell for it. Trump didn't emerge from nowhere. The conditions that fueled MAGA authoritarianism were created by decades of radical neoliberal economic policies and a corrupt political system dominated by corporate interests. They slashed taxes on the super-rich, promising that the benefits would trickle down. They said giveaways to the corporate titans would make life more affordable for the rest of us. It was all bullshit. And when a bitter, betrayed populace searches for someone to blame, right-wing demagogues have little trouble finding scapegoats. People know when they're being lied to, but you won't hear any of this from the corporate media. Only independent journalism—powered and funded by people who believe in building a better world—can deliver truly trustworthy daily news. If you share our vision, please contribute whatever you can to sustain our work. |
The editorial board of The Wall Street Journal vented its frustration Thursday that Rohit Chopra, the director of the Consumer Financial Protection Bureau, is still in his post at the end of the first week of U.S. President Donald Trump's second White House term.
"Why Is Rohit Chopra Still Employed at the CFPB?" reads the headline of an editorial the Journal published late Thursday, hours after the Chopra-led bureau announced that it is opening a docket for public comment on credit card interest rates and other terms.
"Americans owe well over $1 trillion in credit card debt, and many feel crushed by sky-high interest and fees," Chopra wrote in a social media post Thursday morning.
Morgan Harper, director of policy and advocacy at the American Economic Liberties Project, said in a statement that "the only groups opposing this effort are big banks and credit card companies, which would rather see the agency sit idly by as they rake in excess profits from consumers through fees and interest rates that often surpass 30%."
Chopra was chosen by former President Joe Biden to lead the CFPB, a frequent target of attacks from Republicans and Trump allies, including billionaire Elon Musk. During his first White House stint, Trump attempted to gut the CFPB by installing an opponent of the bureau to lead it.
But while Chopra has packed up his office in Washington, D.C., Trump has yet to fire the CFPB chief—a fact that is reportedly making Wall Street nervous.
"It's just amusing that the time hasn't come yet. Amid all the other wreckage, watching Wall Street squirm a bit is at least a tiny bit of solace."
The Journal's editorial board, a reliable mouthpiece for big business, complained Thursday that Chopra "has spent his tenure advancing progressive hobbyhorses, including rules that ban medical debt on consumer credit reports and cap bank overdraft fees."
The editorial goes on to claim, citing anonymous sources, that Chopra has "sought to ingratiate himself with [Vice President] JD Vance in hopes of serving out his term," which officially ends in October 2026.
News reports suggest that Trump's team has "struggled to make selections to replace" Chopra—a difficulty that one watchdog said is unsurprising.
"Being the hatchet person for the sort of chiselers and grifters that the CFPB fights against is not exactly a fun job—especially as some elements within MAGA could potentially call you out," Jeff Hauser of the Revolving Door Project told The American Prospect.
In a column on Friday, the Prospect's David Dayen wrote that Chopra's continued presence at the helm of the CFPB is "freaking Wall Street out."
"Though it was expected that he would be quickly let go, his office continues to be active," Dayen noted. "On Tuesday, CFPB announced a settlement with Argus Information and Advisory Services, a TransUnion subsidiary, CFPB contractor, and serial violator of several financial and data privacy laws. Argus agreed to not seek any contracts with CFPB for five years. Then on Thursday, CFPB released a report showing growing instances of auto repossessions, well above the pre-pandemic level."
Over the past four years, the Chopra-led CFPB "managed to put over $6 billion back into the pockets of Americans," according to the Consumer Federation of America.
But Dayen wrote that "if Chopra continues to make life miserable for financial operators and oligarchs—Big Tech has been one of his main concerns—the pressure to dump him will grow."
"It's just amusing that the time hasn't come yet," Dayen added. "Amid all the other wreckage, watching Wall Street squirm a bit is at least a tiny bit of solace."
The editorial board of The Wall Street Journal vented its frustration Thursday that Rohit Chopra, the director of the Consumer Financial Protection Bureau, is still in his post at the end of the first week of U.S. President Donald Trump's second White House term.
"Why Is Rohit Chopra Still Employed at the CFPB?" reads the headline of an editorial the Journal published late Thursday, hours after the Chopra-led bureau announced that it is opening a docket for public comment on credit card interest rates and other terms.
"Americans owe well over $1 trillion in credit card debt, and many feel crushed by sky-high interest and fees," Chopra wrote in a social media post Thursday morning.
Morgan Harper, director of policy and advocacy at the American Economic Liberties Project, said in a statement that "the only groups opposing this effort are big banks and credit card companies, which would rather see the agency sit idly by as they rake in excess profits from consumers through fees and interest rates that often surpass 30%."
Chopra was chosen by former President Joe Biden to lead the CFPB, a frequent target of attacks from Republicans and Trump allies, including billionaire Elon Musk. During his first White House stint, Trump attempted to gut the CFPB by installing an opponent of the bureau to lead it.
But while Chopra has packed up his office in Washington, D.C., Trump has yet to fire the CFPB chief—a fact that is reportedly making Wall Street nervous.
"It's just amusing that the time hasn't come yet. Amid all the other wreckage, watching Wall Street squirm a bit is at least a tiny bit of solace."
The Journal's editorial board, a reliable mouthpiece for big business, complained Thursday that Chopra "has spent his tenure advancing progressive hobbyhorses, including rules that ban medical debt on consumer credit reports and cap bank overdraft fees."
The editorial goes on to claim, citing anonymous sources, that Chopra has "sought to ingratiate himself with [Vice President] JD Vance in hopes of serving out his term," which officially ends in October 2026.
News reports suggest that Trump's team has "struggled to make selections to replace" Chopra—a difficulty that one watchdog said is unsurprising.
"Being the hatchet person for the sort of chiselers and grifters that the CFPB fights against is not exactly a fun job—especially as some elements within MAGA could potentially call you out," Jeff Hauser of the Revolving Door Project told The American Prospect.
In a column on Friday, the Prospect's David Dayen wrote that Chopra's continued presence at the helm of the CFPB is "freaking Wall Street out."
"Though it was expected that he would be quickly let go, his office continues to be active," Dayen noted. "On Tuesday, CFPB announced a settlement with Argus Information and Advisory Services, a TransUnion subsidiary, CFPB contractor, and serial violator of several financial and data privacy laws. Argus agreed to not seek any contracts with CFPB for five years. Then on Thursday, CFPB released a report showing growing instances of auto repossessions, well above the pre-pandemic level."
Over the past four years, the Chopra-led CFPB "managed to put over $6 billion back into the pockets of Americans," according to the Consumer Federation of America.
But Dayen wrote that "if Chopra continues to make life miserable for financial operators and oligarchs—Big Tech has been one of his main concerns—the pressure to dump him will grow."
"It's just amusing that the time hasn't come yet," Dayen added. "Amid all the other wreckage, watching Wall Street squirm a bit is at least a tiny bit of solace."