

SUBSCRIBE TO OUR FREE NEWSLETTER
Daily news & progressive opinion—funded by the people, not the corporations—delivered straight to your inbox.
5
#000000
#FFFFFF
To donate by check, phone, or other method, see our More Ways to Give page.
Daily news & progressive opinion—funded by the people, not the corporations—delivered straight to your inbox.
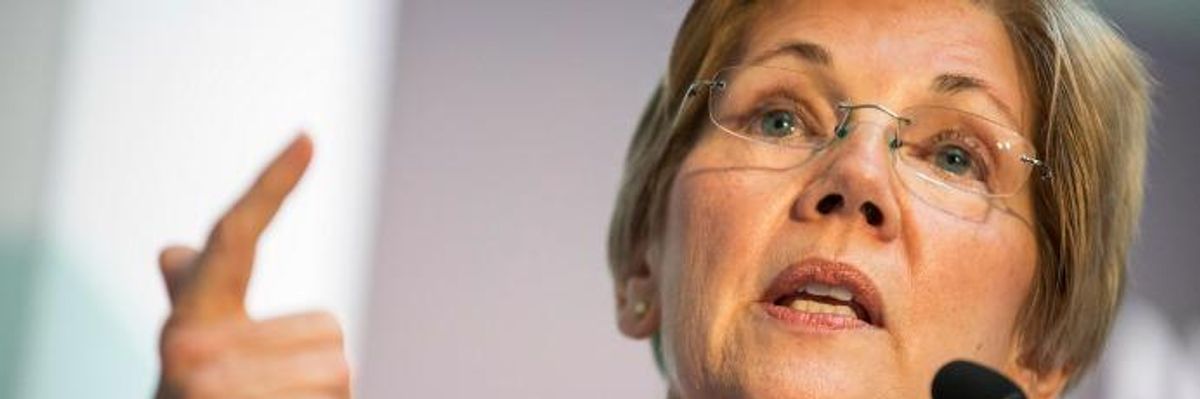
Consumer Financial Protection Bureau architect Sen. Elizabeth Warren (D-Mass.), seen here in 2016, said the new rule from the agency "will allow working families to hold big banks accountable when they're cheated." (Photo: New America/flickr/cc)
A new rule by a federal watchdog--hailed as having "paramount importance" for protecting consumers from Wall Street predators and curbing corporate abuses--is under direct attack by Republicans just days after being issued.
The rule from the successful and broadly-supported Consumer Financial Protection Bureau (CFPB) bans companies from using mandatory arbitration clauses, which makes consumers give up their right to file or join class-action lawsuits. In other words, it blocks "rip-off clauses" that are "a fine-print trick that banks and predatory lenders use to evade accountability and conceal illegal behavior," as advocacy group Public Citizen put it, noting that they are also used by many corporations.
As the CFPB outlines,
No matter how many people are harmed by the same conduct, most arbitration clauses require people to bring claims individually against the company, outside the court system, before a private individual (an arbitrator). Companies know that people almost never spend the time or money to pursue relief when the amounts at stake are small, so few people do this.
In being able to stop group lawsuits, making people "go it alone or give up," companies can deny consumers their day in court; avoid paying out big refunds; and continue harmful practices, the agency states.
"By prohibiting class actions," the Economic Policy Institute's Celine McNicholas writes, "companies have dramatically reduced consumer challenges to predatory practices."
Announcement of the new rule on Monday drew praise from consumer advocacy as well as U.S. Senator Elizabeth Warren (D-Mass.), who helped create the agency in the aftermath of the 2008 financial crisis as part of the Dodd-Frank Wall Street Reform and Consumer Protection Act.
Warren, for her part, said the new rule "will allow working families to hold big banks accountable when they're cheated and help discourage the kinds of surprise fees that consumers hate." Dennis Kelleher, president and CEO of Better Markets, said it marked "a good day for investor and consumer protection."
"Over the past decade," added Lisa Gilbert, vice president of legislative affairs for Public Citizen, "large corporations have turned fine-print clauses buried deep in their contracts into a license to steal from American consumers and cover up the evidence. The CFPB rule will right this egregious wrong by restoring consumers' ability to enforce their most basic rights and protections in court."
And according to Vanita Gupta, president and CEO of The Leadership Conference on Civil and Human Rights, the rule marks "yet another example of how the CFPB is living up to its mandate--to put the concerns and welfare of the consumer above those of corporations that too often seek to take advantage of them."
The agency, however, has been in the cross-hairs of Republicans since its inception, and its latest action drew swift rebuke from GOP lawmakers who vowed to kill it.
In a statement issued Tuesday, U.S. Sen. Tom Cotton of Arkansas accused the agency of having "gone rogue again, abusing its power in a particularly harmful way."
Cotton said he started the process of getting rid of the rule through the Congressional Review Act--a "sneaky tactic" that's been "gleefully employed" by the current House GOP, which allows Congress to get rid of rules put in place during the final six months of the previous administration.
And Cotton's not alone.
Sen. Mike Crapo (R-Idaho), chair of the Senate Banking Committee and committed foe of the CFPB, also said Tuesday he'd pursue a similar path. He argued: "Driving dispute resolutions into class actions is probably harmful to consumers rather than helpful to consumers."
Also slamming the rule was Financial Services Committee Chairman Jeb Hensarling of Texas, who called it "anti-consumer" and urged Congress to "fundamentally refor[m] the CFPB and dismantl[e] the Administrative State."
Referring to Cotton's resolution, Robert Weissman, president of Public Citizen, said the Arkansas Republican "is making clear which side he's on: the banks that want to predate; the payday lenders that want to fleece; the credit card companies that want to defraud; in short, the financial industry that spends hundreds of millions every year on lobbying and campaign contributions."
"And he's making very clear who he's standing against: American consumers who are routinely victimized by these very financial corporations," Weissman said.
This country and this world are at a monumental crossroads. US voters have an opportunity to beat back the forces of fascism and confront the billionaires who are rigging the economy, our media system, and our democracy, making it increasingly impossible for ordinary people to get by. We’re not just talking about the election. We’re talking about what must be done once these fascist elements are vanquished from power. We need a bolder set of solutions than what either major party has so far been willing to offer and a working-class movement ready to fight like hell for it. Trump didn't emerge from nowhere. The conditions that fueled MAGA authoritarianism were created by decades of radical neoliberal economic policies and a corrupt political system dominated by corporate interests. They slashed taxes on the super-rich, promising that the benefits would trickle down. They said giveaways to the corporate titans would make life more affordable for the rest of us. It was all bullshit. And when a bitter, betrayed populace searches for someone to blame, right-wing demagogues have little trouble finding scapegoats. People know when they're being lied to, but you won't hear any of this from the corporate media. Only independent journalism—powered and funded by people who believe in building a better world—can deliver truly trustworthy daily news. If you share our vision, please contribute whatever you can to sustain our work. |
A new rule by a federal watchdog--hailed as having "paramount importance" for protecting consumers from Wall Street predators and curbing corporate abuses--is under direct attack by Republicans just days after being issued.
The rule from the successful and broadly-supported Consumer Financial Protection Bureau (CFPB) bans companies from using mandatory arbitration clauses, which makes consumers give up their right to file or join class-action lawsuits. In other words, it blocks "rip-off clauses" that are "a fine-print trick that banks and predatory lenders use to evade accountability and conceal illegal behavior," as advocacy group Public Citizen put it, noting that they are also used by many corporations.
As the CFPB outlines,
No matter how many people are harmed by the same conduct, most arbitration clauses require people to bring claims individually against the company, outside the court system, before a private individual (an arbitrator). Companies know that people almost never spend the time or money to pursue relief when the amounts at stake are small, so few people do this.
In being able to stop group lawsuits, making people "go it alone or give up," companies can deny consumers their day in court; avoid paying out big refunds; and continue harmful practices, the agency states.
"By prohibiting class actions," the Economic Policy Institute's Celine McNicholas writes, "companies have dramatically reduced consumer challenges to predatory practices."
Announcement of the new rule on Monday drew praise from consumer advocacy as well as U.S. Senator Elizabeth Warren (D-Mass.), who helped create the agency in the aftermath of the 2008 financial crisis as part of the Dodd-Frank Wall Street Reform and Consumer Protection Act.
Warren, for her part, said the new rule "will allow working families to hold big banks accountable when they're cheated and help discourage the kinds of surprise fees that consumers hate." Dennis Kelleher, president and CEO of Better Markets, said it marked "a good day for investor and consumer protection."
"Over the past decade," added Lisa Gilbert, vice president of legislative affairs for Public Citizen, "large corporations have turned fine-print clauses buried deep in their contracts into a license to steal from American consumers and cover up the evidence. The CFPB rule will right this egregious wrong by restoring consumers' ability to enforce their most basic rights and protections in court."
And according to Vanita Gupta, president and CEO of The Leadership Conference on Civil and Human Rights, the rule marks "yet another example of how the CFPB is living up to its mandate--to put the concerns and welfare of the consumer above those of corporations that too often seek to take advantage of them."
The agency, however, has been in the cross-hairs of Republicans since its inception, and its latest action drew swift rebuke from GOP lawmakers who vowed to kill it.
In a statement issued Tuesday, U.S. Sen. Tom Cotton of Arkansas accused the agency of having "gone rogue again, abusing its power in a particularly harmful way."
Cotton said he started the process of getting rid of the rule through the Congressional Review Act--a "sneaky tactic" that's been "gleefully employed" by the current House GOP, which allows Congress to get rid of rules put in place during the final six months of the previous administration.
And Cotton's not alone.
Sen. Mike Crapo (R-Idaho), chair of the Senate Banking Committee and committed foe of the CFPB, also said Tuesday he'd pursue a similar path. He argued: "Driving dispute resolutions into class actions is probably harmful to consumers rather than helpful to consumers."
Also slamming the rule was Financial Services Committee Chairman Jeb Hensarling of Texas, who called it "anti-consumer" and urged Congress to "fundamentally refor[m] the CFPB and dismantl[e] the Administrative State."
Referring to Cotton's resolution, Robert Weissman, president of Public Citizen, said the Arkansas Republican "is making clear which side he's on: the banks that want to predate; the payday lenders that want to fleece; the credit card companies that want to defraud; in short, the financial industry that spends hundreds of millions every year on lobbying and campaign contributions."
"And he's making very clear who he's standing against: American consumers who are routinely victimized by these very financial corporations," Weissman said.
A new rule by a federal watchdog--hailed as having "paramount importance" for protecting consumers from Wall Street predators and curbing corporate abuses--is under direct attack by Republicans just days after being issued.
The rule from the successful and broadly-supported Consumer Financial Protection Bureau (CFPB) bans companies from using mandatory arbitration clauses, which makes consumers give up their right to file or join class-action lawsuits. In other words, it blocks "rip-off clauses" that are "a fine-print trick that banks and predatory lenders use to evade accountability and conceal illegal behavior," as advocacy group Public Citizen put it, noting that they are also used by many corporations.
As the CFPB outlines,
No matter how many people are harmed by the same conduct, most arbitration clauses require people to bring claims individually against the company, outside the court system, before a private individual (an arbitrator). Companies know that people almost never spend the time or money to pursue relief when the amounts at stake are small, so few people do this.
In being able to stop group lawsuits, making people "go it alone or give up," companies can deny consumers their day in court; avoid paying out big refunds; and continue harmful practices, the agency states.
"By prohibiting class actions," the Economic Policy Institute's Celine McNicholas writes, "companies have dramatically reduced consumer challenges to predatory practices."
Announcement of the new rule on Monday drew praise from consumer advocacy as well as U.S. Senator Elizabeth Warren (D-Mass.), who helped create the agency in the aftermath of the 2008 financial crisis as part of the Dodd-Frank Wall Street Reform and Consumer Protection Act.
Warren, for her part, said the new rule "will allow working families to hold big banks accountable when they're cheated and help discourage the kinds of surprise fees that consumers hate." Dennis Kelleher, president and CEO of Better Markets, said it marked "a good day for investor and consumer protection."
"Over the past decade," added Lisa Gilbert, vice president of legislative affairs for Public Citizen, "large corporations have turned fine-print clauses buried deep in their contracts into a license to steal from American consumers and cover up the evidence. The CFPB rule will right this egregious wrong by restoring consumers' ability to enforce their most basic rights and protections in court."
And according to Vanita Gupta, president and CEO of The Leadership Conference on Civil and Human Rights, the rule marks "yet another example of how the CFPB is living up to its mandate--to put the concerns and welfare of the consumer above those of corporations that too often seek to take advantage of them."
The agency, however, has been in the cross-hairs of Republicans since its inception, and its latest action drew swift rebuke from GOP lawmakers who vowed to kill it.
In a statement issued Tuesday, U.S. Sen. Tom Cotton of Arkansas accused the agency of having "gone rogue again, abusing its power in a particularly harmful way."
Cotton said he started the process of getting rid of the rule through the Congressional Review Act--a "sneaky tactic" that's been "gleefully employed" by the current House GOP, which allows Congress to get rid of rules put in place during the final six months of the previous administration.
And Cotton's not alone.
Sen. Mike Crapo (R-Idaho), chair of the Senate Banking Committee and committed foe of the CFPB, also said Tuesday he'd pursue a similar path. He argued: "Driving dispute resolutions into class actions is probably harmful to consumers rather than helpful to consumers."
Also slamming the rule was Financial Services Committee Chairman Jeb Hensarling of Texas, who called it "anti-consumer" and urged Congress to "fundamentally refor[m] the CFPB and dismantl[e] the Administrative State."
Referring to Cotton's resolution, Robert Weissman, president of Public Citizen, said the Arkansas Republican "is making clear which side he's on: the banks that want to predate; the payday lenders that want to fleece; the credit card companies that want to defraud; in short, the financial industry that spends hundreds of millions every year on lobbying and campaign contributions."
"And he's making very clear who he's standing against: American consumers who are routinely victimized by these very financial corporations," Weissman said.

