
5
#000000
#FFFFFF
To donate by check, phone, or other method, see our More Ways to Give page.
Daily news & progressive opinion—funded by the people, not the corporations—delivered straight to your inbox.
"While President Trump and congressional Republicans promised to lower prices, their actions instead sent prices soaring," said Democratic US Sen. Maggie Hassan.
Democrats on the congressional Joint Economic Committee on Thursday published updated data estimating that President Donald Trump's policies have cost the average US family $4,700 during the first two years of his second term.
One major driver of price increases has been Trump's illegal war with Iran, which led to a global spike in energy prices after Iran shut down the Strait of Hormuz in retaliation for military strikes Trump launched without congressional authorization in February.
In total, the JEC found that Americans have spent $101 billion more on gas since the start of the war, which it calculated cost the average US family an additional $856.
The JEC report also highlights the massive rise in insurance premiums thanks to Trump and Republicans' refusal to extend enhanced subsidies for people who buy health coverage through exchanges established by the Affordable Care Act.
"Monthly premiums for ACA plans rose over 50% on average in 2026 compared to last year," JEC wrote. "Meanwhile deductibles surged to record highs, increasing by more than $1,000 on average."
And although Trump vowed to lower the cost of food starting on his first day in office, the report finds the average US family had to pay $310 more for groceries than in 2024.
"Beef and coffee prices are hitting Americans especially hard," the report notes. "Since the president took office, the average price of ground beef has risen almost every month to a record high of more than $7 per pound. Coffee prices also spiked and are now more than $9 per pound."
Sen. Maggie Hassan (D-NH), ranking member of the committee, said the new data is a damning indictment of Trump and the GOP's management of the economy.
"While President Trump and congressional Republicans promised to lower prices, their actions instead sent prices soaring," said Hassan. "Trump’s reckless tariffs and Iran War continue to make things harder every day for Granite Staters and Americans across the country."
Data released by the US Bureau of Labor Statistics (BLS) on Thursday indicated that the affordability crisis in the US appears to be getting even worse.
According to the BLS' latest Producer Price Index, wholesale prices paid by businesses increased by an annual rate of 6.3% in September, which was far higher than economists' forecast of a 5.5% increase.
The biggest factor in increased wholesale costs in September was the price of energy, which posted a monthly increase of 10.8%, reflecting record-high prices for diesel fuel used to ship goods across the country.
PPI is seen as an important gauge of future inflation for consumers, as companies typically pass the costs they pay for inputs onto shoppers in the form of price increases.
"Social Security’s future is on the ballot this November," said one advocate, "and that includes the size of annual COLA adjustments.“
The rising cost of healthcare and other essentials means that the modest cost-of-living adjustment for about 76 million Social Security beneficiaries, announced Wednesday by Social Security Administrator Frank Bisignano, is likely to make only a small difference for senior citizens struggling to afford gasoline and groceries, said economic justice advocates.
Bisignano said the COLA for 2027, effective in January for most beneficiaries, will be 3.6%, amounting to an average of about $75 more per month.
Along with senior citizens, 40% of whom rely on Social Security for at least half their income, about 7.3 million people with disabilities who receive Supplemental Security Income will also receive the COLA increase starting December 31.
The COLA is higher than last year's, when the SSA adjusted monthly earned benefits by 2.8%.
But Richard Fiesta, executive director of the Alliance for Retired Americans, said the new increase "is just not enough to keep up with the cost of food, gas, utilities, and prescription drugs."
"A good chunk" of increased Social Security payments "will be wiped out" by higher premiums for Medicare Part B, which covers medically necessary and preventive healthcare services, said Fiesta. Those premiums are projected to rise to $209.50 per month in January, up from $202.90 per month this year.
Medicare Part D prescription drug plans are also expected to see increased premiums next year, while Social Security beneficiaries, like other Americans, will likely be impacted by continued inflation driven by President Donald Trump's illegal war on Iran and his tariff policy.
Social Security recipients are aware of the limits of the COLA, a poll released Monday by the AARP showed. Seventy-six percent of respondents said a 3.5% COLA would not keep up with rising prices they are facing at the grocery store, gas station, and pharmacy.
Fiesta called on billionaires and the wealthiest 1% of Americans to "pay their fair share" to make it possible to "boost benefits for everyone, implement a COLA that reflects the cost of things older Americans spend money on, and guarantee the program’s solvency for future generations."
While most American workers pay into Social Security year-round, millionaires in the US stop paying into the program just two months into the year because the payroll tax does not apply to income over a certain level. Some of the richest Americans, like Tesla CEO Elon Musk, pay very little into the crucial anti-poverty program by earning most of their money through investments rather than income.
"In just three weeks, older Americans will have an opportunity to elect members of Congress who will make strengthening Social Security a priority. The future of our earned benefits is on the ballot.”
“Strengthening and expanding Social Security must be a national priority," said Fiesta. "It’s time for clear and decisive action. In just three weeks, older Americans will have an opportunity to elect members of Congress who will make strengthening Social Security a priority. The future of our earned benefits is on the ballot.”
At Social Security Works (SSW), which advocates for strengthening the program and regularly debunks myths from the Republican Party claiming that Social Security is unaffordable for the country, Nancy Altman said the COLA increase "will help" some seniors, "but it doesn’t fully account for the costs that Social Security beneficiaries face."
"The Trump administration’s war of choice with Iran and tariff chaos have driven gasoline prices up nearly 40 percent, and caused grocery costs to skyrocket," said Altman, president of SSW.
Part of the problem, said Altman, is the SSA's use of the Consumer Price Index for Urban Wage Earners and Clerical Workers (CPI-W), which measures price changes for goods purchased by working families, to determine the annual COLA.
SSW has called for the use of the Consumer Price Index for the Elderly (CPI-E) to better reflect how Social Security recipients spend their money.
Meanwhile, Altman said, Republicans including House Speaker Mike Johnson (R-La.) have proposed calculating the COLA using the chained Consumer Price Index (CPI), which would “substantially lower benefits over time," according to an AARP analysis.
“That’s a cut to the American people’s hard-earned benefits," said Altman. "Over time, switching to the chained CPI, as the Republicans have proposed, would shrink yearly benefits by hundreds and even thousands of dollars. Switching to the CPI-E, as the Democrats propose, would increase benefits. This would particularly impact women and Hispanics, who have longer average life expectancies."
She noted that US senators elected in November will have a say in whether Social Security remains fully funded through their six-year terms—and urged Americans to vote accordingly.
In 2032, said Altman, "Social Security is projected to face a funding shortfall. The vast majority of Republicans refuse to support a single penny in revenue increases, even from the ultra-wealthy, to address the shortfall. That leaves benefit cuts, including less generous COLAs, as their only option."
"The bottom line: Social Security’s future is on the ballot this November," she said, "and that includes the size of annual COLA adjustments.“
"Real wages are falling, and have been falling for months," said one economist.
Data released by the US Bureau of Labor Statistics on Wednesday showed inflation grew faster than expected in September, driven in large part by costs related to President Donald Trump's illegal war with Iran.
The latest Consumer Price Index (CPI) report showed overall prices in September posted a yearly increase of 3.7%, marking the biggest rise in prices since May.
The main drivers of inflation in September were related to energy, which has surged in cost since Iran shut down the Strait of Hormuz earlier this year in retaliation for Trump's unlawful attack in February.
Energy prices increased by an annual rate of 20% in September, with the price of gasoline growing by an annual rate of 34% and the price of fuel oil growing by an annual rate of 74%.
University of Michigan economist Justin Wolfers noted in a Wednesday social media post that average wages are not keeping up with the rate of inflation, meaning workers have seen their purchasing power decrease.
"Real wages are falling," Wolfers wrote, "and have been falling for months."
Jared Bernstein, a senior fellow at the Center for American Progress and who served as chair of the Council of Economic Advisers under former President Joe Biden, said the September data showed that "working families are getting squeezed on both sides (wage, price) of the affordability crunch," as workers' inflation-adjusted earnings are now back to where they were at the start of Trump's second term.
Bernstein's observations were echoed by Heather Long, chief economist at Navy Federal Credit Union, who pointed out that "inflation has nearly wiped out all wage gains since January 2025."
"This is a very different picture from President Trump's first term when wages were up over 15%, well above about 8% inflation," Long added. "It helps explain the frustration many households feel right now with the economy."
Sen. Andy Kim (D-NJ) said that accelerating inflation was yet another sign of Republicans' governing failures.
"Trump and Republicans have no answer for rising inflation caused by soaring gas prices and the war in Iran," Kim wrote. "They're more focused on enriching Trump and his friends and family. This is why we're fighting to take back Congress so we can end the war and bring prices down for you and your family."
Alex Jacquez, senior vice president of policy, advocacy, and research at Groundwork Collaborative, said the CPI report shows why "Americans have lost faith in Trump’s economy."
"The president has repeatedly made promises he can’t keep," Jacquez said, "and despite the band-aid attempts from the White House, there is a gaping hole in our economy just weeks from the midterms. Between the president’s war in Iran and reckless tariffs, his economy is on life support."
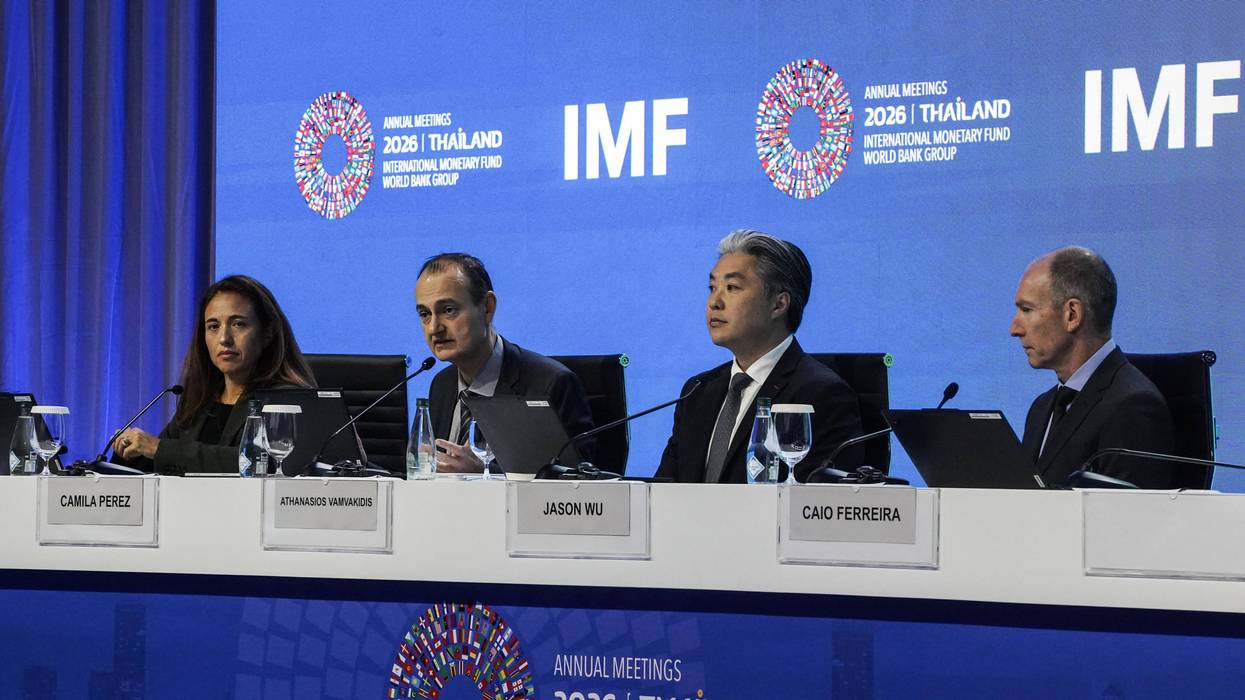
"Instead of helping countries withstand another major shock," Oxfam's executive director said, the IMF "is forcing them to cut back on the very spending that can help protect people and recover."
The US-Israeli war with Iran has exacerbated economic hardship across the world. It's especially bad for the developing nations currently being forced to implement austerity programs by the International Monetary Fund.
Under IMF loan programs, countries struggling with debt are required to reduce government budget deficits by introducing spending cuts and tax increases that tend to hurt their poorest citizens. They often include cuts to public services and welfare programs, caps on government workers' salaries, and the elimination of subsidies that keep basic needs affordable.
According to a report out Monday from Oxfam—amid the IMF's annual meeting in Bangkok this week—24 of the 28 nations currently receiving IMF loans have been forced to implement austerity measures. Some of them, like Sierra Leone and Guinea-Bissau, are among the poorest nations in the world.
Even before the war—which has caused oil prices to soar and driven inflation worldwide—people in many of these countries were struggling to meet their basic needs and facing severe economic pressure: 51% were food insecure, and 57% lacked access to clean cooking fuel.
Emergency government programs have been able to backstop the worst effects for up to 130 million of the world's poorest people, according to a report published before the meeting by the United Nations Development Program.
But as those countries run out of resources, many are being forced to pivot, and the stiff requirements imposed by the IMF may exacerbate the hardship.
In Ecuador and Guinea-Bissau, the IMF is requiring governments to cut spending, raise taxes, or both to the equivalent of roughly 4% of the nations' annual gross domestic product (GDP).
The terms are even harsher for Sierra Leone, where the government is required to cut spending or raise costs equivalent to more than five times its annual healthcare budget.
A loan approved last week for Bolivia requires the government to slash as much as 8.5% of its GDP from the deficit—about twice its annual healthcare spending. The country has already been forced to eliminate a diesel subsidy that drove high prices down for consumers and businesses.
The IMF has acknowledged that these cuts are likely to make the strain worse for many low-income countries already suffering from the war, but said they had "no choice" but to cut spending or restructure their debts.
Oxfam International executive director Amitabh Behar noted that during previous crises like the Covid-19 pandemic and the war in Ukraine, the IMF has enacted tools to ease the burden on nations in debt by providing emergency loans and access to foreign currency without requiring additional borrowing.
"But this time, the fund is taking a very different path," he said. "Instead of helping countries withstand another major shock, it is doubling down on austerity—forcing them to cut back on the very spending that can help protect people and recover—and leaving them even more vulnerable to the next crisis."
"If we don’t see the massive gains in productivity promised by the AI enthusiasts, then we will almost certainly see a collapse in the stock market," said one economist.
The International Monetary Fund warned Tuesday that the global economy faces serious risks from Big Tech firms taking on massive debt to fund the buildout of artificial intelligence data centers worldwide.
The IMF's latest Global Financial Stability Report outlines a number of risks to economic growth in the coming years, including a reliance on AI industry spending that it warns could lead to a new financial crisis.
The report points to the methods the world's largest data center operators, known as hyperscalers, are using to fund new construction as particularly troubling.
"Hyperscalers have strong earnings from their core businesses," the report states. "Yet, free cash flows are rapidly declining as hyperscalers try to sustain large AI investment needs, leaving debt financing increasingly necessary."
The analysis also details the role played by so-called circular financing agreements, in which one company agrees to fund another company's AI project in exchange for the firm receiving the money buying the investing firm's products.
These arrangements could create dangerous interdependence within the industry that could spark a financial contagion if one of the firms goes belly up, according to the report.
"While investors... are generally financially sound, distress at key investee firms could present significant 'wrong-way risk' to the AI ecosystem," the report states. "Equity and debt investments in the firms depreciate in value precisely when future revenue streams tied to them are impaired."
Investment expert Bret Jensen, in an analysis published by Seeking Alpha on Tuesday, examined projected capital expenditures from the five biggest hyperscalers—Oracle, Microsoft, Facebook parent company Meta, Amazon, and Google parent company Alphabet—and highlighted how they have increasingly moved financing off their corporate balance sheets.
"Over the past 12-18 months, there has been a huge increase in debt and equity issuance," Jensen explained. "The five hyperscalers now have a combined over $1.3 trillion of debt on their balance sheets and roughly $3 trillion in off-balance-sheet allocations."
Because of this, Jensen continued, "debt markets are starting to groan" by "signaling a substantial chance of default over the next half-decade on the debt of Oracle."
Jensen also pointed out that half of this infrastructure was being built for the benefit of frontier AI labs OpenAI and Anthropic, which he described as "unprofitable" and "bleeding cash."
Dean Baker, co-founder of the Center for Economic and Policy Research argued in an analysis published on Friday that AI is completely propping up the US economy at the moment, as investors are holding out hope that it delivers an unprecedented boom in productivity.
The problem, Baker pointed out, is there is little sign that AI is going to deliver anywhere near the increased productivity needed to make these historic investments pay off.
"If we believe the hype, we are about to see an incredible surge in productivity that will make us ridiculously wealthy," Baker explained. "To date, there is no evidence to support this view. Productivity growth has been at best on its trend pace the last couple of years."
"If we don’t see the massive gains in productivity promised by the AI enthusiasts," Baker added, "then we will almost certainly see a collapse in the stock market, with a serious recession almost guaranteed."
"Costs are hitting Main Street from every direction at once and Washington doesn't seem to care about the needs of small business owners," said the head of a national coalition.
Arizona-based Gabe Hagen said Tuesday that "to keep my business afloat, I invested my 401(k) savings and leveraged my home equity as collateral for additional capital, putting my family's financial security on the line to sustain my business and employees."
"I raised my prices, but sales have just flattened out because customers are ordering less," explained Hagen, who founded the Tempe coffee roasting company Brick Road Community Corporation. He's among over 1,000 US small business owners polled by the national coalition Small Business for America's Future from mid-August to early October.
Among those surveyed, 77% have seen customers spend less, delay purchases, or trade down recently, with 46% saying that shoppers are spending "significantly less." Meanwhile, owners like Hagen are increasingly enduring more financial stress, with many cutting their own pay or pulling money from personal savings to keep their companies operating.
The survey exposes how "a combination of factors is crushing small business," the coalition said in a statement announcing its resulting report—which highlights soaring costs for everything from fuel to healthcare, and was released just weeks away from the US midterm elections that will determine control of Congress for the latter half of Trump's second term.
"Costs are hitting Main Street from every direction at once and Washington doesn't seem to care about the needs of small business owners," said Walt Rowen, the coalition's co-chair and president of Susquehanna Glass Co., a family-owned glass manufacturer in Columbia, Pennsylvania that's been around for over a century.
Rowen—whose company is located in a key swing state—noted that "my business is a good example of what is happening. We've been navigating erratic tariff policies that have disrupted our supply chains, and now my heating oil costs $4,000 to $6,000 a month."
"We've lived through the Depression, wars, and recessions," he said. "Heating my factory in this current economy is some of the hardest math I've ever had to do, and I'm expecting the bill to jump 30% to 40% this winter. This survey shows us that I am far from alone. Small business owners everywhere are comparing this economy to some of the worst moments we've had this century."
The survey shows that 83% of small business owners are concerned about their company's financial health over the next year, including 44% who are very concerned. Three-quarters called this one of the hardest economies of their careers, with over half drawing comparisons to the Covid-19 pandemic, and nearly a third pointing to the Great Recession.
A similar share (78%) accused decision-makers in Washington, DC of putting large corporations first, and 72% said running their business is harder than it was a year ago—with 85% citing inflation and rising prices as the source of strain. Majorities saw increases for utilities (72%); fuel (68%); transportation, shipping, or supplies (64%); business services (64%); healthcare and health insurance (54%); and employee wages and benefits (53%).
Those soaring costs have had consequences. Two-thirds of surveyed owners said they canceled, delayed, or scaled back investments in equipment, facilities, or technology. Over half did the same for hiring and expansion to new markets. Nearly two-thirds skipped or reduced their own pay, and 52% said their personal debt has increased in the past year.
Rising costs can be clearly connected to decisions by Trump and congressional Republicans—many of whom are up for reelection next month, as the GOP tries to hang on to its slim majorities in both chambers.
The president returned to power early last year having campaigned on a mass detention and deportation agenda, despite arguments from economists and elected Democrats that his approach was not only inhumane but economically risky. A clear majority of surveyed owners (61%) said that immigration enforcement has hurt the small business economy.
Trump and Republican lawmakers also enacted a 2025 budget package that cut federal healthcare spending and did not extend Affordable Care Act enhanced premium tax credits. Among surveyed business owners who buy their own insurance coverage through an ACA marketplace, 90% saw their premiums rise after the subsidies expired. Nearly three-quarters also said they fear rising health insurance costs will make it harder to hire and keep needed employees.
The administration's shifting tariff policy and refund process have caused further stress: 59% of owners said trade-related cost increases have made it harder to run their business, and only 3% have filed refund claims since the US Supreme Court's February ruling against many of Trump's tariffs.
Trump's illegal war on Iran continues to drive up fuel prices. The construction of artificial intelligence data centers—which the president has encouraged—is also increasing energy costs. Nearly three-quarters of those surveyed are worried about the impact of electricity demand from new AI facilities. Around the same share is concerned about the consequences of the new armed conflict in the Middle East, which the GOP-controlled Congress never authorized, but has refused to end.
In a social media post about all the findings, Small Business for America's Future urged, "Lawmakers, make your next decision with Main Street in mind."
Republicans' cuts to Medicaid and their refusal to extend enhanced Affordable Care Act subsidies are key factors in the coverage drop.
Independent healthcare analyst Charles Gaba on Thursday published an updated analysis estimating that up to 12 million Americans have lost their insurance coverage since the start of President Donald Trump's second term.
Gaba based his new estimate on updated data he compiled from recent reports for Medicare, Medicaid, and the Children's Health Insurance Program (CHIP), as well as some state enrollment data for Affordable Care Act (ACA) insurance exchanges.
In total, Gaba found that enrollment in Medicaid and CHIP has dropped by 6.2 million people since the start of Trump's second term, while enrollment in ACA exchanges is down by anywhere from 4.6 million to 6.1 million people, and enrollment in Basic Health Plans (BHP) is down by nearly 275,000 people over the same period.
While there are around 1.8 million more people enrolled in Medicare now than there were at the start of Trump's term, Gaba noted that this isn't nearly enough to make up for the loss of enrollment in other programs.
Adding everything up, Gaba estimated that "between 10.88 million and 12.40 million fewer Americans enrolled in a public healthcare coverage program as of June 2026 than in were as of January 2025."
As in prior analyses, Gaba examined the possibility that some of the people who lost coverage through these programs transitioned to employer-sponsored insurance, but deemed it "extremely unlikely... since unemployment is higher than it was in January 2025."
Over the last two years, Trump and congressional Republicans have taken a number of actions that have made healthcare less affordable and pushed people off coverage.
First, they cut spending on Medicaid by an estimated $900 billion over a 10-year period when they enacted the One Big Beautiful Bill Act in 2025. The Congressional Budget Office projects these cuts will leave more than 10 million fewer people enrolled in the program by 2034.
GOP lawmakers last year also refused to extend enhanced subsidies for insurance plans purchased through the ACA, even as insurers raised premiums on those plans by an average of 26% this year, according to an analysis published by KFF.
In a Thursday article published by Time, scholars Neale Mahoney and Abigail Sanchez of the Stanford Institute for Economic Research warned that the costs of private health insurance are set to spike even further in 2027.
"Employer health plan costs are projected to rise 8 to 10% next year," Mahoney and Sanchez explained, "the largest increase in more than 20 years and double the average increase of the 2010s."
The two researchers said there are three major reasons for the surge in insurance costs: The expiration of the enhanced ACA subsidies, an increase in premiums and out-of-pocket costs for employer-based insurance plans, and the upcoming Medicaid work requirements projected to push millions of people off the program.
"Donald Trump promised to lower costs on day one. Instead, he has spent his presidency creating an affordability crisis, and now he's calling his self-made crisis a hoax."
With the US midterm elections just weeks away and control of Congress up for grabs, the top Democrat on the Senate Banking, Housing, and Urban Affairs Committee on Wednesday released a tool tracking inflation under Republican President Donald Trump.
"Donald Trump promised to lower costs on day one. Instead, he has spent his presidency creating an affordability crisis, and now he's calling his self-made crisis a hoax," said Ranking Member Elizabeth Warren (D-Mass.) in a statement. "The Trumpflation Tracker will show families across the country exactly how much of a price they are paying for Trump's and Republicans' failed economic agenda."
The tracker shows not only cumulative inflation since December 2024, the month before Trump returned to office—it's up 5.2%— but also limited job growth during his second term, the impact of his broken promise to cap credit card interest rates, falling wages since he launched an illegal war on Iran in February, mortgage rate increases, and rising household debt.
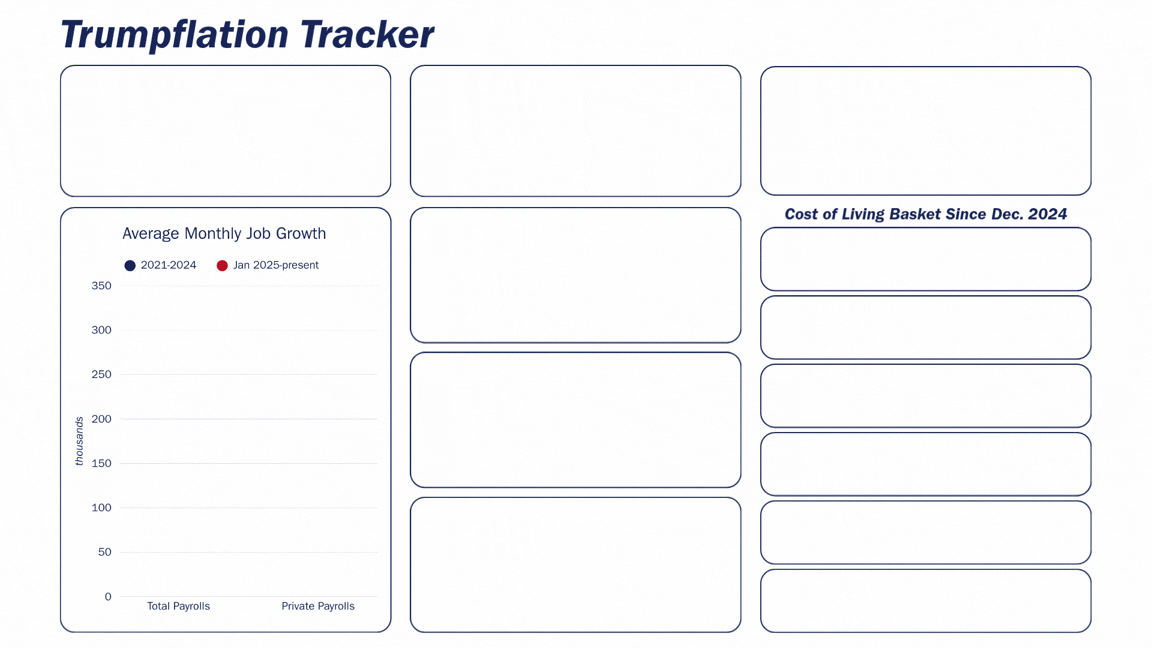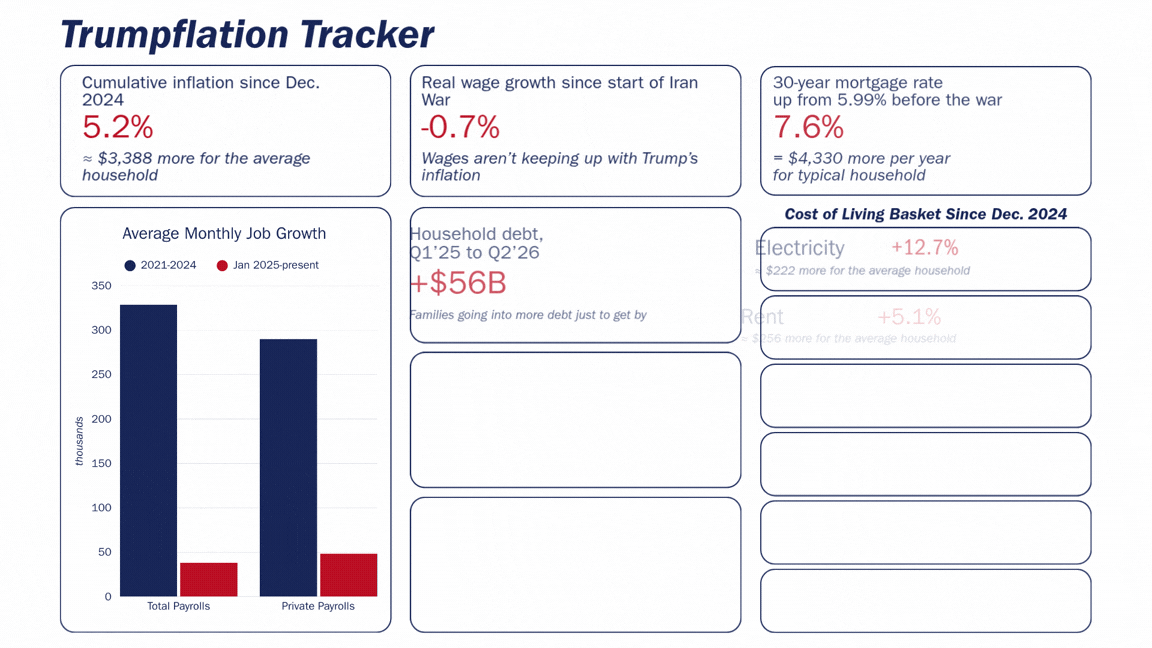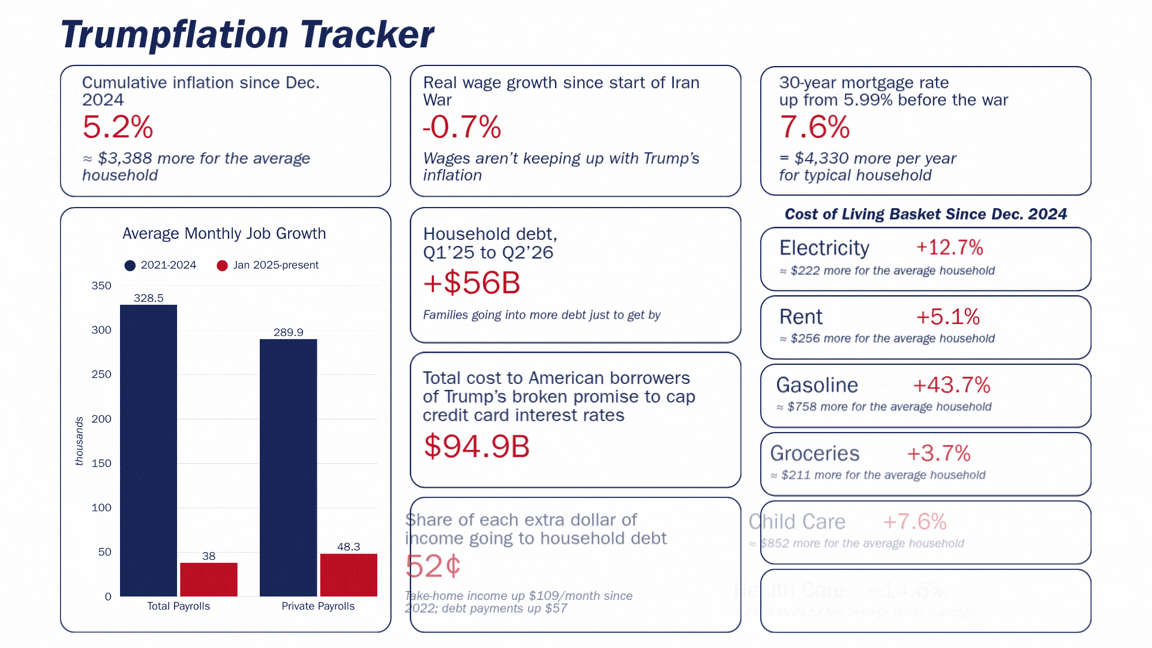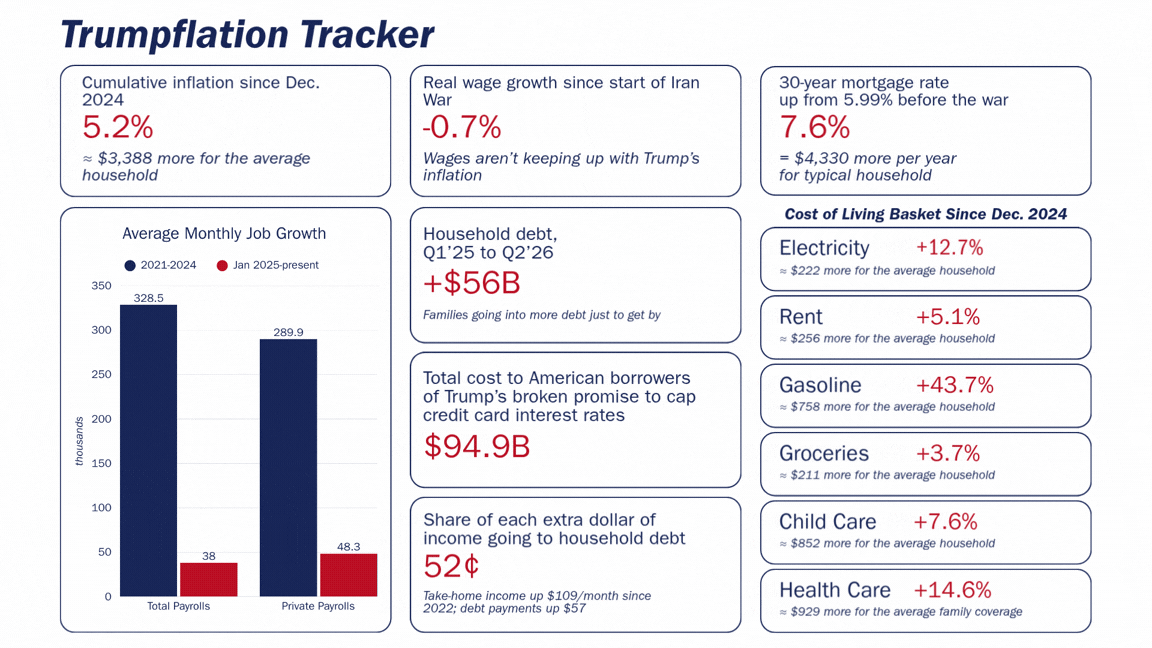
The tool also highlights the country's affordability crisis, detailing how costs have skyrocketed for childcare, electricity, gasoline, groceries, healthcare, and rent, with the average US household paying over $3,000 more.
As Trump rallies behind efforts to build more energy-sucking artificial intelligence data centers, Warren's tracker shows that residential electricity prices are up 12.7% during this term, with the average US household paying $222 more.
Last year, congressional Republicans passed and Trump signed a budget package that cut government healthcare programs and did not extend expiring Affordable Care Act subsidies. Now, per the new tool, healthcare costs are up 14.6%.
Prices for gas and diesel have skyrocketed since Trump and the Israeli military started bombing Iran, but the US president has dismissed concerns, claiming that paying $4 at the pump is "not very high" and is worthwhile to prevent the Middle Eastern nation from building a nuclear weapon—which the US intelligence community concluded, before the war, that Tehran wasn't trying to do.
Warren's tracker puts the gas surge at 43.7% since December 2024, with an average cost of over $750 per household. The senator plans to have the panel's economic experts update the figures on a monthly basis, as more data becomes available.
The Century Foundation's president, Julie Margetta Morgan, applauded the committee "for doing the math on this," writing on social media that "the Trump administration continues to claim that the economy is strong, but this tracker shows clearly just how much families are being squeezed."
"Walmart has amassed the most intimate information about its customers and is developing the technology that can be used to put that data to work at checkout," said Lindsay Owens of Groundwork Collaborative.
As Walmart attempted to debunk research into its pricing practices by watchdog group Groundwork Collaborative on Monday, the organization released a new report detailing more than a dozen patents the $833 billion corporation holds or has applied for—all aimed at monitoring customers' behavior to determine what products to market to them, deceiving them about an item's price, and upcharging them.
“Corporations don’t spend years building high-tech pricing tools, hiring experts, and filing patents just to let them collect dust. They do it because they see a path to higher profit—one that runs right through everyday consumers’ budgets," said Lindsay Owens, president and CEO of Groundwork and the author of the book Gouged: The End of a Fair Price—And What That Means for Your Wallet.
On Monday, Owens and Elizabeth Pancotti, Groundwork's vice president of policy, advocacy, and research, released “The Walmart Watchtower: Patents Speak Louder Than Pledges,” noting that Walmart CEO John Furner just recently attempted to do damage control on Owens' reporting in Gouged regarding the company's artificial intelligence-enabled pricing tactics.
While Walmart executives have "openly touted" the ability of "Sparky," the AI shopping assistant the company launched last year, to push customers to spend an average of 40% more during a shopping trip, Furner insisted last month that Walmart will "price the product, not the person.”
But Groundwork said that beyond its deployment of Sparky, "Walmart’s own investments and patents suggest that the retail giant is building a vast arsenal of tools that can be used to track shoppers and even potentially determine what they pay."
The report reveals that technology patented by Walmart can:
The company has also filed applications for technology that could:
"Walmart has amassed the most intimate information about its customers and is developing the technology that can be used to put that data to work at checkout," said Owens. "Shoppers will have to decide whether to believe Walmart’s patent applications or its PR statements.”
As the report was released, Dan Bartlett, Walmart's executive vice president of corporate affairs, released a public letter accusing Owens of "mischaracterizations" regarding the company's pricing practices.
"Walmart does not and will not use an individual customer’s personal information, income, shopping history, urgency, or willingness to pay to set an individualized price," said Barlett. "We do not engage in dynamic pricing, raising prices in response to a hot afternoon or an approaching snowstorm, for example."
He also said Groundwork has wrongly taken Walmart's patents "as evidence that we will pursue individualized or dynamic pricing," and said the company has "committed not to."
Although Bartlett denied that the company uses AI to upcharge customers, Walmart US CEO Dave Guggina told investors just last month that “when customers engage with Sparky, their average order value jumps 40%.”
Owens responded to Bartlett's letter by saying that any "confusion around Walmart’s pricing practices is of its own making."
"Walmart says one thing in its damage-control letters to customers, another to its investors behind closed doors, and a different thing entirely to the United States Patent and Trademark Office," said Owens.
She called on Walmart to publicly release information about "what data Sparky can see, how that information shapes the recommendations and purchases it makes, and whether sensitive consumer information could be exposed, misused, or used against shoppers," especially considering recent hacking incidents by AI models.
"The arsenal of technologies the company is building that can be used to profile and track us should worry every American who is concerned about their privacy and pocketbooks," Owens said. "This personal data, according to Walmart’s own patents, is a critical element of the new pricing strategies the company is developing."
The report on Walmart's patents released by Groundwork on Monday, said Owens, will allow Americans to "decide for themselves" whether to believe executives' denials.
"We have to crush these sociopaths," said one critic.
Critics of the artificial intelligence industry expressed horror after OpenAI CEO Sam Altman said the world needs to "accept some bad things happening" as the price to pay for technological advancement.
In a Sunday interview with Politico, Altman was asked where his company differs from rival Anthropic, whose CEO, Dario Amodei, has called for guardrails that will slow the pace of AI development.
"We have always been a big believer that this technology has to be democratized and put into people's hands," said Altman. "One of the biggest differences between us and some of the stricter... AI safety people is that we believe the world should accept some bad things happening for the benefits of this technology."
“We believe the world should accept some bad things happening for the benefits of this technology.”In a conversation for the first edition of Decoded, a new daily newsletter and podcast, OpenAI CEO Sam Altman talked with POLITICO’s @BrendanBordelon about trade-offs, AI safety, and how his company is different from Anthropic.Subscribe to Decoded for the full conversation with Sam Altman: https://t.co/YHJJsDOQVh
— POLITICO (@politico) October 4, 2026
Altman went on to say that one reason he's called for "lighter touch" regulation "comes with an accepting of the fact that some bad things are going to happen as society figures out the resilience."
Critics reacted furiously to Altman's blithe dismissal of "bad things" his own company's technology could cause, especially because many AI developers have warned that it could potentially wipe out human life.
Patrick Gaspard, distinguished senior fellow at the Center for American Progress, called Altman's statement "freaking insane" and said politicians cannot let the AI industry continue without any regulations.
"Our elected leaders need to move past the polling safe territory of data center resistance to the real work of regulating these narcissistic freaks," Gaspard wrote in a Sunday social media post, "who gleefully tell us that we 'need to accept some bad things' from AI for their massive profits. And they don’t even know the limits of what they’re unleashing."
Joshua Topolsky, co-founder of tech news website The Verge, completely rejected the premise of Altman's argument.
"No, I don't think this is a reasonable answer or position," Topolsky wrote, "and no one should accept it or acquiesce to it."
Commentator Wajahat Ali said Altman's statement showed the need for a political movement against the AI industry.
"We have to crush these sociopaths," Ali wrote. "The problem is that many Democrats take money from them, which means they will get bailed out at our expense in the next two to four years."
Ali's comments were echoed by Talking Points Memo founder Josh Marshall.
"A whole political movement should be stood up against this arrogant and sociopathic bullshit," Marshall wrote.
Adam Carlson, founder of Zenith Polls, said Altman's remarks were symbolic of how completely out of touch Silicon Valley executives are with ordinary people.
"To any normal, rational person who doesn’t stand to materially benefit from AI acceleration or buy their whole schtick hook line and sinker," wrote Carlson, "you genuinely just sound insane talking about 'accepting bad things' without specifying exactly what you mean."
The social media account for The Tennessee Holler offered up a satirical summary of Atlman's argument.
"Sociopath elitist tech fascists who think they’re creating God and believe democracy is the enemy," The Tennessee Holler wrote, "want us to finance our own demise to let them take over the world."
"It’s a stalled economy—and working families are stuck in it," said one economist.
A Friday report from the US Bureau of Labor Statistics showed that the American job market is running on fumes.
According to the BLS, the US economy added just 29,000 jobs in September, which was well below economists' forecasts of 90,000 jobs added on the month.
Additionally, employment numbers for previous months were revised downward by a total of 60,000 jobs, and BLS now estimates that the economy posted a net loss of 10,000 jobs in July and a net gain of 133,000 jobs in August.
In a Friday social media post, economist Bill McBride noted that the economy over the last year has only created 496,000 jobs, which averages to roughly 41,000 jobs per month. For comparison, the economy created an average of 186,000 jobs per month in the last year of former President Joe Biden's term.
Heather Long, chief economist at Navy Federal Credit Union, called the latest jobs numbers "mediocre," and pointed out that wage growth in September posted just a 3% yearly gain.
"That’s a new five-year low," Long remarked, "and it’s wiped out entirely by ~3.4% inflation."
Tahra Hoops, director of economic analysis at Chamber of Progress, also pointed to wage growth failing to keep up with inflation, which she said "gives credibility to the negative consumer sentiment" expressed in recent surveys.
Kyle Moore, chief economist at The Century Foundation, said that the weak wage growth on the month doesn't tell the full story of the stresses working-class Americans are facing because the numbers "leave out debt, all the bills families have to pay before they can spend any of their paycheck."
"A worker with debt often can’t afford to miss a paycheck, and therefore can’t afford to quit a bad job or push for a raise," Moore explained. "That is exactly what we see in today’s job market, with hiring stalled, the quit rate stuck at 1.9%, and wage growth falling as prices climb. Mounting debt, sluggish hiring and real wage growth, and weak social support all disempower workers."
Moore criticized President Donald Trump and his administration for trying to spin their economic policies as successes given the current numbers.
"Until the Trump administration confronts the reality that debt is eating into workers’ gains—wage gains that are now non-existent, in real terms, for the typical worker," said Moore, "the gulf between how this administration spins the economy and how working families actually experience it will continue to widen."
White House National Economic Council Director Kevin Hassett didn't heed Moore's advice on this matter, and continued boasting about the state of the economy during a Friday interview.
"If you look at the data from this week, it's proving that Trumponomics is really working," said Hassett, "and this is one reason why markets are celebrating so much."
Kevin Hassett responds to a bad September jobs report: "If you look at the data from this week, it's proving that Trumponomics is really working ... we're very very happy"
The Fox News host responds by saying "you're bullish and I expected that" pic.twitter.com/bVdTFnteHc
— Aaron Rupar (@atrupar) October 2, 2026
Breyon Williams, chief economist at Groundwork Collaborative, called the weak jobs report emblematic of how the economy as a whole has performed during Trump's second term.
"There’s a clear pattern in the Trump economy," Williams explained. "One sector is creating most of the new jobs, unemployed workers can’t find new jobs, and Americans are seeing their paychecks eaten up by the president’s high prices. When businesses are barely hiring and raises aren’t keeping up with rising prices, it’s a stalled economy—and working families are stuck in it."