SUBSCRIBE TO OUR FREE NEWSLETTER
Daily news & progressive opinion—funded by the people, not the corporations—delivered straight to your inbox.
5
#000000
#FFFFFF
To donate by check, phone, or other method, see our More Ways to Give page.
Daily news & progressive opinion—funded by the people, not the corporations—delivered straight to your inbox.
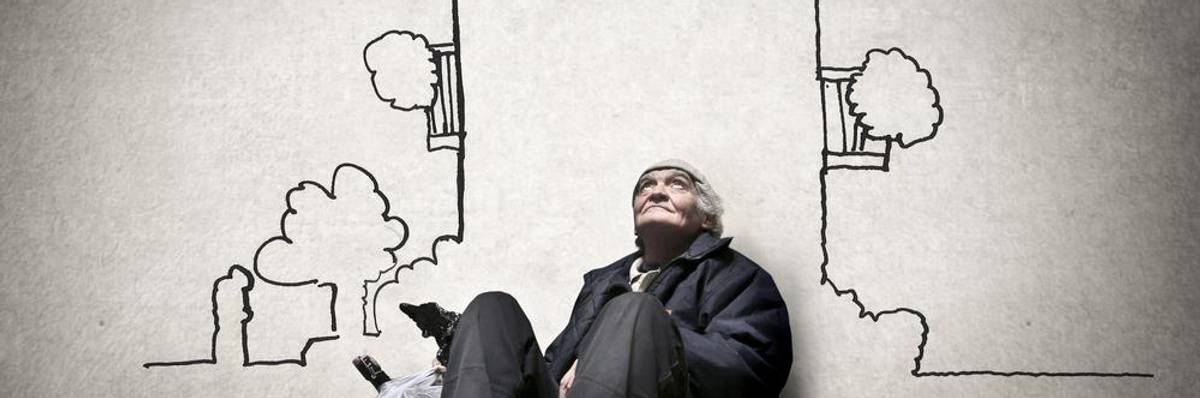
Poorer seniors are likely to have been poor, or among the working poor, most of their lives. (Photo: Shutterstock)
Vivian Majors spent her life cleaning houses while her husband, Martin, worked as a carpenter.
Their bodies broke down in their 60s. Martin now lives in a nursing home and has Parkinson's disease. Vivian, now 71, lives on her own and ekes by on a $960 in social security, plus $50 in food stamps.
Hardened by years of physically taxing work that left her hovering around the poverty line, Majors, now retired, is girding herself for more years of financial hardship.
Social Security supposedly wiped out the scourge of old-age poverty. But inequality has widened the gap between the secure and insecure in all age groups, exposing American seniors to financial distress in ways that often go unnoticed.
According to research from the University of Massachusetts Boston, material hardship bedevils millions of Americans like Majors.
Opelousas, Louisiana, where Majors and her husband grew up and raised their own children, has the highest rate of elderly poverty in the United States. Opelousas is home to men and women who have worked all their lives. But in 2017, the average per-capita income in the town was only $15,266 a year, and 45 percent of its population lived in poverty.
As inequality impacts more working-age Americans, the poverty they experience throughout life follows them into old age.
Few Opelousas retirees received sick leave or health care coverage while they were working, and virtually none can count on a pension. A lifetime of poverty rarely translates into what the rest of the country defines as true retirement. Instead, the working poor often stay on the job past retirement age.
Social Security has played a crucial role in bringing down poverty rates for Americans over 65. But the lives of older Americans are a natural extension of their experiences in their prime working years.
As inequality impacts more working-age Americans, the poverty they experience throughout life follows them into old age. The Gerontology Institute at the University of Massachusetts Boston found in 2016 that a majority of American seniors lacked "the financial resources required to pay for basic needs."
The numbers are higher for those living alone than those in two-senior households, but overall the material hardship of the elderly is significant -- especially for the large population living just a little above the official poverty line.
These households miss out on benefits--from food stamps to housing grants to Medicaid--designed to assist those in need. They're on their own and yet facing significant shortfalls in the resources needed to survive at a minimally acceptable level.
Gaps were particularly problematic for women who, on average, received $4,500 less per year in Social Security benefits than men.
The institute found that gaps were particularly problematic for women who, on average, received $4,500 less per year in Social Security benefits than men because they had lower lifetime earnings and worked fewer quarters to take time out for caregiving.
In this sense, elder poverty isn't really about elders; it's about whole lifetimes of economic marginality.
Poorer seniors are likely to have been poor, or among the working poor, most of their lives. They've held jobs that paid low wages, were often involuntarily part-time, provided for no sick leave or health insurance, and provided nothing at all in the way of pensions.
Majors is a frugal woman. She shuts down the air conditioner during humid Louisiana summers rather than see her electricity bill rise. Even in her old age, with such limited resources, she lends a hand to her grown children when they need it.
"A lot of people sometimes wonder how you're making it," she says. "But you manage, you know. You're going to survive."
That is no doubt true. Yet we can ask ourselves why merely being able to "manage" is the best that can be expected for a hardworking woman like Majors. Retirement shouldn't mean hardship in the 21st century.
This country and this world are at a monumental crossroads. US voters have an opportunity to beat back the forces of fascism and confront the billionaires who are rigging the economy, our media system, and our democracy, making it increasingly impossible for ordinary people to get by. We’re not just talking about the election. We’re talking about what must be done once these fascist elements are vanquished from power. We need a bolder set of solutions than what either major party has so far been willing to offer and a working-class movement ready to fight like hell for it. Trump didn't emerge from nowhere. The conditions that fueled MAGA authoritarianism were created by decades of radical neoliberal economic policies and a corrupt political system dominated by corporate interests. They slashed taxes on the super-rich, promising that the benefits would trickle down. They said giveaways to the corporate titans would make life more affordable for the rest of us. It was all bullshit. And when a bitter, betrayed populace searches for someone to blame, right-wing demagogues have little trouble finding scapegoats. People know when they're being lied to, but you won't hear any of this from the corporate media. Only independent journalism—powered and funded by people who believe in building a better world—can deliver truly trustworthy daily news. If you share our vision, please contribute whatever you can to sustain our work. |
Vivian Majors spent her life cleaning houses while her husband, Martin, worked as a carpenter.
Their bodies broke down in their 60s. Martin now lives in a nursing home and has Parkinson's disease. Vivian, now 71, lives on her own and ekes by on a $960 in social security, plus $50 in food stamps.
Hardened by years of physically taxing work that left her hovering around the poverty line, Majors, now retired, is girding herself for more years of financial hardship.
Social Security supposedly wiped out the scourge of old-age poverty. But inequality has widened the gap between the secure and insecure in all age groups, exposing American seniors to financial distress in ways that often go unnoticed.
According to research from the University of Massachusetts Boston, material hardship bedevils millions of Americans like Majors.
Opelousas, Louisiana, where Majors and her husband grew up and raised their own children, has the highest rate of elderly poverty in the United States. Opelousas is home to men and women who have worked all their lives. But in 2017, the average per-capita income in the town was only $15,266 a year, and 45 percent of its population lived in poverty.
As inequality impacts more working-age Americans, the poverty they experience throughout life follows them into old age.
Few Opelousas retirees received sick leave or health care coverage while they were working, and virtually none can count on a pension. A lifetime of poverty rarely translates into what the rest of the country defines as true retirement. Instead, the working poor often stay on the job past retirement age.
Social Security has played a crucial role in bringing down poverty rates for Americans over 65. But the lives of older Americans are a natural extension of their experiences in their prime working years.
As inequality impacts more working-age Americans, the poverty they experience throughout life follows them into old age. The Gerontology Institute at the University of Massachusetts Boston found in 2016 that a majority of American seniors lacked "the financial resources required to pay for basic needs."
The numbers are higher for those living alone than those in two-senior households, but overall the material hardship of the elderly is significant -- especially for the large population living just a little above the official poverty line.
These households miss out on benefits--from food stamps to housing grants to Medicaid--designed to assist those in need. They're on their own and yet facing significant shortfalls in the resources needed to survive at a minimally acceptable level.
Gaps were particularly problematic for women who, on average, received $4,500 less per year in Social Security benefits than men.
The institute found that gaps were particularly problematic for women who, on average, received $4,500 less per year in Social Security benefits than men because they had lower lifetime earnings and worked fewer quarters to take time out for caregiving.
In this sense, elder poverty isn't really about elders; it's about whole lifetimes of economic marginality.
Poorer seniors are likely to have been poor, or among the working poor, most of their lives. They've held jobs that paid low wages, were often involuntarily part-time, provided for no sick leave or health insurance, and provided nothing at all in the way of pensions.
Majors is a frugal woman. She shuts down the air conditioner during humid Louisiana summers rather than see her electricity bill rise. Even in her old age, with such limited resources, she lends a hand to her grown children when they need it.
"A lot of people sometimes wonder how you're making it," she says. "But you manage, you know. You're going to survive."
That is no doubt true. Yet we can ask ourselves why merely being able to "manage" is the best that can be expected for a hardworking woman like Majors. Retirement shouldn't mean hardship in the 21st century.
Vivian Majors spent her life cleaning houses while her husband, Martin, worked as a carpenter.
Their bodies broke down in their 60s. Martin now lives in a nursing home and has Parkinson's disease. Vivian, now 71, lives on her own and ekes by on a $960 in social security, plus $50 in food stamps.
Hardened by years of physically taxing work that left her hovering around the poverty line, Majors, now retired, is girding herself for more years of financial hardship.
Social Security supposedly wiped out the scourge of old-age poverty. But inequality has widened the gap between the secure and insecure in all age groups, exposing American seniors to financial distress in ways that often go unnoticed.
According to research from the University of Massachusetts Boston, material hardship bedevils millions of Americans like Majors.
Opelousas, Louisiana, where Majors and her husband grew up and raised their own children, has the highest rate of elderly poverty in the United States. Opelousas is home to men and women who have worked all their lives. But in 2017, the average per-capita income in the town was only $15,266 a year, and 45 percent of its population lived in poverty.
As inequality impacts more working-age Americans, the poverty they experience throughout life follows them into old age.
Few Opelousas retirees received sick leave or health care coverage while they were working, and virtually none can count on a pension. A lifetime of poverty rarely translates into what the rest of the country defines as true retirement. Instead, the working poor often stay on the job past retirement age.
Social Security has played a crucial role in bringing down poverty rates for Americans over 65. But the lives of older Americans are a natural extension of their experiences in their prime working years.
As inequality impacts more working-age Americans, the poverty they experience throughout life follows them into old age. The Gerontology Institute at the University of Massachusetts Boston found in 2016 that a majority of American seniors lacked "the financial resources required to pay for basic needs."
The numbers are higher for those living alone than those in two-senior households, but overall the material hardship of the elderly is significant -- especially for the large population living just a little above the official poverty line.
These households miss out on benefits--from food stamps to housing grants to Medicaid--designed to assist those in need. They're on their own and yet facing significant shortfalls in the resources needed to survive at a minimally acceptable level.
Gaps were particularly problematic for women who, on average, received $4,500 less per year in Social Security benefits than men.
The institute found that gaps were particularly problematic for women who, on average, received $4,500 less per year in Social Security benefits than men because they had lower lifetime earnings and worked fewer quarters to take time out for caregiving.
In this sense, elder poverty isn't really about elders; it's about whole lifetimes of economic marginality.
Poorer seniors are likely to have been poor, or among the working poor, most of their lives. They've held jobs that paid low wages, were often involuntarily part-time, provided for no sick leave or health insurance, and provided nothing at all in the way of pensions.
Majors is a frugal woman. She shuts down the air conditioner during humid Louisiana summers rather than see her electricity bill rise. Even in her old age, with such limited resources, she lends a hand to her grown children when they need it.
"A lot of people sometimes wonder how you're making it," she says. "But you manage, you know. You're going to survive."
That is no doubt true. Yet we can ask ourselves why merely being able to "manage" is the best that can be expected for a hardworking woman like Majors. Retirement shouldn't mean hardship in the 21st century.