Talk about piling on. Bill Gates, the Pope, Michael Moore, the Archbishop of Canterbury, 1,000 parliamentarians, 1,000 economists, the world's major labor leaders, Occupy Wall Street protestors, Oxfam and other major development groups, thousands of nurses, the World Wildlife Fund and other major enviros...It might be easier to list who didn't come out didn't come out in support of a Wall Street tax in the lead-up to this week's G20 summit in Cannes.
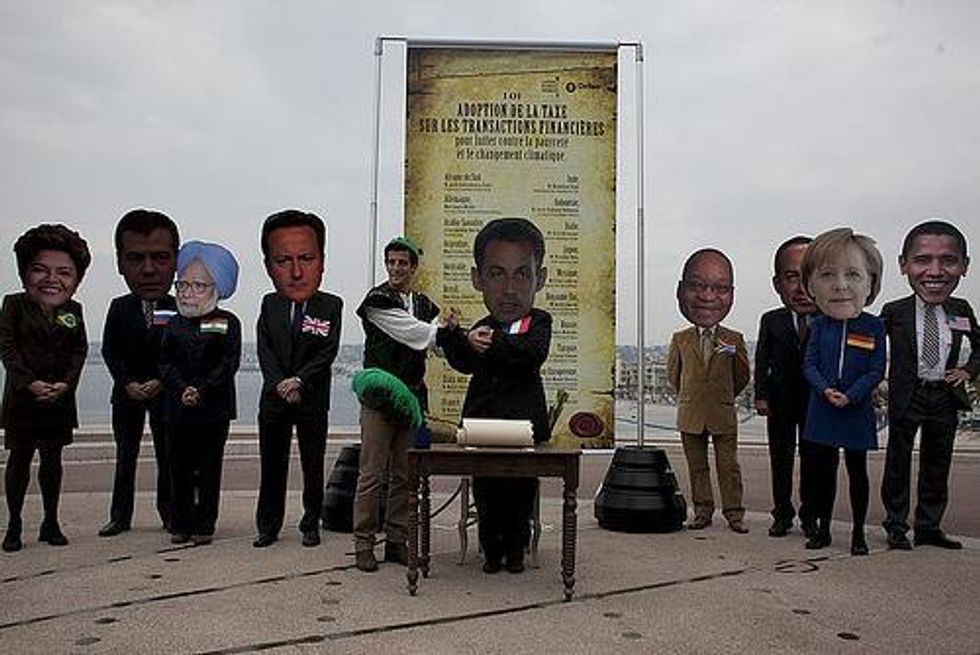
The outcome? No home run, but some measurable steps forward.
No one expected a G20-wide agreement on taxing financial transactions at this summit. Despite rising support, opposition from the United Kingdom, Canada, and the United States, among others, is still just too strong. But there were high hopes that a subset of European and non-European G20 countries would launch a "coalition of the willing" in support of the tax.
This goal was achieved. In his concluding press conference, summit host French President Nicolas Sarkozy announced that South Africa, Brazil, and Argentina were joining the list of current supporters, including France, Germany, Spain, the European Commission, and several other European governments. Sarkozy said he hopes to move towards implementation in early 2012.
Sarkozy and German Chancellor Angela Merkel have been the strongest supporters of taxing financial transactions for nearly two years. A few months ago, the European Commission also reversed its earlier opposition and released proposed legislation for such a tax in the European Union. But while Europe appears likely to move forward, the addition of several emerging market countries to the supporter list is significant for several reasons:
- The increased revenue that can be generated.
- The reduced potential for tax avoidance.
- The enhanced chances that revenue won't just be plowed into European bank bailouts, but instead spent on human needs in both the global North and South.
- The strengthened legitimacy through the backing of rising powers in the Global South.
For U.S. advocates, there was another modest victory. Over the past two years, Treasury Secretary Timothy Geithner has made no secret of his aversion to the tax. In September, Geithner angered some of his European counterparts by objecting to proposals to raise funds to address their deficit problems through an EU-wide tax on financial transactions.
In Cannes, the Obama position shifted from active blocking to friendly neutrality.
"The president made clear that he shares the objectives that Chancellor Merkel and President Sarkozy have in ensuring that the financial sector contributes an appropriate share to the resolution of crises," said Michael Froman, the White House's G20 point person. "I think there is broad consensus between the Europeans that the president met with this morning and ourselves about the ability of each to pursue this in their own way, whatever way they see to be most effective."
The final communique of the G20 leaders was a disappointment, however.
The only relevant line in it is a typical diplomatic non-statement: "We acknowledge the initiatives in some of our countries to tax the financial sector for various purposes including a financial transaction tax inter alia to support development."
But with the likelihood of a critical mass of countries coordinating taxes on financial speculation, this kind of mumbo jumbo may disappear in the coming years. Once other governments start generating massive revenues by taxing speculation, even the most closed-minded economic advisors in this country may see the issue anew.
Talk about piling on. Bill Gates, the Pope, Michael Moore, the Archbishop of Canterbury, 1,000 parliamentarians, 1,000 economists, the world's major labor leaders, Occupy Wall Street protestors, Oxfam and other major development groups, thousands of nurses, the World Wildlife Fund and other major enviros...It might be easier to list who didn't come out didn't come out in support of a Wall Street tax in the lead-up to this week's G20 summit in Cannes.
The outcome? No home run, but some measurable steps forward.
No one expected a G20-wide agreement on taxing financial transactions at this summit. Despite rising support, opposition from the United Kingdom, Canada, and the United States, among others, is still just too strong. But there were high hopes that a subset of European and non-European G20 countries would launch a "coalition of the willing" in support of the tax.
This goal was achieved. In his concluding press conference, summit host French President Nicolas Sarkozy announced that South Africa, Brazil, and Argentina were joining the list of current supporters, including France, Germany, Spain, the European Commission, and several other European governments. Sarkozy said he hopes to move towards implementation in early 2012.
Sarkozy and German Chancellor Angela Merkel have been the strongest supporters of taxing financial transactions for nearly two years. A few months ago, the European Commission also reversed its earlier opposition and released proposed legislation for such a tax in the European Union. But while Europe appears likely to move forward, the addition of several emerging market countries to the supporter list is significant for several reasons:
- The increased revenue that can be generated.
- The reduced potential for tax avoidance.
- The enhanced chances that revenue won't just be plowed into European bank bailouts, but instead spent on human needs in both the global North and South.
- The strengthened legitimacy through the backing of rising powers in the Global South.
For U.S. advocates, there was another modest victory. Over the past two years, Treasury Secretary Timothy Geithner has made no secret of his aversion to the tax. In September, Geithner angered some of his European counterparts by objecting to proposals to raise funds to address their deficit problems through an EU-wide tax on financial transactions.
In Cannes, the Obama position shifted from active blocking to friendly neutrality.
"The president made clear that he shares the objectives that Chancellor Merkel and President Sarkozy have in ensuring that the financial sector contributes an appropriate share to the resolution of crises," said Michael Froman, the White House's G20 point person. "I think there is broad consensus between the Europeans that the president met with this morning and ourselves about the ability of each to pursue this in their own way, whatever way they see to be most effective."
The final communique of the G20 leaders was a disappointment, however.
The only relevant line in it is a typical diplomatic non-statement: "We acknowledge the initiatives in some of our countries to tax the financial sector for various purposes including a financial transaction tax inter alia to support development."
But with the likelihood of a critical mass of countries coordinating taxes on financial speculation, this kind of mumbo jumbo may disappear in the coming years. Once other governments start generating massive revenues by taxing speculation, even the most closed-minded economic advisors in this country may see the issue anew.
Talk about piling on. Bill Gates, the Pope, Michael Moore, the Archbishop of Canterbury, 1,000 parliamentarians, 1,000 economists, the world's major labor leaders, Occupy Wall Street protestors, Oxfam and other major development groups, thousands of nurses, the World Wildlife Fund and other major enviros...It might be easier to list who didn't come out didn't come out in support of a Wall Street tax in the lead-up to this week's G20 summit in Cannes.
The outcome? No home run, but some measurable steps forward.
No one expected a G20-wide agreement on taxing financial transactions at this summit. Despite rising support, opposition from the United Kingdom, Canada, and the United States, among others, is still just too strong. But there were high hopes that a subset of European and non-European G20 countries would launch a "coalition of the willing" in support of the tax.
This goal was achieved. In his concluding press conference, summit host French President Nicolas Sarkozy announced that South Africa, Brazil, and Argentina were joining the list of current supporters, including France, Germany, Spain, the European Commission, and several other European governments. Sarkozy said he hopes to move towards implementation in early 2012.
Sarkozy and German Chancellor Angela Merkel have been the strongest supporters of taxing financial transactions for nearly two years. A few months ago, the European Commission also reversed its earlier opposition and released proposed legislation for such a tax in the European Union. But while Europe appears likely to move forward, the addition of several emerging market countries to the supporter list is significant for several reasons:
- The increased revenue that can be generated.
- The reduced potential for tax avoidance.
- The enhanced chances that revenue won't just be plowed into European bank bailouts, but instead spent on human needs in both the global North and South.
- The strengthened legitimacy through the backing of rising powers in the Global South.
For U.S. advocates, there was another modest victory. Over the past two years, Treasury Secretary Timothy Geithner has made no secret of his aversion to the tax. In September, Geithner angered some of his European counterparts by objecting to proposals to raise funds to address their deficit problems through an EU-wide tax on financial transactions.
In Cannes, the Obama position shifted from active blocking to friendly neutrality.
"The president made clear that he shares the objectives that Chancellor Merkel and President Sarkozy have in ensuring that the financial sector contributes an appropriate share to the resolution of crises," said Michael Froman, the White House's G20 point person. "I think there is broad consensus between the Europeans that the president met with this morning and ourselves about the ability of each to pursue this in their own way, whatever way they see to be most effective."
The final communique of the G20 leaders was a disappointment, however.
The only relevant line in it is a typical diplomatic non-statement: "We acknowledge the initiatives in some of our countries to tax the financial sector for various purposes including a financial transaction tax inter alia to support development."
But with the likelihood of a critical mass of countries coordinating taxes on financial speculation, this kind of mumbo jumbo may disappear in the coming years. Once other governments start generating massive revenues by taxing speculation, even the most closed-minded economic advisors in this country may see the issue anew.