SUBSCRIBE TO OUR FREE NEWSLETTER
Daily news & progressive opinion—funded by the people, not the corporations—delivered straight to your inbox.
5
#000000
#FFFFFF
To donate by check, phone, or other method, see our More Ways to Give page.
Daily news & progressive opinion—funded by the people, not the corporations—delivered straight to your inbox.
Unilever’s buyback strategy undermines all three pillars of the triple bottom line: weakening long-term economic resilience, harming workers and consumers, and perpetuating avoidable animal suffering.
Fresh off its expensive World Cup advertisement spend, which included covering the referee time board with its deodorant name, Unilever recently announced more stock buybacks. At a time when Unilever, one of the world’s largest packaged goods companies, has billions at its disposal to reinvest in its supply chain and animal welfare commitments, the company chose to pour the money into self-enriching stock buybacks. The result is a widening gap between what Unilever says it values and where it is actually putting its resources.
Recently, in June 2026, Unilever’s €1.5 billion share buyback program announced in February 2026 was completed. Unilever plans to support a total of €6 billion of share buybacks between 2026 and 2029.
Once considered a stock manipulation practice that was banned in the US until the mid 1980s, these corporate buybacks benefit those who hold the stock—primarily C-suite executives and shareholders. In fact, Unilever’s own board members purchased substantial sums of stock in May and June 2026, just before the formal announcement of a four-year six billion euro stock buyback program in its recent quarterly report.
This continuous caging is one of the worst forms of animal cruelty, yet by enriching itself through corporate buybacks, Unilever is choosing to profit from caged hens.
Unilever ought to tread lightly. In a special report, Reuters showcased Hewlett-Packard as one of the clearest cases where massive buybacks enriched shareholders in the short term but arguably undermined the company's long-term competitiveness, leading to massive layoffs and reduced innovation.
Moreover, this buyback program hurts the rank-and-file employees who keep Unilever, and its army of subsidiaries, running. Share buybacks can also reduce expenditure on research and development, skill development for jobs of the future, decent pay for staff and suppliers, and lower energy and consumer prices, which would reduce inflation and increase citizens’ purchasing power.
In fact, in 2024, Unilever announced they were eliminating 7,500 jobs. Coincidentally, in Unilever’s most recent quarterly results presentation, Srinivas Phatak celebrated the “€800-million-euro productivity programme" that improved overheads "together with continued simplification and cost discipline."
By choosing to reward shareholders, the company is neglecting to reinvest in its workforce. The consequences also extend to the animals who remain in cages, consumers who are fed empty promises and given less ethical choices, and the company itself, which becomes weakened when it chooses short-term gains over long-term responsibility.
Earlier in 2026, the Open Wing Alliance (OWA), a global coalition of nearly 90 organizations across more than 70 countries, united by a shared mission: to end the abuse of hens worldwide, launched a campaign against Unilever for its broken cage-free promise. Despite earning praise and positive media coverage for its voluntary commitment to free hens in their supply chain from cages by 2025, the company has euphemistically claimed to “end its commitment” along with eliminating its corporate sustainability officer position.
Unilever once committed to sourcing 100% cage-free eggs globally—and achieved this in Europe and North America. But the company abandoned the global aspect of its policy, breaking the promise it made to hens and consumers worldwide, as well as its own “responsible marketing” guidelines (page 30).
This rollback has created a two-tiered animal welfare system: one for Western markets, and another where extreme cruelty remains acceptable. By walking away from its original commitment and spending lavishly on marketing, Unilever is sending a troubling message—that animal welfare and their word matter in some regions, but not in others.
In its code of conduct, Unilever proclaims: to “demonstrate ethical business conduct” and “lead with integrity.” Even in its Sustainable Agriculture Principles 2026, Unilever proclaims to “ensure good animal welfare and promote the health of livestock.” The continued confinement of egg-laying hens in cages directly contradicts its purported business values and agricultural principles. The hens in cages in Unilever’s supply chain have about the space of an iPad to move. In this intense confinement, they are unable to flap their wings or dust bathe, all while standing on cage wires. This continuous caging is one of the worst forms of animal cruelty, yet by enriching itself through corporate buybacks, Unilever is choosing to profit from caged hens.
The world is moving past cages. Ninety-two percent of corporate cage-free commitments due by 2024 have already been fulfilled. Additionally, many countries, including the UK, where Unilever is headquartered, have banned cages entirely or are advancing bans currently, leading to hundreds of millions of hens no longer suffering in cages and eroding the legitimacy of Unilever’s supply excuse. In select geographic locations where cage-free supply is limited, Unilever is not without responsible options aligned with their global commitment. More responsible businesses opt to purchase cage-free credits to fulfill their global cage-free promises. A company that can pay 50,000 influencers around a sporting event yet claims to not be able to navigate supply chain challenges is not being entirely truthful.
Unilever’s spending on buybacks is out of alignment with its stated values and longstanding promises, prioritizing short-term financial gains over long-term economic resilience, worker and consumer trust, and basic animal welfare.
While executives and shareholders may benefit in the near term, the long-term costs are clear: weakened credibility, lost talent and customers, and years of unnecessary suffering for millions of hens. True leadership means investing in people, ethical supply chains, and lasting value, not financial engineering that comes at a profound moral and social cost.
When you do the math, Larry Page and Sergey Brin are $55 billion wealthier today than they would be had the limitation on stock buybacks that existed prior to 1982 not been modified.
One of us previously wrote on the tax treatment of stock buybacks. Prior to a rule change by the Securities and Exchange Commission in 1982, publicly traded corporations faced strict limits in the number of shares they could buy back. The 1982 rule change effectively gave corporations a choice: They could use their profits to buy shares on the open market, with no meaningful limit, or they could distribute their profits as dividends to their shareholders, taxable at the same rate as ordinary income.
The rule the Securities and Exchange Commission changed was related to insider trading; the SEC might not care about the tax consequences of share buybacks, but everyone else involved surely does. As noted in the post, the shareholders who don’t sell when a corporation buys back shares are the beneficiaries of the rule change:
To understand the impact of the SEC rule change, focus on the shareholders who don’t sell any shares in connection with a buyback. They’re the ones who reap the tax benefit. The selling shareholders were going to sell anyhow. We’re talking about publicly traded stock here. The decision to sell has nothing to do with the corporation’s decision to buy, and a selling shareholder has no idea who buys their publicly traded shares. The corporation doesn’t benefit either. It’s just shedding cash either way.
The concentration of American wealth—and the accompanying concentration of political power—now poses an existential threat to our democracy. Stock buybacks have made this situation measurably worse than it otherwise would have been.
But not all non-selling shareholders benefit from stock buybacks. If you own stock inside an IRA, the corporation’s decision whether to buy shares or issue dividends is not critical to you. You avoid an immediate income tax consequence either way. And if you don’t want a stock buyback to cause an increase in your ownership interest in the corporation, you can sell a few shares off, also without tax consequence, and create an economic result identical to that of a dividend.
The same applies to shares held by other retirement accounts, pension plans, university endowment funds, and other tax-exempt entities.
That leaves the ultra-rich—and especially the billionaires—as the main beneficiaries of stock buybacks. The benefits are enormous, and become ever larger as we move up the wealth scale.
The situation of Google co-founders Larry Page and Sergey Brin exemplifies the wealth concentrating impact of the SEC rule change. Alphabet, which became the publicly traded parent of Google in a 2015 reorganization, has bought back a lot of shares over the past 11 years. Page and Brin, the third and fourth wealthiest Americans, respectively, have a combined wealth totaling over half a trillion dollars. As of October 16, the two held a combined total of 14,960,019,745 shares of Alphabet stock—778,102,320 for Page and 717,917,425 for Brin—which they’d held at least since Google’s IPO in 2004 (adjusted for stock splits over that period).
Brin is leading the opposition to California’s Proposition 40, which would impose a one-time wealth tax of 5% on all residents of California as of January 1, 2026 with personal wealth exceeding $1 billion. Brin claims to have changed his state of residence to Nevada prior to that date, although it’s not clear whether the steps he took to accomplish that change were sufficient to avoid California residence for purposes of Proposition 40. To date, Brin has contributed over $100 million to groups opposing Proposition or supporting Propositions 41 and 42, which effectively would nullify Proposition 40.
Page, similarly, has moved to Florida, although it’s not clear if he has avoided being a California resident as of January 1, 2026.
If Proposition 40 passed and if Brin’s attempt to avoid California residency were unsuccessful, his tax liability would be in the $12 billion to $14 billion range. His co-founder Page would face a slightly higher tax liability under Proposition 40. Their total liability would be around $28 billion, give or take a few billion.
I was curious how Page and Brin’s prospective Proposition 40 tax liability compares with the wealth they now hold that’s attributable to the 1982 SEC rule change. Would the one-time tax recoup the windfall bestowed on them by the SEC rule change?
To determine that windfall, we figured that without the rule change the profits used by Alphabet to buyback shares would instead have been distributed as dividends and that the dividends would have been taxable as ordinary income. Yes, the federal tax rate applicable to dividends was reduced in 2003 to equal the long-term capital gains rate, but analyzing the counterfactual of “if there were no SEC rule change” points to the assumption the tax rate applicable to dividends would not have been reduced. Because of the SEC rule change, there was not much point for anyone to oppose lowering the tax rate applicable to dividends in 2003. Corporations could protect their shareholders from the higher rate by buying back stock instead of issuing dividends.
Absent the SEC rule change, then, the revenue cost of a reduction in the tax rate applicable to dividends would have posed a much larger obstacle to enactment. Would the rate nonetheless have been reduced? We’ll never know. But since we’re exploring the potential windfall to Page and Brin attributable to the SEC rule change, the higher of the two possible tax rates on dividends was the logical choice.
To determine the savings to Brin and Page, we calculated the change in their percentage ownership of Alphabet that would have resulted from each stock buyback, beginning with the first stock buyback in 2015, had the amount used in the buyback instead been distributed as a dividend, followed by Page and Brin paying federal and state income tax on the dividend, then purchasing additional Alphabet shares with the after-tax proceeds of the dividend. For simplicity, we assumed a total 50% US and California rate for each year during the period. The actual annual rate during the period, factoring in the full federal deductibility of state income tax prior to 2018, would have been slightly higher.
Under this alternative scenario, Page and Brin would now hold 10.9% of the outstanding shares of Alphabet, some 1.3 percentage points less than the percentage they currently hold.
When you do the math, Page and Brin are $55 billion wealthier today than they would be had the limitation on stock buybacks that existed prior to 1982 not been modified and had dividends continued to be considered ordinary income for federal income tax purposes. [And if you assume the federal rate would have been reduced to the capital gains rate in 2003, they’re still $41 billion wealthier today by virtue of the 1982 SEC rule change.]
Put another way, about 10% of their obscene combined wealth of over half a trillion dollars has been derived from one tax giveaway. And—it’s important to note—that tax giveaway wasn’t even delivered by duly elected members of Congress. Rather, it was ordained by unelected regulators (or, really, anti-regulators) at the SEC.
If Proposition 40 passes and Page and Brin are required to pay the one-time tax, they’ll still be $25 billion ahead. Don’t feel too bad for them.
Page and Brin likely are the most extreme examples of how the 1982 SEC rule change conferred massive additional wealth on the wealthiest Americans. But they’re far from the only examples. Meta, Oracle, Nvidia, and Dell all have distributed tens of billions of dollars in buybacks. Apple has bought back nearly half its shares through stock buybacks over the past decade. In total, stock buybacks have been running in the $1 trillion per year range and may hit $1.5 trillion this year. Today’s billionaires undoubtedly are sitting on several hundred billion dollars of additional wealth courtesy of stock buybacks.
The concentration of American wealth—and the accompanying concentration of political power—now poses an existential threat to our democracy. Stock buybacks have made this situation measurably worse than it otherwise would have been. We can’t do much about the damage that’s already been done. But we could avoid further damage.
This piece was first published on Substack.
Nvidia, led by the eighth-richest person in the world, boosted its existing buyback program by $150 billion, bringing the total to $235 billion.
The tech behemoth and chipmaker Nvidia on Monday announced the largest-ever stock buyback increase in US corporate history as its profits continue to explode due to massive spending on artificial intelligence data centers, which have drawn increasingly intense grassroots opposition nationwide.
Nvidia said its board "has authorized an additional $150 billion under the company’s existing share repurchase program, increasing the total remaining amount authorized to $235 billion." Jensen Huang, Nvidia's CEO and the eighth-richest person in the world, said his company's "growth is being driven by a once-in-a-generation platform shift to AI and accelerated computing," adding that Nvidia's "cash generation gives us the capacity to invest in the technologies that advance this transformation and return capital to shareholders."
Stock buybacks reduce the number of a company's shares outstanding on the public market and boosts earnings per share, typically resulting in a stock price increase and a wealth boost for shareholders and executives who receive stock-based compensation. Nvidia's stock price jumped by around 3% following Monday's announcement.
Critics argue that corporate spending on share repurchases amounts to stock price manipulation that diverts resources from more productive uses of capital, such as increasing worker pay and research and development. Buybacks, which were effectively illegal until 1982, have surged to record levels in recent years, fueled by massive tax cuts that President Donald Trump signed into law during his first White House term.
“The huge tax cuts corporations received from the 2017 Trump-GOP tax law–which were supposed to be used to increase employee pay and business investment—have instead been wasted on trillions of dollars of stock buybacks,” David Kass, executive director of Americans for Tax Fairness, said in June. “Stock buybacks widen economic inequality by making already wealthy shareholders even richer."
The Financial Times noted that Nvidia's buyback increase "beats Apple’s record $110 billion, set in 2024, for the largest in US corporate history."
Nvidia is one of the chief beneficiaries of the AI data center boom that has sparked protests and sustained, bipartisan opposition across the US.
"Nvidia’s chips are the centerpiece of giant AI data centers, and demand for those chips has become a barometer of the AI boom," The New York Times reported last month. "Other technology companies have been buying tens of billions of dollars’ worth of those chips, making Nvidia the most valuable public company in the world, with a market capitalization of about $5 trillion."
Nvidia's profits more than doubled in the second quarter of 2026 compared to the previous year, surging to nearly $60 billion.
Low-Wage 100 CEOs have raised nary a peep about ICE attacks on their employees or the gutting of our social safety net. And, with few exceptions, they have obediently rolled back DEI programs.
Low-wage US workers have faced multiple rising threats to their economic and personal security over the past year.
Aggressive Immigration and Customs Enforcement (ICE) actions have terrorized immigrant workers, who are disproportionately represented at the bottom of the corporate ladder. Congress approved the largest cuts in history to public assistance programs that millions of low-wage workers have to rely on to get by. And the Trump administration has attacked diversity, equity, and inclusion (DEI) programs designed to expand opportunities for disadvantaged employees.
How have the largest employers of low-wage workers responded to these threats? This year’s edition of the annual Institute for Policy Studies Executive Excess report takes a look by zeroing in on the 100 S&P 500 firms with the lowest median wages, a group we’ve dubbed the “Low-Wage 100.” The country’s most profitable retailers, fast food chains, and hospitality firms dominate the list.
Our key finding: Low-Wage 100 CEOs have raised nary a peep about ICE attacks on their employees or the gutting of our social safety net. And, with few exceptions, they have obediently rolled back DEI programs.
By looking the other way as low-wage workers face surging threats, corporate CEOs have shown even more clearly that we cannot rely on them to voluntarily do the right thing.
How did these corporate leaders choose to deploy their vast political power instead? Passage of the July 2025 budget bill was a top priority. This legislation will throw millions of Americans off Medicaid and the Supplemental Nutrition Assistance Program (SNAP) to pay for more tax cuts for the rich and a massive increase in ICE funding.
Under the bill’s reduced top marginal tax rate, chief executives will be able to take home an even greater share of their fat paychecks. In 2025, average CEO compensation within the Low-Wage 100 hit $17.5 million. By contrast, the group’s average median worker pay sat at just $36,571 and their average CEO-worker pay gap came to 614 to 1.
We reviewed public statements about this budget legislation by Low-Wage 100 firms and the corporate lobby groups that represent them. Each statement cheered the law’s tax cuts, which will overwhelmingly benefit the wealthy. The International Franchise Association even praised the doubling of the estate tax exemption, a tax break that will benefit less than 0.2% of the population.
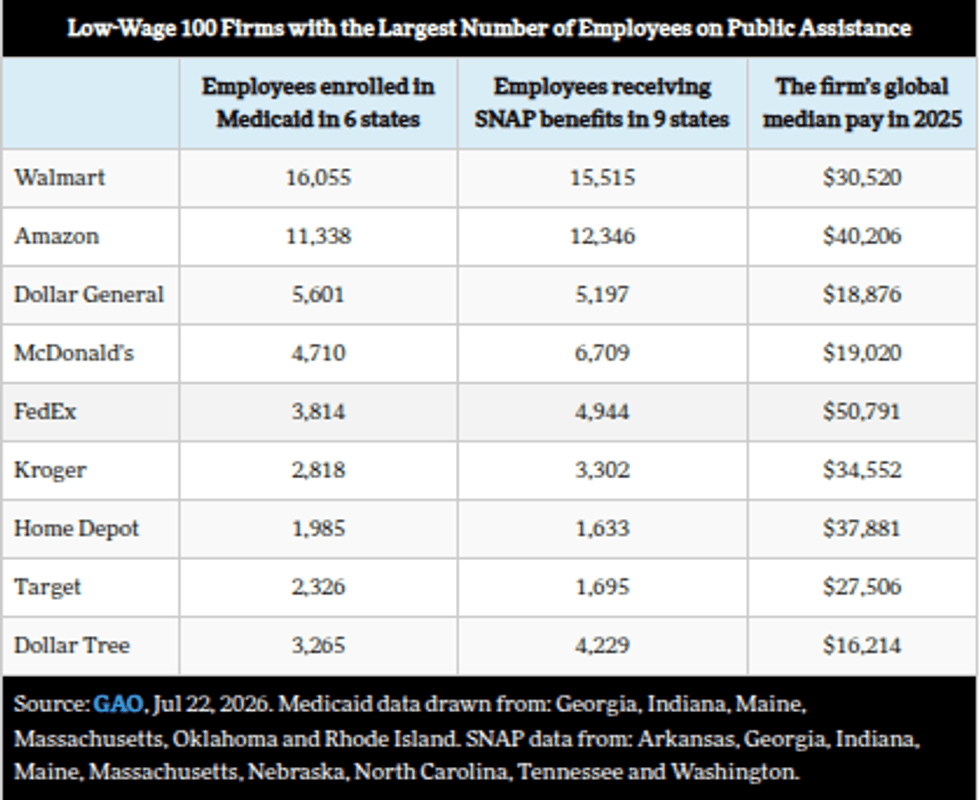
Not one statement expressed concern about the law’s drastic Medicaid and SNAP cuts. A recent Government Accountability Office report lists the top employers of workers receiving Medicaid and SNAP in a sampling of states where this information is available. Low-Wage 100 firms dominate the lists.
Given past trends, Low-Wage 100 CEOs’ muted response to the increased threats against their employees is hardly a surprise. The pandemic opened the eyes of many Americans to the essential value of frontline low-wage workers. But even that national crisis did not lead to more equitable sharing of corporate wealth.
Between 2019 and 2025, the Low-Wage 100’s average CEO pay rose 41.4%, double the 20.7% increase in their average median worker pay.
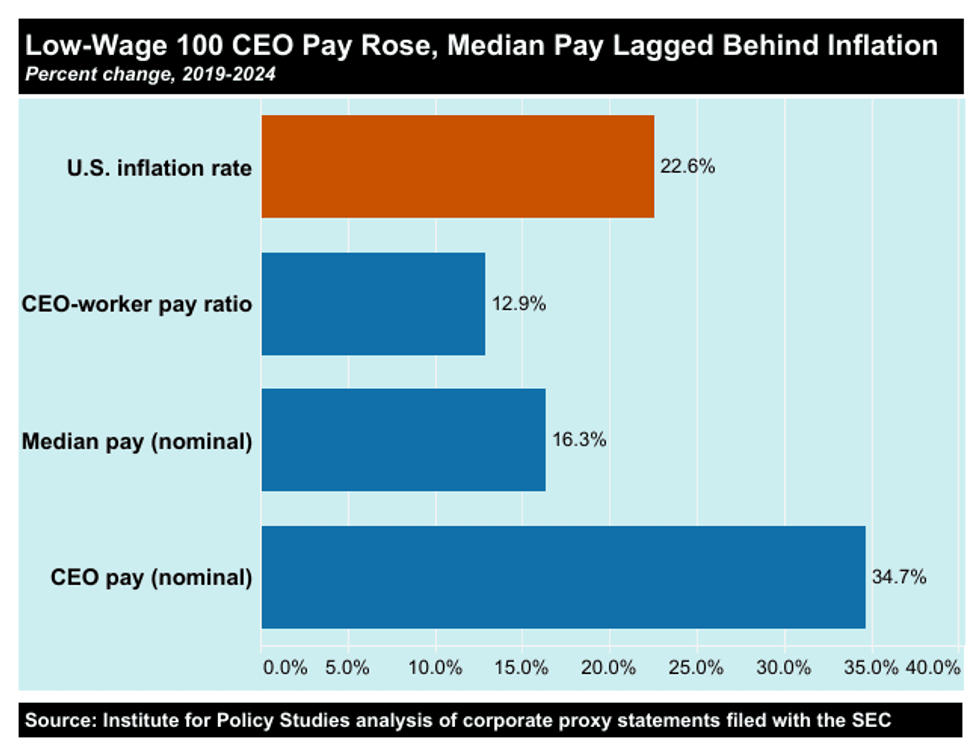
A technical note: we did not adjust these figures for US inflation because median pay figures in corporate SEC filings are based on a company’s global workforce. But many Low-Wage 100 firms have the vast majority of their employees in the United States. In fact, that’s the case for 5 of the 10 Low-Wage 100 corporations with the lowest median pay (Ross Stores, Ulta Beauty, TJX, Yum! Brands, and Dollar Tree).
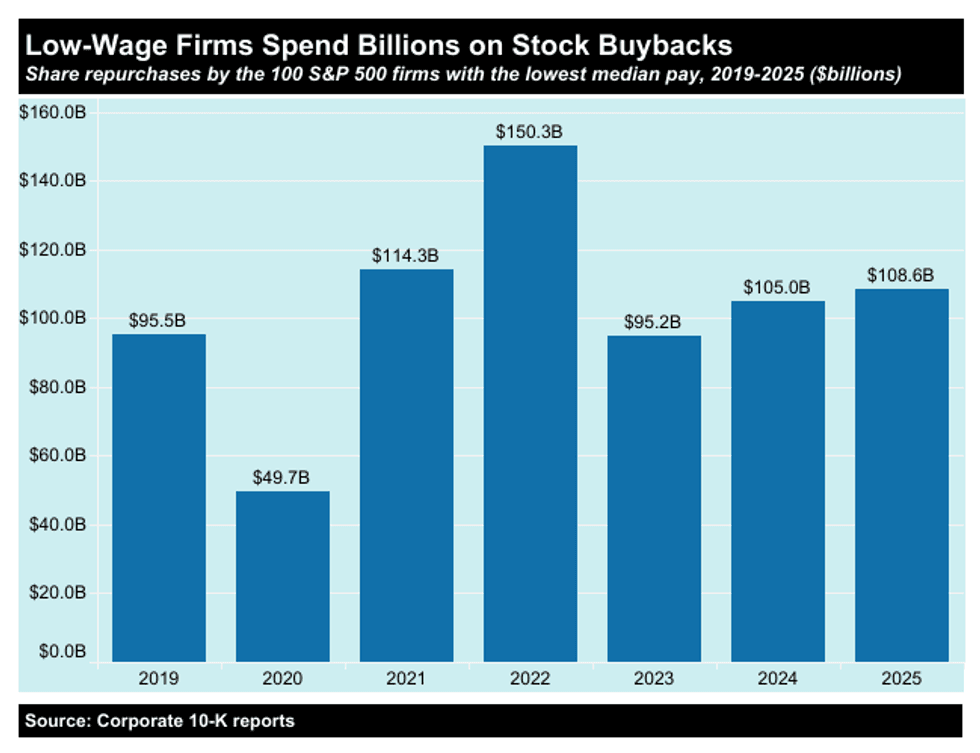
To further enrich their wealthy executives, Low-Wage 100 firms have spent over $718 billion repurchasing their own stock over the past seven years. This formerly illegal financial maneuver artificially boosts the value of a company’s shares and, in the process, pumps up the value of the stock-based compensation that makes up about 80% of corporate CEO compensation.
Every dollar spent on buybacks represents a dollar not spent on worker wages or long-term productive investments. The Lowe’s home improvement store’s $46.8 billion expenditures on buybacks over the past seven years could have covered the cost of a $24,235 bonus for each of their 276,000 employees every year during that period. Median pay at Lowe’s in 2025: $37,371.
The Low-Wage 100 represent a business model designed to deliver staggering personal gains for top executives by squeezing their workers. This predominant model is shredding our social fabric and threatening our democracy. We clearly need to build worker power and raise the minimum wage to a living wage. But to solve this problem we also need to curb runaway CEO pay.
Governments at all levels should explore options for leveraging tax policies and procurement and subsidy policies against executive excess. These policy solutions have serious bipartisan potential.
For instance, one survey found that 89% of Democratic and 71% of Republican likely voters support a tax hike on corporations that pay their CEO over 50 or more times what they pay their median employees. A bipartisan provision in the pending Senate defense authorization bill would bar military contractors from engaging in CEO pay-inflating stock buybacks.
Congress should also increase the existing 1% stock buybacks tax, ideally to a level high enough to discourage this activity. But even if companies continued the wasteful practice, hiking this tax would generate additional revenue for combatting inequality. If a 4% buyback levy had been in place between 2023 and 2025, the Low-Wage 100 would have owed approximately $9.3 billion in additional federal taxes.
By looking the other way as low-wage workers face surging threats, corporate CEOs have shown even more clearly that we cannot rely on them to voluntarily do the right thing. Lawmakers must take responsible action to narrow our dangerous economic divides.
A new report shows that Walmart could have funded a nearly $4,000 bonus for every single one of the company's employees with the amount of money it spent buying back its own stock last year.
A report published Thursday shows that the top 100 lowest-wage corporations in the US pay their CEOs 614 times more than their median workers on average while also pumping hundreds of billions of dollars into stock buybacks, which further boost the wealth of top executives and rich shareholders.
The new report, released by the Institute for Policy Studies (IPS), examines the 100 corporations in the S&P 500 index that pay their median workers the least—a list that includes Walmart, Amazon, Target, DoorDash, and Home Depot. Between 2019 and 2025, the IPS report shows, the "Low-Wage 100" spent a combined $718 billion on stock buybacks.
IPS characterizes share repurchases as "a financial maneuver that artificially inflates CEOs’ stock-based pay and siphons resources out of worker wages and long-term investments."
"Walmart ranked No. 1 in buyback spending among Low-Wage 100 firms in 2025," the report observes. "The giant retailer spent $8.1 billion on share repurchases—a sum that could have funded a $3,851 bonus for each of the firm’s 2.1 million employees."
The CEOs at the Low-Wage 100 have seen their compensation rise by over 41% on average—without adjusting for inflation—since 2019, more than double the increase that the companies' median workers have seen during the same period, lagging behind rising costs.
"Average CEO compensation within the Low-Wage 100 hit $17.5 million in 2025. The group’s average median worker pay sat at just $36,571 last year," IPS found. "The average CEO-worker pay ratio of Low-Wage 100 firms has widened from 574 to 1 in 2019 to 614 to 1 in 2025. Seventeen of the 100 corporations reported pay ratios of 1,000 to 1 or higher."
The company with the highest CEO-worker pay ratio in 2025 was Lumentum, which paid its top executive 2,884 times as much as its median worker last year.
"Over the past year," the IPS report notes, "the CEOs of the Low-Wage 100 pocketed huge paychecks while looking the other way as their employees grappled with fears of ICE actions, the loss of vital healthcare and food assistance programs, and attempts to roll back key protections against racial and gender discrimination."
Far from wielding their power and influence to advocate on behalf of their own employees, IPS observed, the 100 leading corporations deployed their armies of lobbyists to push "tax cuts for the wealthy and big corporations in the One Big Beautiful Bill Act, legislation that slashed Medicaid and SNAP programs on which many of these firms’ employees rely."
“The Low-Wage 100 includes many of the world’s most influential CEOs,” said Sarah Anderson, director of the Global Economy Project at IPS and lead author of the new report. “They could be using their political and economic clout to defend their workers against multiple threats. Instead, at this precarious moment in our democracy, they’ve chosen to remain silent.”
IPS concludes its report by recommending that lawmakers pursue three policy solutions: Increasing taxes on companies with large CEO-worker pay gaps, expanding the excise tax on stock buybacks, and "leveraging government contracts and subsidies" to force changes at major corporations.
"A bipartisan provision in the pending Senate defense authorization bill would bar military contractors from engaging in stock buybacks," the report notes. "This builds on modest Biden administration progress to use the power of the public purse to rein in CEO pay. But governments at all levels could be doing much more to leverage this power against executive excess."
"Seeing such strong numbers coupled with the mass layoffs at Xbox is not sitting right with many," wrote one tech journalist.
President Donald Trump has touted his massive corporate tax breaks in 2017 and 2025 not just as handouts to the rich, but as boons for their employees, who could expect to see rising wages and job growth in the coming years.
But one of the policy's biggest beneficiaries, Microsoft, just announced it was laying off thousands of employees in a move described as "cost-cutting," even though the company has spent tens of billions of dollars buying back its own stock.
When Trump's 2017 tax law reduced the corporate tax rate from 35% to 21%, Americans for Tax Fairness estimated that the company was saving about $16.5 billion per year.
The One Big Beautiful Bill Act, passed last July, rewrote rules to benefit companies investing in artificial intelligence by allowing them to deduct the cost of data centers and other equipment up front rather than spreading the deductions out over time, and introduced new deductions for research and development expenses.
For Microsoft, which pledged roughly $80 billion globally toward AI data center investment last year, that could translate to up to $16.8 billion in near-term federal tax savings.
The added windfall has been great for Microsoft shareholders. From 2018-25, the company returned roughly $139.5 billion to shareholders through stock buybacks since the Trump-GOP tax cut took effect, according to shareholder reports.
In the first nine months of fiscal year 2026, the first since the new tax breaks went into effect, the company bought back another $13.3 billion, an acceleration from the previous year, according to a form filed with the US Securities and Exchange Commission.
At the same time as the company is ramping up AI investment, however, it is laying off employees.
On Monday, the company announced that it was shedding roughly 2% of its global workforce, eliminating about 4,800 jobs—mostly in its Xbox division—as it allocates more money and resources to the AI arms race.
They are among the more than 20,000 Microsoft employees who have been shown the door since 2025. Additionally, thousands more employees took voluntary buyouts this spring.
Microsoft executive Amy Coleman attributed the cuts to a changing technological landscape.
"Our customers’ needs are shifting, the business models that serve them are shifting, and that means the work itself—what we do, where we focus, and how we’re organized—has to transform too,” she said. “Companies don’t get to choose whether their industry changes; they only get to choose whether they change with it."
She also stressed that workers were “not being replaced by AI.”
But Eddie Makuch, a writer at GameSpot, noted that the company has been doing terrifically, and despite falling share prices over the past year, remains "the No. 4 biggest company on Earth with a market cap of more than $2.8 trillion."
"Microsoft stockholders might not have been happy with the company’s share price falling, but for the past quarter alone, Microsoft paid out $10.2 billion to shareholders via dividends and share repurchases," he wrote. "These are signs of strength and health for Microsoft. Xbox is a very small piece of Microsoft’s overall business, but seeing such strong numbers coupled with the mass layoffs at Xbox is not sitting right with many."
"It’s shameful that wealthy shareholders and executives are profiting while American families pay through the roof for groceries, gas, and rent."
A group of Senate Democrats on Thursday introduced legislation to hike taxes on US corporations that buy back their own stock as a new analysis estimated that major companies have spent nearly $5 trillion on share repurchases since President Donald Trump's 2017 tax cuts took effect.
The Democratic legislation, titled the Stock Buyback Accountability Act of 2026, would increase the current stock buyback excise tax from 1% to 4%, a change that experts say would raise around $240 billion in revenue over a 10-year period and likely dissuade some companies from engaging in buybacks, which artificially inflate share prices and further enrich shareholders and executives.
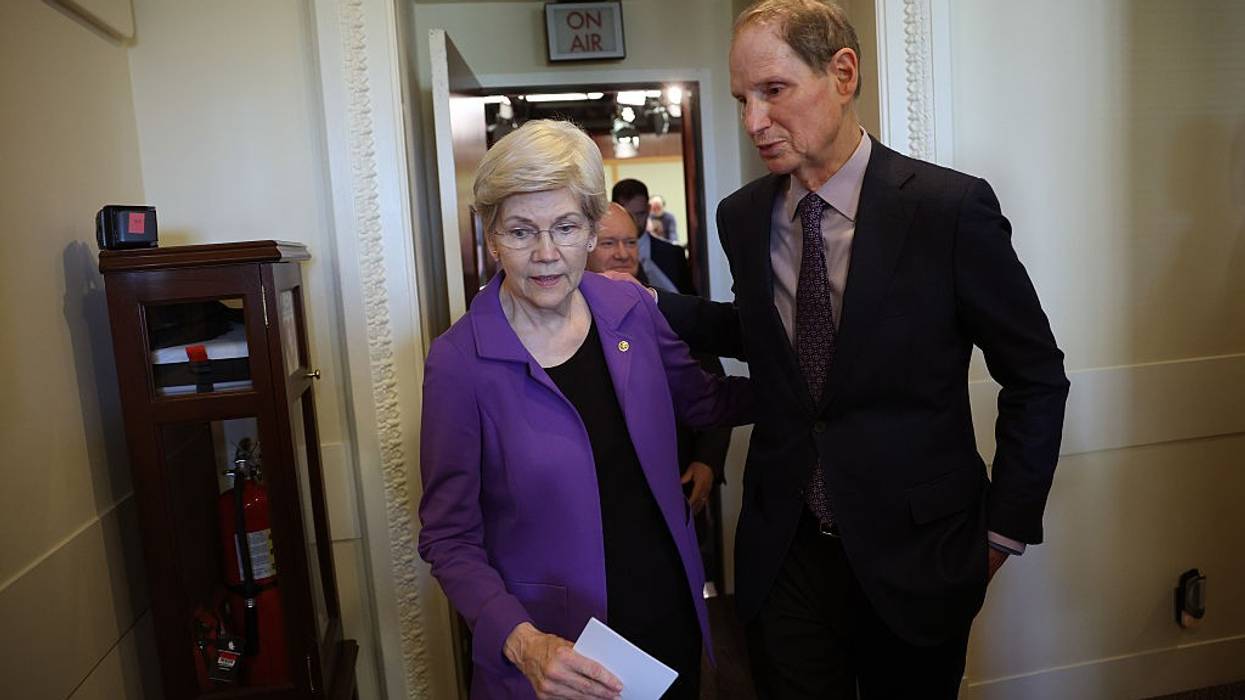
“After getting massive tax breaks from Donald Trump and Republicans in Congress, giant corporations are turning around and delivering stock buybacks at record highs,” said Sen. Elizabeth Warren (D-Mass.), who joined Senate Minority Leader Chuck Schumer (D-NY) and Sen. Ron Wyden (D-Ore.) in introducing the new bill to rein in what they called corporate America's "stock buyback bonanza."
“It’s shameful that wealthy shareholders and executives are profiting while American families pay through the roof for groceries, gas, and rent," said Warren. "This bill is an important step forward in making corporations pay their fair share."
The legislation's release coincided with an analysis conducted by the advocacy group Americans for Tax Fairness (ATF), which found that 100 of the largest corporations in the US have spent a combined $4.8 trillion on stock buybacks in the eight years since enactment of the 2017 Trump-GOP tax law.
"Every time Republicans sweep an election they shower corporations with new tax breaks, and then corporations shower their wealthy shareholders and executives with new stock buybacks."
Just 10 companies—Apple, Alphabet, Microsoft, Meta, Bank of America, JPMorgan Chase, Wells Fargo, Oracle, Nvidia, and Visa—were responsible for more than $2 trillion of the $4.8 trillion in total buybacks since 2017, ATF noted. The group estimated that, had the Stock Buyback Accountability Act been in place over the past eight years, the federal government could have raised around $200 billion in revenue from the 100 big corporations examined in the new analysis.
“The huge tax cuts corporations received from the 2017 Trump-GOP tax law—which were supposed to be used to increase employee pay and business investment—have instead been wasted on trillions of dollars of stock buybacks,” said ATF executive director David Kass. “Stock buybacks widen economic inequality by making already wealthy shareholders even richer. We need the Stock Buyback Accountability Act now more than ever.”
Stock buybacks were effectively prohibited in the US until 1982, as they were considered a form of market manipulation. Over four decades later, in 2025, stock buybacks by American companies surpassed $1 trillion—a record high.
"Every time Republicans sweep an election they shower corporations with new tax breaks, and then corporations shower their wealthy shareholders and executives with new stock buybacks," Wyden, the top Democrat on the Senate Finance Committee, said in a statement Thursday. "We need to dial up the tax on these buybacks, and if corporations decide they’re better off investing in workers and long-term growth, that’s a great outcome.”
ATF noted in its analysis that "the resulting rise in stock price created by a buyback is not taxed unless the stock is sold."
"With the top 5% of households owning 70% of all stocks, that is a big benefit for wealthy investors, who prefer the unrealized income which comes from buybacks to the traditional corporate dividends that are paid out and taxed on an annual basis," the group observed.
"These companies want Americans to believe price spikes are simply the unavoidable result of global events, but their own executives are openly telling investors that volatility, conflict, and supply disruptions are good for business."
A Tuesday report from Groundwork Collaborative reveals how fossil fuel companies are not merely scoring windfall profits from President Donald Trump's illegal war with Iran, but also using that money to reward shareholders rather than providing relief to consumers.
The price of gas has soared since Trump attacked Iran without any congressional authorization in late February, going from an average of under $3 per gallon at the start of the war to $4.49 per gallon as of Tuesday.
As US drivers have paid more at the pump, however, fossil fuel firms have been concerned with paying out dividends and conducting stock buybacks expanding production to lower prices, Groundwork Collaborative's report finds.
Among other things, the report notes that ExxonMobil is on pace to deliver $20 billion worth of stock buybacks in 2026, even as CEO Darren Woods has insisted that the company's decisions on production will be "grounded in value, not volume."
Additionally, the report documents how Shell recently announced "another 5% dividend increase and more than $3 billion in buybacks," with CEO Wael Sawan describing the company's commitment to paying shareholders as "sacrosanct."
Chevron has pledged roughly $3 billion in quarterly stock buybacks, while also saying increasing dividends for shareholders is its "first and foremost" priority.
Chevron CFO Eimear Bonner, the report adds, recently revealed that the company has no plans to boost output in response to high energy prices, stating that "capital spending and production outlooks are consistent with previous guidance."
Lindsay Owens, executive director of Groundwork Collaborative, accused Big Oil of using Trump's illegal war as cover to keep prices high without taking any steps to reduce pain at the pump.
"These companies want Americans to believe price spikes are simply the unavoidable result of global events," said Owens, "but their own executives are openly telling investors that volatility, conflict, and supply disruptions are good for business. They are choosing buybacks over production, shareholder payouts over affordability, and corporate profiteering over the economic security of working families.”
The high fuel prices aren't being felt just in the US, but across the world.
Karthik Sankaran, senior research fellow at the Quincy Institute for Responsible Statecraft, explained in a Tuesday analysis how oil prices are hitting nations in the Global South particularly hard.
"A recent story in The New York Times described how the price for transporting corn into refugee camps in Somalia had doubled or even tripled, as had the price of water at diesel-powered public tubewells," Sankaran wrote. "Meanwhile, protests this week in Kenya against fuel price hikes have led to four deaths, and political and financial stresses are mounting across the continent."
Sankaran also pointed to problems in India, where "sharp jumps in the price of liquid petroleum gas have hit urban households hard, particularly those whose breadwinners work in small-scale industrial establishments."
Despite the actue global economic pain, energy experts who spoke with CNN on Tuesday expressed skepticism that the crisis would abate anytime soon, despite Trump's regular hyping of a deal to end the conflict.
Rory Johnston, an oil market researcher and founder of Commodity Context, told CNN that he wasn't buying optimism from commodities futures markets after Trump claimed to have made significant progress on an agreement with Iran.
"Nothing has fundamentally changed," Johnston said. "The strait remains closed."
Sultan Al Jaber, the CEO of Abu Dhabi National Oil Company, said that a deal to end the war wouldn't instantly bring energy prices back to where they were before the war began, estimating it could take months just to get 80% of the pre-war oil supply flowing through the Strait of Hormuz.
Dan Osborn, the independent US Senate candidate in Nebraska, needs a plan. And it's a plan that could and should be embraced in states and communities nationwide.
Here are some things to know about large corporations:
Dan Osborn, the Nebraska independent senatorial candidate, knows all this. It’s a good part of the reason he’s running for office, and he needs a plan. He knows this is a travesty, a disaster, a case of the rich and powerful trashing working people. As he puts it, “This isn’t left and right anymore, this is big versus little,” and he wants to do all he can to stop Tyson from killing 3,200 jobs in Lexington, Nebraska.
Osborn has called for the enforcement of the 1921 federal Packers and Stockyards Act, which was designed to promote competitiveness in the livestock, meat, and poultry industries and prohibit deception and fraud. He claims Tyson broke the law by closing its Lexington, Nebraska, plant instead of selling the facility to a competitor. The closure was “destroying 5 percent of America’s beef processing capacity,” Osborn argued, which will drive up prices instead of maintaining a competitive market.
In just the last quarter of 2025, Tyson conducted more than $200 million in stock repurchases which did nothing to improve production and nothing at all to protect the workers.
Senate Minority Leader Chuck Schumer joined the fight by demanding that Agricultural Secretary Brooke Rollings use the authority she has under the Act to block the Lexington closure. But, on January 21, 2026, the plant shut down anyway. In fact, no plant closing has ever been stopped by this act.
If the law is not enough to protect these devastated workers and communities, where can Osborn find leverage to help them?
It is really hard to stop a plant closing in the United States of America. Of the millions of mass layoffs over the past three decades, I’m having trouble finding any that have been reversed (although my friends at the Teamsters Union say they have been successful on occasion.) There have been at least a handful of worker buyouts of facilities scheduled for shutdowns that kept them open for a time, but all I know about soon went under.
There is one point of leverage, however, that has yet to be used—federal contracts.
Large corporations love to dine at the federal trough, gobbling up as much taxpayer money as they can through federal grants and contracts. Tyson is no exception. It’s got its hands all over our tax dollars. In 2025, it received 170 federal awards for a total of $234 million. It also received, from 2018 to 2020, $727 million from the Pentagon to supply beef to the military. And those contracts have been renewed through today.
Mass layoffs are a heartless tool that ignores how critical stable employment is to families and communities.
What if Osborn promised that as senator, he would fight for a new federal regulation like this:
All corporations of 500 or more employees that receive taxpayer-funded federal contracts shall not be permitted to conduct compulsory layoffs of taxpayers. All layoffs must be voluntary based on financial incentives.
Wouldn’t that be fair and just? After all, voluntary financial incentives to leave a job are commonplace for executives. And it’s not just severance. The idea is that no one should be forced to leave. The financial incentive would need to be high enough to attract voluntary departures.
Is this proposal too radical for Nebraska?
No doubt, corporations and their political handmaidens would vigorously attack the proposal. Isn’t the key to a free society the right of business owners, large and small, to manage their own enterprises as they see fit? When the government intervenes to control hiring and firing, isn’t it stepping towards socialism, which history has shown is both a failure economically and a path towards totalitarianism? Wouldn’t such a proposal harm jobs, our economy, and democracy?
Osborn’s response could be simple: Corporations would be totally free to hire and fire at will—but not if they are taking taxpayer money. If they want our money, then they can’t force us out against our will. No compulsory layoffs!
We tested this idea and the corporate attacks in our survey of 3,000 Midwestern voters across Wisconsin, Michigan, Ohio, and Pennsylvania. About half of those voters supported the idea, with very low percentages opposed, even after being introduced to corporate attacks against the policy.
If they want our money, then they can’t force us out against our will. No compulsory layoffs!
Where would the money come from?
That’s where stock buybacks come in. In just the last quarter of 2025, Tyson conducted more than $200 million in stock repurchases which did nothing to improve production and nothing at all to protect the workers. They chose to pad the bonuses of Tyson executives and the portfolios of large Wall Street shareholders. It might have made instead a nice start on a worker buyout fund.
The proposal may sound radical, but nothing about this is pie in the sky. The Siemens Corporation in Germany agreed to a no-compulsory layoff proposal with its union, IG Metall, after it announced the layoff of 3,000 workers. As the result of negotiated settlement with the union, the workers could take voluntary financial buyout packages. But, none of the workers were forced to leave. And instead of the scheduled shutdown of five facilities, the company agreed to put in new products to keep the plants open.
Large corporations like Siemens and Tyson have enormous flexibility. They can rearrange production in countless ways. Unless pressured by the workers through their labor unions, they serve corporate needs first and subordinate those of workers. Mass layoffs are a heartless tool that ignores how critical stable employment is to families and communities. These companies have the financial power to fulfill the needs and interests of their employees, but they choose not to. But for Tyson, and so many companies today, all that matters is shoveling as much money as possible into the pockets of their wealthy executives and Wall Street investors. The workers be damned!
At this point, the Tyson workers and Dan Osborn know that the plant is not going to be reopened. But Osborn’s campaign could commemorate those workers by becoming the first politician in the nation to offer a realistic and potentially popular solution to this recurring nightmare:
No Compulsory Layoffs at Corporations That Receive Taxpayer Money!
The poverty wage business model that is so prevalent in Corporate America works spectacularly well for a handful of wealthy and politically powerful executives and shareholders. For the rest of us, not so much.
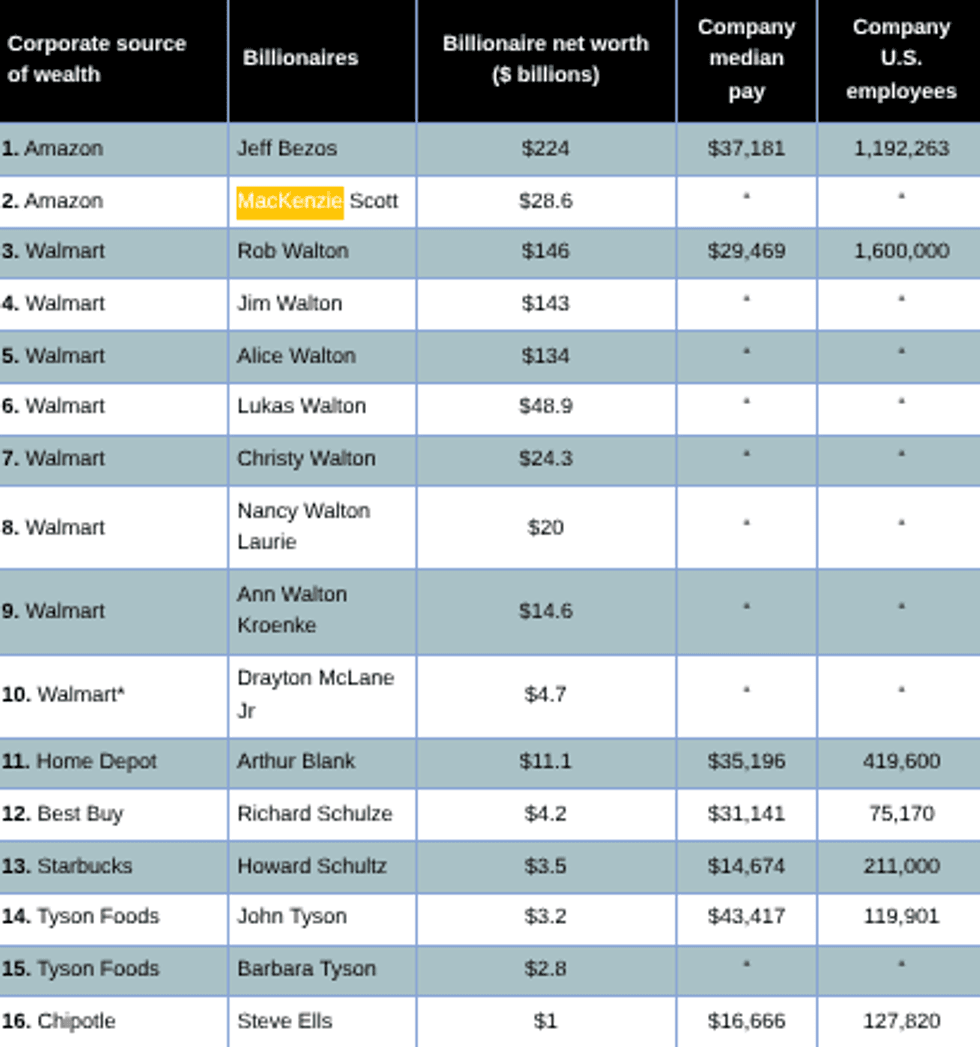
At least 16 US billionaires owe their wealth to one of America’s 20 largest low-wage employers—corporations where a significant share of workers earn so little they have to rely on public assistance.
Of these 16 billionaires, 8 are associated with Walmart. Amazon and Tyson Foods have two members of this elite club, while Home Depot, Best Buy, Starbucks, and Chipotle each have one.
For detailed data on wages and CEO pay at these and other leading low-wage corporations, see the recent Institute for Policy Studies report "America’s 20 Largest Low-Wage Employers and the Affordability Crisis." This article includes updated net worth data from the just-released Forbes 2026 Global Billionaires List.
Seven descendants of Walmart founder Sam Walton have accumulated their multi-billion-dollar fortunes off the backs of the giant retailer’s low-wage workers. His eldest son, Rob Walton, leads the pack, with $146 billion. Another billionaire, Drayton McLane, gained entry to this elite club by selling his grocery distribution business to Walmart for a significant share in the retailer.
When corporate resources are funneled into the pockets of those at the top while ordinary employees have to rely on public assistance, we are all subsidizing the executive mansions and private jets.
Median pay at Walmart, the largest US private sector employer, stood at $29,469 in 2024. That’s below the income limits for a family of three to qualify for Medicaid and Supplemental Nutrition Assistance Program (SNAP) food aid benefits. It’s nowhere near the $59,600 income level needed to afford the US average rent for a two-bedroom apartment.
In addition to median pay figures reported in corporate proxy statements, we gathered data from the small number of state governments that disclose corporations’ use of public assistance programs to subsidize their low wages.
In Nevada, Walmart had 4,574 employees, 29.3% of their employees in that state, enrolled in Medicaid in 2024. In four states (Colorado, Massachusetts, Illinois, and Michigan), Walmart had a total of 10,920 employees enrolled in the SNAP food aid program.
The media organization More Perfect Union points out that Walmart not only relies on SNAP to make up for the low wages they pay their workers, but they also benefit when people use food stamps to buy groceries in their stores. According to a Numerator survey covering the 12 months ending July 31, 2025, Walmart ranked No. 1 for SNAP benefit redemption, receiving nearly 26% of all SNAP dollars.
Since MacKenzie Scott received 4% of Amazon stock in her 2019 divorce settlement, the ecommerce goliath has had not one but two reps on the billionaire ranking. Scott has become a major philanthropist, but is still sitting on an estimated $28.6 billion. Her ex, Amazon founder and current Trump ally Jeff Bezos, came in fourth in the world in the Forbes list this year, with $224 billion.
Amazon’s typical employees are on another economic planet. Their median pay of $37,181 just barely exceeds the family-of-three income limits for Medicaid and SNAP. With half of Amazon employees earning less than that amount, a significant share of the company’s 1.2 million US employees no doubt have to rely on public assistance.
Indeed, the Nevada state government’s Medicaid report reveals that Amazon had 8,951 employees enrolled in that health program in that state in 2024, making up 48.4% of all of the firm’s employees in Nevada. In the four states that report SNAP enrollee data by employer, Amazon came in second after Walmart, with 9,633 employees receiving those benefits.
Home Depot co-founder and Atlanta Falcons owner Arthur Blank holds an estimated $11.1 billion. His fellow co-founder, Bernard Marcus, died on election day in 2024, after donating $9.4 million to the campaigns of President Donald Trump and other Republicans.
While ranking among the country’s lowest-paying companies, Home Depot has had plenty money to blow on stock buybacks. This is a financial maneuver that artificially inflates the value of a company’s shares—and the stock holdings of wealthy executives and stockholders.
The big-box chain spent $37.9 billion on share repurchases between 2019 and 2024. That sum would have been enough to give each of Home Depot’s 419,600 US employees six annual $15,039 bonuses. Home Depot’s median pay in 2024 stood at just $35,196—less than the $35,631 income limit for a family of three to qualify for Medicaid.
State government data show that Home Depot employees had a total of 2,213 employees enrolled in SNAP food aid in Colorado, Massachusetts, Illinois, and Michigan.
Longtime Starbucks CEO Howard Schultz has accumulated $3.5 billion in wealth off a company that paid its median earner just $14,674 in 2024. Employee discontent has sparked pro-union elections at more than 570 stores over the past four years. But the company has used various tactics to prevent workers from securing a first contract, including during a period when Schultz returned to his CEO post.
Schultz recently purchased a $44 million penthouse in Surfside, Florida, a state with zero personal income tax.
Taxing away excessive wealth could also encourage business models that share profits equitably with all employees.
Rounding out the low-wage billionaires list are the founders of Best Buy and Chipotle and two descendants of John Tyson, the founder of Tyson Foods, a meat processor with a sizeable immigrant workforce.
The poverty wage business model that is so prevalent in Corporate America works spectacularly well for a handful of wealthy and politically powerful executives and shareholders. For the rest of us, not so much.
When corporate resources are funneled into the pockets of those at the top while ordinary employees have to rely on public assistance, we are all subsidizing the executive mansions and private jets, the massive political spending, and all the other trappings of excessive wealth.
Lawmakers have introduced several tax proposals to curb the size of billionaire fortunes. Under current law, the ultra rich hold most of their wealth in stock and other financial assets that are not taxable until they are sold. In the meantime, they’re allowed to borrow against these assets to fund their lavish lifestyles and then pass their wealth on to heirs tax-free.
One federal bill to address that loophole, the Billionaires Income Tax Act, would impose an annual tax on billionaires’ gains from tradable assets like stocks, whether or not they sell the asset.
Several other proposals would tax billionaires’ accumulated wealth. For example, Sen. Elizabeth Warren (D-Mass.) and Rep. Pramila Jayapal (D-Wash.) are the lead advocates of the Ultra-Millionaire Tax Act, which would apply a 2% annual tax on the net worth of households and trusts between $50 million and $1 billion and a 3% tax on those with net worth above $1 billion.
Sen. Bernie Sanders (I-Vt.) and Rep. Ro Khanna (D-Calif.) recently introduced a slightly different model that would establish a 5% annual wealth tax on billionaires. This proposal is similar to a California state ballot initiative for a 5% one-time wealth tax on billionaire residents of that state.
Each of these proposals would raise massive revenue for public investments. At the same time, taxing away excessive wealth could also encourage business models that share profits equitably with all employees instead of extracting from those at the bottom to make wealthy executives and shareholders even richer.