

SUBSCRIBE TO OUR FREE NEWSLETTER
Daily news & progressive opinion—funded by the people, not the corporations—delivered straight to your inbox.
5
#000000
#FFFFFF
To donate by check, phone, or other method, see our More Ways to Give page.
Daily news & progressive opinion—funded by the people, not the corporations—delivered straight to your inbox.
"The need for responsible cryptocurrency regulation remains," said one anti-corruption advocate.
The US Senate voted not to advance a major cryptocurrency bill on Tuesday, heeding warnings from critics that it would fail to regulate the volatile financial asset effectively and would allow President Donald Trump to continue profiting lavishly from it with little oversight.
Earlier reports indicated that crypto industry darling Sen. Kirsten Gillibrand (D-NY) was trying to rally enough Democrats to support the GOP-led Digital Asset Market Clarity Act to get the 60 votes necessary to break the filibuster.
But by Tuesday afternoon, even Gillibrand herself had jumped ship. In what turned out to be a 50-49 vote against the legislation, she joined every other member of the Democratic caucus to vote against the Clarity Act. So did four Republicans—Sen. Susan Collins (Maine), Josh Hawley (Mo.), Jerry Moran (Kan.), and Thom Tillis (NC).
Democrats who voted against the legislation said that a revised version presented by Republicans on Sunday failed to meet their demands for rules to prevent Trump and other high-ranking officials from profiting from their cryptocurrency ventures while in office.
In 2025, Trump reported roughly $1.4 billion in crypto-related income, including hundreds of millions from his family’s crypto exchange World Liberty Financial (WLF) and from sales of his $TRUMP meme coin.
"President Trump, his children, and his Cabinet are making billions of dollars in the crypto space, in part from bilking everyday Americans out of their hard-earned money," said Sen. Elissa Slotkin (D-Mich.) in a post to social media. "I cannot in good conscience vote for any legislation that codifies that behavior from public officials."
Sen. Ruben Gallego (D-Ariz.), who negotiated the bill's ethics language with Tillis, said in a statement that "instead of spending their time twisting themselves into knots to appease President Trump, Republicans should have worked more closely with Senate Democrats to craft a bill that could pass with strong ethics provisions.”
Reuters reported in August that crypto-aligned super political action committees have spent nearly $190 million during this election cycle to support industry-friendly candidates.
"It’s no secret that they are seeking to ram a bill through Congress based upon not the merits of the bill, but the threat that they will spend even more money in elections against people who vote against it,” said Sen. Chris Murphy (D-Conn.), who voted against the bill.
Ella Fanger, corporate power policy adviser for the progressive activist group Demand Progress, said in a statement that Democrats "dodged a bullet by refusing to go along with the dangerously weak bill that Trump and the crypto industry have asked for," though she questioned why Gillibrand was advocating for the measure up to the last minute, "particularly at a time when she is claiming to oppose Trump's corruption."
The Clarity Act is stalled for now and likely won't be revived until after the November midterms. But Scott Greytak, deputy executive director of Transparency International US, said that "the need for responsible cryptocurrency regulation remains."
"Before bringing it back, Congress must confront two fundamental failures of the legislation," he said in a statement. "First, it must stop President Trump—and future presidents and other public officials—from profiting from the crypto industry while shaping and enforcing its rules. President Trump’s crypto interests make the stakes clear: Public officials who write or enforce the rules for crypto shouldn’t be allowed to cash in on it."
"Second, Congress must ensure that law enforcement can follow the money wherever it moves," he continued. "Unless the bill applies strong anti-money laundering and sanctions rules across the crypto market, scammers, drug cartels, terrorist financiers, sanctions evaders, and corrupt officials will exploit the weakest parts of the system to move and hide their money."
Sen. Elizabeth Warren (D-Mass.), one of the Clarity Act's most outspoken critics, said, “Let’s make sure that we do not pass a crypto bill that will let Donald Trump continue to rake in billions of dollars in crypto profits while working families across this country struggle to deal with higher prices and an economy that gets worse by the day."
"It may be the most brazen act of self-dealing our financial system has ever seen."
After President Donald Trump and the Republican Party revealed what they called their "last, best, and final offer" of ethics restrictions for cryptocurrency regulation, US Sen. Elizabeth Warren stood on the Senate floor Monday evening with a counteroffer: the Ending Presidential Corruption in Banking Act, whose passage she said was crucial for guarding against Trump using his very own crypto bank as a financial hub for his "web of corruption."
The GOP's "offer" on ethics pertains to the Digital Asset Market Clarity Act, also known as the Clarity Act, which would create a regulatory framework for the crypto market and which the Senate is expected to vote on Tuesday. The Republicans agreed to a proposal from Sens. Ruben Gallego (D-Ariz.) and Thom Tillis (R-NC), which would give state attorneys general the ability to sue if federal officials create or sponsor digital assets while holding office.
But, said Warren (D-Mass.), the proposal ensures the law "could never be enforced against Donald Trump because it gives his political appointees the power to turn off enforcement of these ethics provisions."
It also "contains major loopholes designed to allow President Trump to keep earning billions of dollars from his crypto businesses, including World Liberty Financial... and his new bank," said the senator.
Speaking for over 12 minutes on the Senate floor Monday evening, Warren pointed to the decision last month by the Office of the Comptroller of the Currency (OCC), whose leader was appointed by Trump, to grant approval for a federal bank charter for World Liberty Financial, a crypto investment fund that is owned in large part by the president himself and his family.
The Trump family owns 38.25% of the bank, while an investment fund backed by the national security adviser of the United Arab Emirates and the brother of UAE President Mohamed bin Zayed Al Nahyan owns 49% of the venture.
In January, Warren had called on the OCC to delay its review of World Liberty Financial's charter application until Trump divested from the venture.
"Donald Trump is now the first president in history to own and oversee his own bank. It may be the most brazen act of self-dealing our financial system has ever seen," said Warren. "With a bank charter, World Liberty will be able to operate nationwide, offer families and businesses financial products and services, and enjoy the credibility that comes with the federal government’s stamp of approval."
Trump is the first President in history to own and oversee his own bank.
We're live on the Senate floor to say enough is enough with Trump’s crypto corruption.
We need to pass the Ending Presidential Corruption in Banking Act now.https://t.co/wFurTSS0n1
— Elizabeth Warren (@SenWarren) September 14, 2026
But while the president is determined to have his family's crypto venture recognized as a bank—one whose USD1 stablecoin token sales earned Trump $527 million in proceeds last year, according to financial disclosures—the senator warned that World Liberty Financial's charter could "drive even greater profits for President Trump and his family" while serving as "a new vehicle for billionaires, corporations, and foreign countries to bribe him."
With his own bank, the president could charge transaction fees and generate interest by "investing the cash deposited with World Liberty in exchange for the USD1 stablecoin," said Warren, noting that a similar scenario played out last year during a trial run, before the company was granted preliminary approval for the bank charter.
"MGX, a UAE state-owned investment fund, made a $2 billion investment in the crypto exchange Binance," she said. "Instead of using a fiat currency like the US dollar or the UAE dirham to purchase stock in Binance, MGX paid Binance using USD1, cutting Trump into the deal."
Warren suggested sardonically that it was likely just "coincidental" that Trump pardoned the founder of Binance, who had pleaded guilty to failing to guard against money laundering.
Companies affiliated with World Liberty Financial have also reportedly sold millions of dollars in tokens that conducted business with hackers sponsored by North Korea and sanctioned money-laundering entities in Russia, and accepted $100 million from a businessman reportedly under investigation in the UK for money laundering.
"Now with Trump’s federal bank charter, we could see more and more of this," said Warren.
The top officials associated with the bank would also likely have led to the charter application being "flatly denied under any previous administration" due to a lack of competence and previous misconduct, said Warren, pointing to bank president Zachary Witkoff, the son of Middle East envoy Steve Witkoff, who "has never worked in a senior banking role."
Warren called on her colleagues to reject the Clarity Act and instead pass her bill in order to terminate "this corrupt bank charter."
"Unfortunately, my Republican colleagues want to move in the opposite direction," she said. "They seem intent on furthering President Trump’s corruption. Look no further than the Senate’s first order of business after August recess. Is it a bill to make life more affordable for American families? No. Is it a bill to end Trump’s dangerous war in Iran? No. It’s a bill that would juice the value of President Trump’s crypto empire, and reward the crypto billionaires who have facilitated his corruption."
"Instead of further enriching the president, Congress should curb his corruption," Warren added. "Let’s start by passing my bill, the Ending Presidential Corruption in Banking Act."
Crypto industry darling Sen. Kirsten Gillibrand is trying to bring Democrats on board despite warnings that a new version of the bill "still fails to address President Trump’s unprecedented profiteering."
Democrats in the US Senate may be on the verge of helping Republicans pass a cryptocurrency bill that could enable President Donald Trump's self-enrichment.
On Tuesday, the Senate will hold a key vote on whether to advance the Digital Asset Market Clarity Act, a bill drafted hand-in-glove by the crypto industry that fulfills many of its key objectives, amid a $190 million lobbying blitz.
The bill, commonly called the Clarity Act, establishes what would be considered the first federal regulatory framework for cryptocurrency, which is much looser than the rules that govern stocks and other securities, with fewer disclosure requirements and investor protections.
In May, Sen. Elizabeth Warren (D-Mass.), the top Democrat on the Senate Banking Committee, warned that this bill would help to "turbocharge" President Donald Trump's "crypto corruption."
"In just one year in office, the president and his family have raked in at least $1.4 billion in gains from crypto deals alone, and yet this bill stunningly includes zero provisions to prevent that," Warren said.
As Politico reported Monday, Sen. Kirsten Gillibrand (D-NY), one of Congress’ biggest crypto supporters, is privately urging others in her party to back the legislation and break the filibuster.
According to the Government Transparency Project, Gillibrand is Congress' top recipient of campaign donations from employees in the crypto sector. And as Andrew Perez noted on Tuesday for Zeteo, Gillibrand's 22-year-old son "recently received startup backing from a crypto billionaire."
Politico said there were about a dozen Democrats in the chamber who had "signaled openness" to voting for the legislation, though it did not specify who they were.
Two potentially worth watching are Sens. Ruben Gallego (D-Ariz.) and Angela Alsobrooks (D-Md.), the only two Democrats who voted to advance the initial, even less restrictive version of the bill out of the Senate Banking Committee.
Trump reported roughly $1.4 billion in crypto-related income in 2025, including hundreds of millions from his family's crypto exchange World Liberty Financial (WLF), which is funded by the United Arab Emirates' national security adviser, Tahnoun bin Zayed Al Nahyan, and from sales of his $TRUMP meme coin, a kind of digital collectible that Trump's own Securities and Exchange Commission has acknowledged typically has “no use."
Last month, WLF received preliminary approval from a Trump-appointed regulator to become a federally regulated bank, leading to warnings from anti-corruption watchdog groups that the institution could create a new vehicle for Trump to accept bribes from business interests and foreign governments seeking his favor.
The Trump family reportedly owns about a 38% stake in the holding company for the bank, while Al Nahyan, who is also the brother of the UAE's president, owns about 49% of the venture.
The Clarity Act will require 60 votes to advance in the Senate, meaning that seven Democrats will have to get on board, assuming all Republicans vote yes. Some have demanded that the bill address some of its shortcomings, including provisions that would allow Trump to continue profiting.
On Sunday, with the vote less than 48 hours away, Senate Republicans and the White House unveiled a new version of the bill that purports to do just that, which they described as a "final offer" to Democrats.
But Mark Hays, the associate director of crypto and fintech policy at Americans for Financial Reform, said these changes were mostly "window dressing."
Under the new version, he wrote on Monday, crypto would still have fewer guardrails than other investments, much of its activity would still escape oversight, regulators would still have too few tools to crack down on abuse, and crypto would still become much more intertwined with national banks, meaning that a crypto crash could wreak havoc across the economy.
Hays said the bill's new ethics language also "still fails to address President Trump’s unprecedented profiteering from corrupt and conflicted crypto ventures while in office," a predictable outcome since his own White House approved the language.
The bill prohibits state attorneys general from bringing ethics enforcement against public officials unless Trump administration officials approve. It also leaves the US attorney general, Todd Blanche—who has portrayed himself as Trump's personal lawyer—and an in-house ethics council as the sole arbiters of whether the president violated new rules.
And while the Clarity Act could eventually require Trump to put some of his assets in a blind trust, Hays noted that the provisions "exclude the lion’s share of the Trump family’s existing crypto enterprises, exclude his sons who operate these firms, and allow carve-outs that enable Trump’s branded crypto ventures to continue to generate profits."
Hays called the bill an attempt to “trick senators into voting for a giveaway to the crypto industry and crypto billionaires,” adding that “no one should be fooled” by the last-minute changes.
"It still fails to stop Trump’s crypto corruption; it still allows traffickers, rogue actors, and sanctions evaders to launder money with crypto; it still allows crypto platforms to unfairly gouge customers; and it still allows platforms to pay interest on stablecoins that will drain deposits from community banks," he said.
Sen. Mark Warner (D-Va.), who also sits on the Senate Banking Committee, has participated heavily in negotiations around the Clarity Act and has said he's not ruled out allowing it to advance. But on Monday, he told Semafor's Burgess Everett that while "there has been some movement," he didn't "think the ethics provision is near enough."
Warren made the case on the Senate floor Monday for her colleagues to vote against the bill, describing the new provisions as a "weak fig leaf that will do nothing to stop him from making his next $1.4 billion in crypto profits" and that would enable his effort to create a bank.
She called on Congress to instead pass her Ending Presidential Corruption in Banking Act, which would bar senior government officials from owning and controlling a bank while in office.
Trump's personal meme coin alone has left its investors $3.2 billion underwater, Public Citizen found.
A report released Thursday by government watchdog Public Citizen estimates that President Donald Trump's assorted cryptocurrency products have left investors on the hook for billions of dollars in losses.
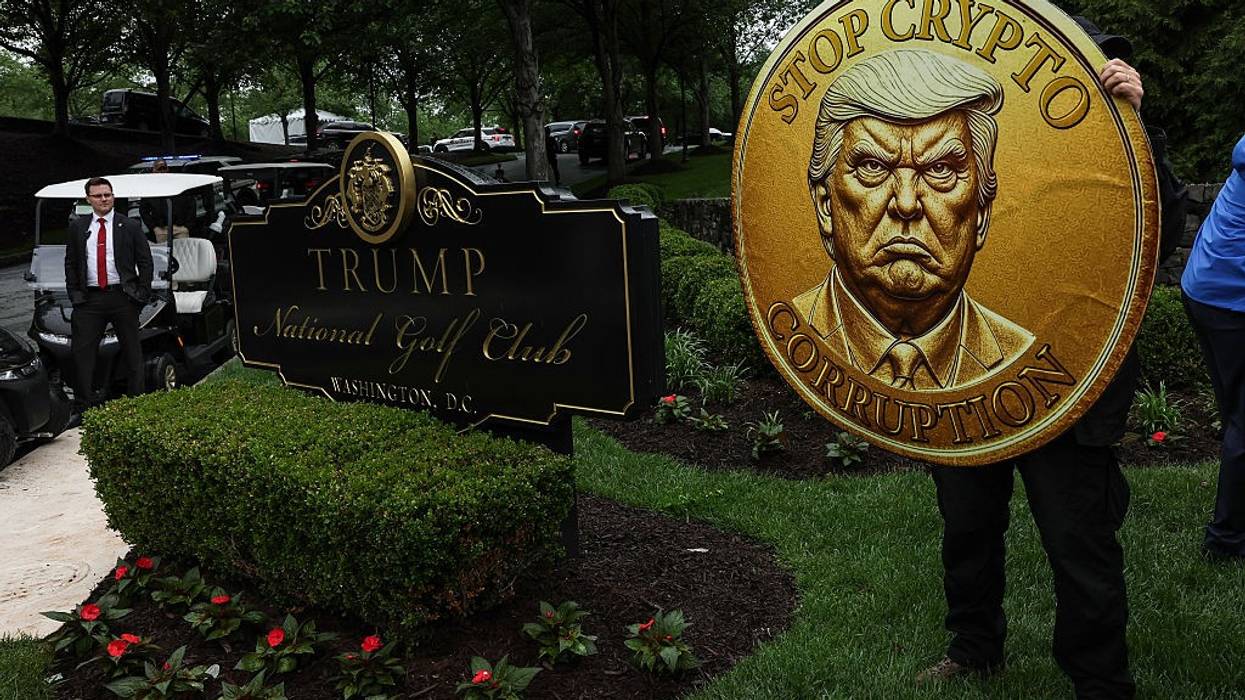
In total, Public Citizen found that Trump's crypto schemes have left investors at least $4.7 billion in the hole, with the majority of those losses coming from investments into the president's personal meme coin, which he launched just three days before the start of his second term.
The value of Trump's meme coin peaked at over $73 per token two days after its launch. Since then, its value has completely cratered and it is currently trading in the $2 range.
Early investors in the coin scooped up tokens that they quickly unloaded to other buyers, who were left holding the bag after the value of the digital assets collapsed.
In all, Public Citizen explained, 1% of wallets that invested in the coin reaped 80% of all gains, while 65% of wallets that put money into it are underwater to the tune of $3.2 billion.
Even as many investors in the Trump coin saw the value of their investments deteriorate, the president profited handsomely, hauling in $635 million in licensing fees from the coin last year alone.
Trump was also not personally hurt by the coin's drop in value given that he invested no money to acquire his own share of the digital tokens, which Public Citizen estimated is worth $271 million.
While the Trump meme coin accounted for the lion's share of losses suffered by investors, Public Citizen also highlighted the damage done by governance tokens issued by World Liberty Financial, the cryptocurrency venture co-founded by Donald Trump Jr. and Eric Trump in 2024.
As explained by Public Citizen, a governance token is "a digital commodity that conveys to holders certain 'rights with respect to the associated functional crypto system,' according to the SEC and Commodity Futures Trading Commission (CFTC)."
In practice, however, Public Citizen said that owning such tokens is akin to having "membership in a condo board—but without actually getting to vote on many issues or even own the condo."
The price of the tokens reached a peak of $0.33 per unit in September 2025, but they're now trading at under $0.06 per unit.
And much like the Trump meme coin, a small group of early investors made a killing on the tokens while most others racked up losses totaling at least $1 billion.
"The accredited and foreign investors who got in on the private sale paid $0.015 or $0.05, meaning they’re up anywhere from 15% to 283%," wrote Public Citizen. "Almost everyone who bought the tokens on the public market, though, is down—possibly as much as 83%, if they bought at the peak."
Public Citizen also highlighted the money lost by people who bought nonfungible tokens (NFTs) that Trump marketed as digital trading cards and that sold for $99 a piece.
While the cards were initially worth $12.3 million at the time of their release, their aggregate value has since fallen to $3 million, leaving investors $9.3 million underwater. But regardless of how well investors in the cards fared, Trump still made $7.2 million in licensing fees and royalties on secondary market sales, Public Citizen found.
Zach Everson, research director for Public Citizen's Trump Accountability Project and author of the report, cautioned Trump critics against ridiculing people who invested in the president's crypto products in a Thursday social media post.
"Trust me, I get the desire to sneer," wrote Everson. "People decided to put their money into virtual currencies backed by the word of a man who: admitted to misusing charitable funds; took six companies into bankruptcy; was convicted of 34 felony counts of falsifying business records. But these people got screwed over nevertheless."
"We have never seen financial conflicts or corruption of this magnitude."
The Office of the Comptroller of the Currency, a regulatory agency whose leader was chosen by President Donald Trump, granted preliminary approval on Friday to World Liberty Financial's application for a federal bank charter.
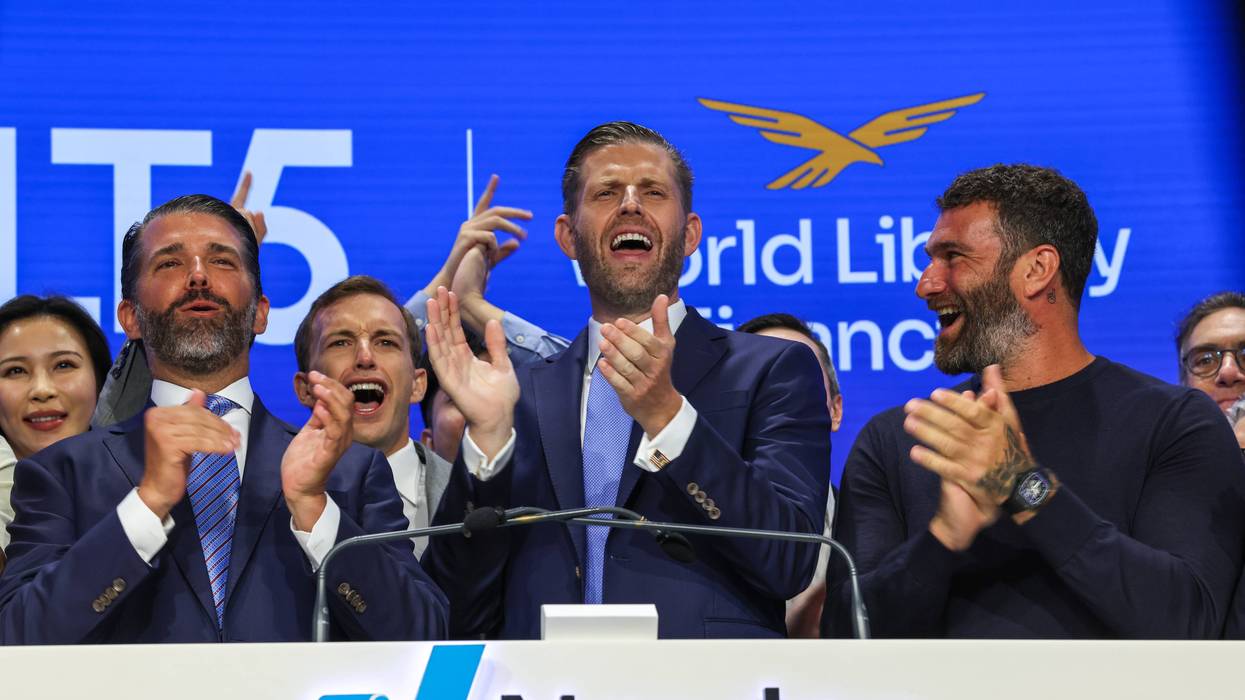
World Liberty Financial is a crypto venture launched in 2024 by the president's two eldest sons, Donald Trump Jr. and Eric Trump, and several partners. The firm's website states that WLF is 38% owned by "an entity affiliated with Donald J. Trump and certain of his family members."
WLF applied for a US bank charter in January, drawing alarm from lawmakers and watchdogs who said the review process would be rife with conflicts of interest. "We have never seen financial conflicts or corruption of this magnitude," Sen. Elizabeth Warren (D-Mass.), the top Democrat on the Senate Banking Committee, said at the time.
The OCC, headed by Jonathan Gould, announced the approval decision in a letter published Friday. WLF's application was assessed by career OCC staff, the agency said.
"The Office of the Comptroller of the Currency (OCC) has reviewed your application to establish a new national trust bank, which will engage in operations of a trust company and activities related thereto, including fiduciary activities, with the title of World Liberty Trust Company, National Association," the letter states. "The OCC hereby grants preliminary conditional approval of your charter application upon determining that your proposal meets certain regulatory and policy requirements."
In response to the news, Warren wrote on social media that "this is the most brazen act of self-dealing our financial system has ever seen."
Reuters reported that the charter, if finalized, would allow World Liberty's "to directly issue its USD1 stablecoin, as well as custody the US dollar assets backing it, both of which are now handled by a business partner, BitGo."
"Hoping to capitalize on the Trump administration’s crypto-friendly stance, the industry has been knocking on the OCC’s door for such charters," Reuters noted. "They allow crypto companies to hold assets on behalf of clients nationwide under a single federal charter, as well as to provide other settlement and asset servicing functions—making it easier to court major institutional clients. Other crypto firms, including Ripple and Circle, have received preliminary approval for such charters under Comptroller Jonathan Gould."
World Liberty Financial welcomed the OCC's preliminary approval as "a milestone in a multi-step chartering process." The firm said in a press release that the newly formed bank's board would be chaired by Zach Witkoff, the son of Trump's special envoy to the Middle East.
Last year, Trump reaped around $527 million in proceeds from token sales by WLF, according to financial disclosures released in late June.
"They are making sure they are rich beyond their wildest dreams long after Trump departs the White House (if he departs the White House)," journalist Mehdi Hasan wrote in response to the OCC decision. "It's so openly and nakedly and obviously corrupt, I'm not sure it can be overstated."
From filling the Reflecting Pool with algae to creating a mess of the global economy by invading Iran, some of President Trump's choices have been questionable to say the least.
The first thing I swear I won’t do, if the American people were to elect me (at 82 years of age) president of these (dis)United States of ours is to put any more algae in the Lincoln Memorial Reflecting Pool in Washington, DC, or, for that matter, any more millions of (our tax) dollars into making it ever greener (as Donald Trump has already done with $16.4 million of them).
Oh, and talking about that presidential algae, there may be a second thing (not) to do if Donald Trump manages to take away birthright citizenship from Washington’s algae, or for that matter if he manages somehow to get congressional Republicans to do the same for children born of immigrants to this country (despite the Supreme Court and our Constitution). Of course, that document couldn’t be clearer on the subject, though obviously not clear enough for “our” president. (”All persons born or naturalized in the United States, and subject to the jurisdiction thereof, are citizens of the United States and of the State wherein they reside. No State shall make or enforce any law which shall abridge the privileges or immunities of citizens of the United States; nor shall any State deprive any person of life, liberty, or property, without due process of law; nor deny to any person within its jurisdiction the equal protection of the laws.”)
As Trump put it recently, “Congress should start TODAY to work on ending expensive and unfair to our Country, Birthright Citizenship.” And it’s a good point, right? Who wants the kids of immigrants born here to become citizens? In fact, inspired by Trump, I should email my long dead immigrant grandfather, who came from what’s today Ukraine, in heaven (or, for all I know, hell) and tell him not to have my dad because Donald Trump would never have considered him a citizen of the United States and would have expelled him—and, had that happened, who knows where I might have been born (if I were born at all). Of course, the same could be said for Donald J. Trump, since his mother was indeed an immigrant and, had he had the chance, he might well have chucked her out of the country, too (though, since she was a white Scottish immigrant, given how he feels about white South African immigrants, maybe he would have welcomed her instead).
Oh, and sorry, but here’s a third thing that came to mind not to do (if I were president): It’s not just a matter of being born here, according to the United States Constitution. Plenty of American citizens of every imaginable sort are going to suffer miserably from the fact that “our” president and congressional Republicans have managed to cut an estimated $536 billion (or is it a full trillion dollars?) from Medicare over the next decade. Of course, what could possibly go wrong with that, since it’s estimated that less than 12 million Americans, a mere drop in the bucket, will lose their Medicaid coverage and a mere 5 million more their health insurance in the years to come?
And on that he’s been proven right, I guess. It’s not an endless war (not yet anyway), just an endless mess, imperiling the global economy, and what in the world could be the harm in that?
And let me add something else as the fourth thing I wouldn’t do (or in this case, wouldn’t have done): I wouldn’t have attacked Iran out of the blue and for no imaginable reason, ensuring that the Strait of Hormuz would be closed and the global economy sent into a fossil-fuelized free fall (even if that free fall has, at least, lent a hand to a future green economy). I mean, honestly, how dumb was that for the man who once swore that “under Trump, we will have no more wars, no more disruptions, and we will have prosperity and peace for all”? I’m talking about the fellow who not so long ago walked out of an interview with NBC’s Kristen Welker, when faced with such statements of his own, saying, “First of all, I didn’t guarantee no war.” (Yes, he did!) And then, when it came to his war on Iran, he added, “So when you say I promised—I didn’t promise anything. I don’t like these endless wars. This is not an endless war.”
And on that he’s been proven right, I guess. It’s not an endless war (not yet anyway), just an endless mess, imperiling the global economy, and what in the world could be the harm in that?
As for the fifth thing I wouldn’t do—that I wouldn’t, in fact, have been faintly capable of doing—as The New York Times recently reported, Donald J. Trump pulled in approximately $2.2 billion as president in 2025 from the Trump family’s cryptocurrency businesses, his real estate holdings, and who knows what else (more money, in short, than he had been making as a private citizen). As the Times noted, “One of his biggest hauls in 2025 came when an investment firm tied to the United Arab Emirates bought nearly half of the Trump family’s main crypto company, World Liberty Financial, a transaction that blurred the line between foreign policy and private enterprise.” Oh, and don’t forget those “hundreds of millions of dollars from sales of his $TRUMP memecoin and World Liberty’s sale of its own digital tokens.” Clearly, my problem is that I don’t own any cryptocurrency. In fact, I’m so old that, unlike Donald Trump, who just turned a youthful 80, I’m at a total disadvantage, since—and I just checked my pockets—I don’t seem to have a single bit of cryptocurrency around. Of course, since I basically don’t know what cryptocurrency is, I have no idea whether it could even be in my pocket. (Sigh.)
Oh, yes, and here’s one more thing, a final sixth thing I wouldn’t do as president: On a planet where Europe has been sweltering; the world’s ocean surface temperatures have hit record highs (and last year, as The Guardian reported, “the amount of heat being added to the oceans was equivalent to about... 11 Hiroshima explosions a second”); and Central Park in my own city of New York just officially hit 100°F as July began, I wouldn’t go out of my way to up the level of fossil-fuel use and take out after every windmill in sight.
But of course, that’s me and it’s true that I didn’t win the election of 2024 and become this country’s president a second time around. No such luck. So, of course, it matters not at all what I wouldn’t do on this distinctly imperiled planet of ours. Sigh...
"The Trump family has made over $5 BILLION in corrupt crypto deals," said Rep. Greg Casar. "Now Trump is openly bragging that his government won’t investigate cryptocurrency-related crimes."
President Donald Trump on Monday boasted about how lax his administration has been in pursuing investigations into the cryptocurrency industry.
Speaking at the White House, Trump attacked former President Joe Biden's administration for prosecuting cryptocurrency industry figures for a wide variety of crimes related to money laundering and fraud.
"They were very violently against [the crypto industry]," Trump said. "They were putting people in jail. What they were doing to the crypto world, it was horrible. It's amazing that it survived that onslaught, it was a weaponization of government."
Trump then explained how he drew support from the industry by coming out in favor of it during the 2024 presidential campaign, adding that "every time I see a crypto guy where they dropped an investigation, I said, 'You're lucky I'm president.'"
Trump: "Every time I see a crypto guy where they dropped an investigation, I said, 'You're lucky I'm president.'" pic.twitter.com/7Jgg0ffgq7
— Aaron Rupar (@atrupar) July 6, 2026
During his second term, Trump has not only taken a hands-off approach to the crypto industry, but also pardoned Changpeng Zhao, the founder of cryptocurrency exchange Binance, who pleaded guilty to money-laundering charges in 2023.
This pardon drew allegations of corruption given that Binance has been a major financial booster of World Liberty Financial, the crypto venture backed by the Trump family that has added billions of dollars to their total wealth.
Even as Trump has personally raked in money from selling his own memecoin, many of his supporters who invested in it have lost significant sums of money.
A Sunday report in The New York Times revealed that nearly 1 million people who invested in the Trump memecoin have recorded losses totaling $3.8 billion since its launch in 2025.
As the Times noted, "Trump profited whether the price of his memecoin went up or down" because he "collected returns whenever anyone traded the tokens, as he repeatedly pushed his followers to do, using his Truth Social account to promote the coin."
Rep. Greg Casar (D-Texas), chair of the Congressional Progressive Caucus, ripped the president for openly boasting about going easy on the industry that he's personally profiting from.
"The Trump family has made over $5 BILLION in corrupt crypto deals," Casar wrote in a social media post. "Now Trump is openly bragging that his government won’t investigate cryptocurrency-related crimes. Corruption, plain and simple."
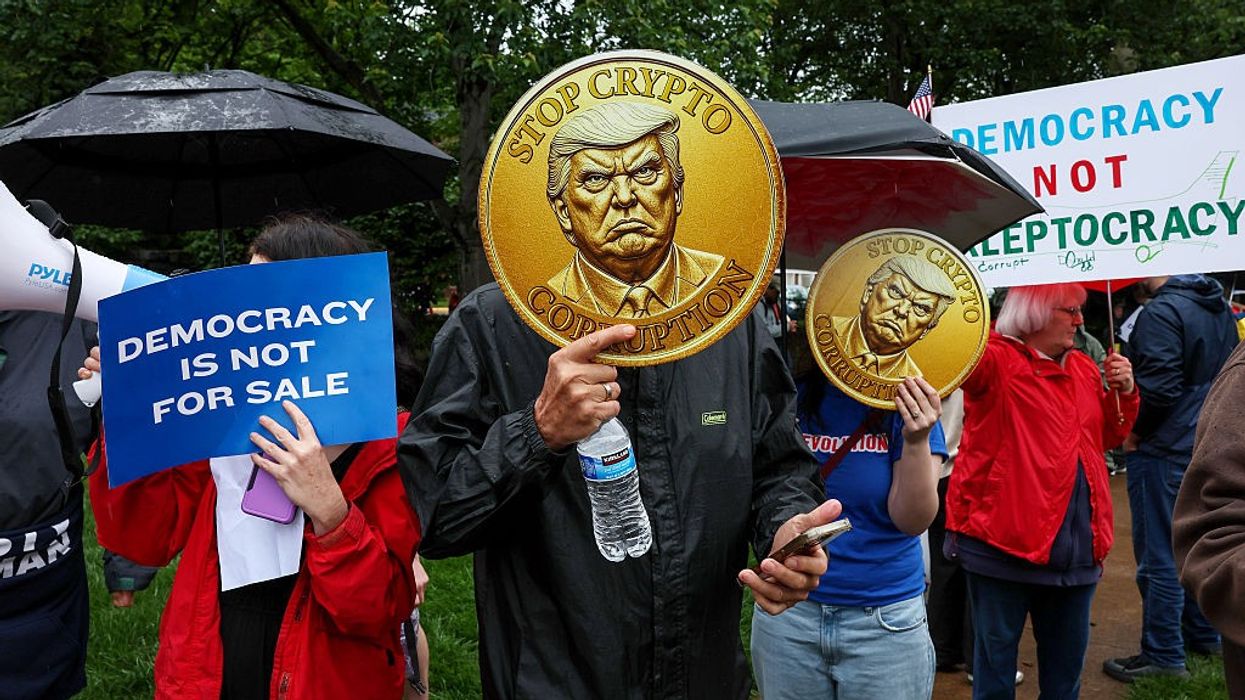
The administration has endeavored to negotiate every peace deal, trade agreement, investment arrangement, and mineral pact in such a way as to deliver Trump, his family, and their circle of close supporters a good chunk of change.
The Trump administration concluded a recent mineral deal with Kazakhstan that, not surprisingly, enriches not only President Donald Trump’s own family but that of his secretary of commerce, Howard Lutnick. Trump’s two eldest sons, part owners of Dominari Securities, are set to profit from the Kazakh tungsten deal. So is Cantor Fitzgerald, the investment firm run by Lutnick’s two sons.
As The New York Times pointed out in its investigation of the scheme, “Their sons were soon doing business with partners in a deal that their fathers were negotiating, continuing a pattern of self-enrichment in the second Trump administration that has few precedents in American history.”
The phrases “self-enrichment” and “few precedents” are interesting ways of characterizing this latest instance of the administration’s corruption. Isn’t self-enrichment a good thing, in the sense of profiting from your own hard work? By contrast, the article doesn’t mention the word “corruption” at all. Perhaps the Times is worried about getting hit by yet another Trump legal challenge (in October last year, Trump refiled a $15 billion defamation suit against the paper for its coverage of his 2024 presidential campaign).
There are indeed several precedents in American history for what Trump is doing. These previous corruption scandals—Credit Mobilier, Whiskey Ring, Teapot Dome—wrecked the reputations of presidents and cast long shadows over American politics. They also helped to produce the kind of safeguards that Trump is now destroying.
Foreign policy is a tool by which the administration levies a toll on any entity that has the temerity to be a country other than the United States.
As with much of Trump’s disrespect for norms, his corruption has been massive and largely in full view. The two outstanding questions are: Will Trump and company ever be held accountable for their graft and will this corruption have an enduring impact on political institutions in the United States?
If scandalous behavior unfolds in full view of everyone, is it still a scandal? “Scandal” suggests something hidden, something whispered about, something revealed. Trump’s actions are full frontal. They are both brazen and matter-of-fact.
According to the Trump administration and its extended family, the money skimmed off the top of economic transactions is just smart politics. The administration has endeavored to negotiate every peace deal, trade agreement, investment arrangement, and mineral pact in such a way as to deliver Trump, his family, and their circle of close supporters a good chunk of change.
This is Trump’s interpretation of the American dream: Folks would be downright foolish not to profit from their position. All the great tycoons made their money, from railroads to AI, by being in the right place at the right time with the right amount of ruthlessness. In Trump’s case, however, he is using taxpayer money to cover the risk. And most the time, given the terms of the arrangement, there is hardly any risk because Trump is using his presidential power to game the system. That’s what he really means by the “art of the deal.” Trump only deals from a marked deck of cards.
The Center for American Progress runs Trump’s Take, which estimates that the president has received a little over $2.6 billion in cash and gifts since he took office in January 2025.
The graft is not secret, though sometimes the actual amounts involved are obscured by layers of complex finance. Trump’s recent mandatory financial disclosure offers some details. But thanks to a number of websites, it’s become quite easy to track in real time the growing amount of Trump’s slice of the pie.
The Center for American Progress runs Trump’s Take, which estimates that the president has received a little over $2.6 billion in cash and gifts since he took office in January 2025. Much of this money has come from various crypto schemes, including the Trump meme coin, but also such dubious ventures as the documentary about Melania Trump and a number of legal settlements (more colloquially known as shakedowns). Corruption Counter puts the value at $2.2 billion and includes such recent items as the $100 million savings for Trump from the recent effort to bar the Internal Revenue Service from auditing the president. (Courts blocked the overall $1.8 billion “settlement fund,” but the Justice Department is upholding the IRS amnesty.)
If you want to keep track just of the crypto deals, the Democrats on the House Oversight Committee maintain the Trump Family Digital Grift Wealth Tracker. Senator Chris Murphy (D-Conn.) keeps his own list, which highlights the insider trading around the Iran War and a defense contract with Dell after the president invested in the company. David Kirkpatrick, at The New Yorker, has been keeping a running total of Trump’s ballooning assets. In January, he updated his total to $4 billion, which details, among other things, the Gulf money flowing into Trump pockets. Meanwhile, at RepresentUS, you can find a timeline of shady deals, from the no-bid contract to a presidential supporter for the Reflecting Pool “upgrade” to an Air Force contract for drones awarded to a company backed by Trump’s eldest sons.
In May, Campaign Legal Center published a rundown of influence peddling—what Trump supporters get in return for their contributions—that includes Elon Musk’s DOGE appointment, Immigration and Customs Enforcement contracts for the Trump-supporting GEO Group, and the cessation of various lawsuits for Trump-friendly entities (Gemini, Robinhood, Coinbase). Citizens for Responsibility and Ethics in Washington has its own tracker that keeps up with the number of major events held at Trump’s properties and the number of Trump-branded foreign projects developed during his second term (with a new Trump Tower planned for Tbilisi, Georgia, it’s now up to 25).
Sometimes it seems as though Trump administration policy is just a front for making money, much as a shell company provides a legitimate façade for organized crime.
One of the sticking points in the current war with Iran is the latter’s attempt to control shipping in and out of the Strait of Hormuz. Tehran wants to charge a toll on ships passing through the Strait. Given that the strait is an international waterway—and not a canal—Iran’s bid violates international law.
Trump has opposed Iran’s gambit not so much because it violates the Law of the Seas but because Iran has borrowed a page from the Trump playbook. How dare they try to trump Trump! Indeed, the president has threatened a toll of his own if the ceasefire doesn’t hold: a take of 20% of regional revenues if the United States becomes “the guardian of the Middle East” by using military force to protect shipping in the region.
Foreign policy is a tool by which the administration levies a toll on any entity that has the temerity to be a country other than the United States. The Kazakh deal on tungsten is but one of several ways that the administration has cashed in on critical minerals. The Trump sons have a financial interest in 14 companies working with the US government on mineral deals that involve nearly $9 billion in federal funding. This includes $620 million Pentagon loan, fast-tracked by the White House, to a North Carolina rare-earth magnet company in which Donald Trump Jr.’s venture capital firm has invested. Several Trump associates stand to gain from any future deal involving Greenland minerals.
Trump has used tariffs to extract various concessions. In some cases, countries have responded by appealing to Trump’s self-interest. Vietnam, for instance, approved a Trump golf course and received a tariff reduction. Switzerland also enjoyed such treatment when it gifted Trump “a special Rolex desktop clock, a 1-kilogram personalized gold bar, and loads of flattery.” The message is clear: US trade policy is for sale.
Even peace agreements are not immune from the Trump treatment. The Gaza peace deal offers potentially lucrative opportunities for outside businesses to profit from the reconstruction of the rubble-strewn area. “Everybody and their brother is trying to get a piece of this,” one long-time contractor told The Guardian. “People are treating this like another Iraq or Afghanistan. And they’re trying to get, you know, rich off of it.” The executive board of Trump’s Board of Peace is dominated by titans of industry—Marc Rowan, Steve Witkoff, Jared Kushner—all salivating at the prospect of using their insider position to profit (though, with progress stalled on the ground, the Board of Peace may end up doing corruption the old-fashioned way by just siphoning off the money up front and granting itself legal immunity to escape the consequences).
The deal that created a “Trump corridor” between Armenia and Azerbaijan was similarly projected to provide commercial opportunities to Trump cronies. But it has yet to get off the ground, another victim of Trump’s propensity to make a big splash with his agreements and neglect to secure the follow-through. Trump’s peace deal with Russia, negotiated on the backs of the Ukrainians, would have also meant a huge windfall for Trump cronies—in opportunities for reconstruction contracts in Ukraine and even larger profits for the commercial reengagement with Russia.
In The Atlantic, several months after Trump took office, David Frum summed up the corrupt activities of the administration this way:
Nothing like this has been attempted or even imagined in the history of the American presidency. Throw away the history books; discard feeble comparisons to scandals of the past. There is no analogy with any previous action by any past president. The brazenness of the self-enrichment resembles nothing seen in any earlier White House. This is American corruption on the scale of a post-Soviet republic or a postcolonial African dictatorship.
Frum served in the George W. Bush White House. A NeverTrumper, he nevertheless knows a little something about corrupt conservatives. Upwards of $20 billion of post-war reconstruction aid for Iraq disappeared into the ether of corruption (and the pockets of US firms, including Halliburton). Trump stands on the shoulders of giants.
Donald Trump knows that he is a living, breathing violation of the law. That’s why he has gone to such lengths to ensure immunity—the Supreme Court decision providing presidents with immunity from criminal prosecution for their official acts, the attempt to secure exemption from IRS audits. Trump has also promised to pardon preemptively “everyone who has come within 200 feet of the Oval Office.”
Let’s tackle Trump first. His immunity is not absolute. First, it does not cover “unofficial acts.” Depending on how courts define this category, Trump (and certainly his family) could be prosecuted for corrupt business dealings that are deemed “private.” Second, immunity doesn’t apply if it can be demonstrated that criminal prosecution poses no “dangers of intrusion on the authority and functions of the Executive Branch.” That’s another tough one to parse, and it will probably fall to future courts to define. But if something is demonstrably corrupt, then it should by definition fall outside the legitimate authority and functions of the Executive Branch.
Trump has already used his broad powers to pardon the January 6 rioters and other malefactors, including 22 corrupt politicians. Trump cronies must look at this record and feel pretty safe from future prosecution.
Donald Trump knows that he is a living, breathing violation of the law.
But presidential pardons also have their limits. Such pardons can’t violate the Constitution or criminal law—though Trump has challenged these strictures—and they don’t cover future crimes. More to the point, Trump’s pardons only apply to federal prosecution. Individuals can still be tried in various states (and overseas if their misconduct took place in other countries).
The impact of Trump’s misconduct is directly related to this question of immunity. If the president and his coterie “get away with it,” then the corruption they initiated will be much harder to root out of political institutions. Unprosecuted acts can harden into precedents. Throwing Trump and company into prison would be satisfying. Ditto clawing back their ill-gotten gains. From the point of view of democracy, however, even a plea bargain in which the malefactors stay out of jail and pay a nominal penalty in exchange for pleading guilty would be a victory.
It’s best to think of Trump as an aberration, however much his behavior can be traced to past scandals, the authoritarian tendencies of previous presidents, and the oft-corrupt workings of American capitalism. Democracy, like any fiction, requires the willing suspension of disbelief. Trump’s truly an unbelievable character. Once he’s gone, it will be time to pretend that the monster has been vanquished and the rule of law restored. Only in this way will America escape its semiquincentennial with its clothing muddied but its presumably good intentions intact.
One expert who has studied presidential wealth called Trump's windfall "completely unprecedented" in American history.
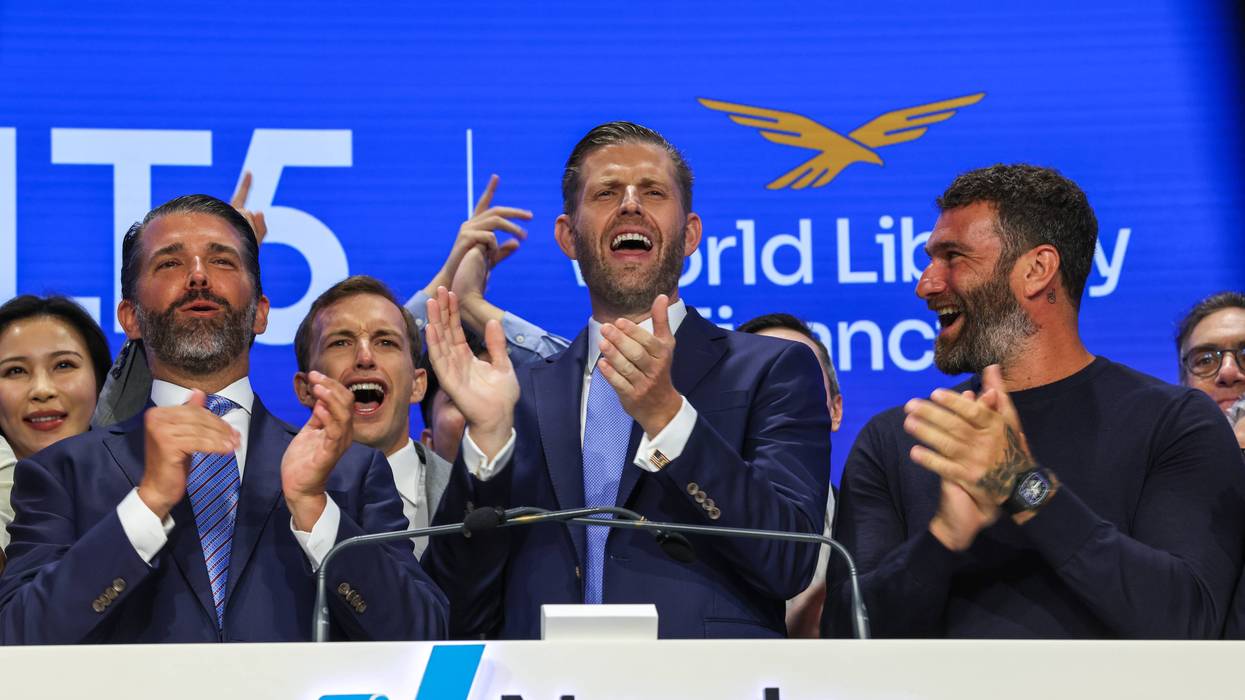
Annual financial disclosures released Tuesday reveal that US President Donald Trump pocketed at least $2.2 billion—more than half of it from his family's crypto grift—during his first year back in the White House, a windfall that experts say is without precedent in American history.
The disclosure report shows that Trump pulled in $635 million in royalties from Celebration Coins, an entity linked to the president's meme coin. The president also disclosed around $527 million in proceeds from token sales by World Liberty Financial, the Trump family crypto venture spearheaded by Eric Trump and Donald Trump Jr.
“It is completely unprecedented,” Megan Gorman, a tax attorney who has studied the history of presidential wealth, told The New York Times of the president's windfall.
Robert Weissman, co-president of the consumer advocacy group Public Citizen, said in a statement that "Trump’s obscene income is driven by various cryptocurrency schemes, leveraging his political position to exploit a scam-driven industry that he once said was nothing more than a racket."
"In doing so, he’s ripping off investors—to the tune of billions—who want to get in on the game with him, or think that buying his crypto products is an innocent means to show their support," said Weissman. "Most troubling, Trump’s personal profit interest has now aligned him with the crypto industry, paving the way for dangerous legislation that will facilitate mass rip-offs and even threaten financial system stability."
Trump's massive profits from an industry he's tasked with regulating represent what the watchdog group Campaign Legal Center (CLC) described as an "unprecedented" conflict of interest, notwithstanding the White House's laughable claim that "neither the president nor his family has ever engaged—or will ever engage—in conflicts of interest."
"We have never seen a president have direct conflicts of interest with his financial holdings and the policies he supports, and it’s another example why we need widespread ethics reform now," Kedric Payne, CLC's senior director of ethics, told The Wall Street Journal.
The Journal noted that, in addition to crypto profits, "Trump reported $4.7 million in income last year from Trump-branded watches, as well as $1.9 million in royalties from his 'Save America' book."
"Multimillion-dollar licensing deals linked to real-estate developers stretched from Romania to India to across the Middle East. A $6,484-a-month pension from the Screen Actors Guild continued paying out," the newspaper observed.
The disclosures also include tens of million dollars in legal settlements stemming from Trump's lawsuits against major companies, including ABC, CBS, and Meta.
Sen. Elizabeth Warren (D-Mass.), the top Democrat on the Senate Banking Committee, said Tuesday that lawmakers must add language to the upper chamber's crypto legislation that prevents "the president, vice president, senior administration officials, members of Congress, and their families from profiting off the crypto industry."
"If it does not," the senator warned, "it will only turbocharge Donald Trump’s brazen crypto corruption."
"The intense escalation of corporate spending we are now seeing shows that it is well past time for salvaging American democracy to be treated with the urgency that it deserves."
As the right-wing majority on the US Supreme Court on Tuesday handed down a 6-3 ruling that campaign finance reform advocates warned would give special interest groups and rich donors yet another way to curry favor with politicians, a new report from government watchdog Public Citizen revealed how "corporate supremacist" groups have already set records for spending in this year's midterm elections.
There are still more than four months to go until the general election, but according to "The Rise of Corporate Supremacist Super PACs,” by research director Rick Claypool, this campaign cycle accounts for nearly one-third of all corporate political spending since the 2010 Citizens United v. Federal Election Commission (FEC) ruling.
That decision has enabled corporations and groups including super political action committees (PACs) to spend unlimited money on elections, and in the 2026 cycle alone, they have already spent $517 million—"a figure sure to soar as the November general election approaches," said Public Citizen.
"These totals reference disclosed political spending, not any contributions from dark money organizations that keep donors secret," the group emphasized.
The amount spent this year by Big Tech, fossil fuel companies, the cryptocurrency industry, and other sectors whose bottom lines could benefit from lax government regulations represents a sizable chunk of the $1.58 billion that corporations have spent on federal elections since 2010.
The 2024 election cycle saw $461 million poured into campaigns by corporations, a sum that dwarfed previous corporate political spending.
Public Citizen released its report as the Supreme Court ruled in National Republican Senatorial Committee v. FEC, striking down regulations that for decades have restricted political parties from coordinating campaign spending with candidates.
The report offered more evidence that the high court "has reorganized America for the worse," said law professor Zephyr Teachout.
Four industries—crypto, artificial intelligence, Big Tech, and online betting companies—have spent $294 million collectively to influence the elections, said Public Citizen, accounting for 57% of the corporate spending.
In 2024, the crypto sector pioneered the playbook corporations are using this year—"prioritizing corporate priorities over parties or candidates and using their financial power to discipline sitting lawmakers and candidates."
PACs including the pro-AI Leading the Future and the sports betting industry-backed Win for America PAC are some of the top recipients of the corporate case, taking $50.1 million and $43 million, respectively.
A Win for America spokesperson told Axios in April that the super PAC's backers "seek candidates who will thoughtfully approach regulation and ensure legal sports betting can continue to support communities through billions in tax revenue and jobs across America," while Josh Vlasto of the pro-crypto PAC Fairshake said in 2025 that the committee is "building an aggressive, targeted strategy for next year to ensure that pro-crypto voices are heard in key races across the country.”
Claypool said the report shows that "a decade and a half after Citizens United, corporations are starting to spend on politics like never before."
"This corporate spending is a disaster for democracy," he said. "If the current, broken campaign finance system remains unchallenged—and corporate spending is allowed to drown out the voices of real voters and real people—these corporate campaigns will keep multiplying, even as voting rights for individual Americans face escalating attacks.”
Behind the "corporate supremacist super PACs," reads the report, the biggest beneficiary of corporate spending is the President Donald Trump-supporting MAGA Inc., which has received $120.6 million in direct contributions from companies including Crypto.com, UnitedHealthcare, and Energy Transfer Partners.
The report comes two weeks after campaigners in Montana announced they had collected signatures that far exceeded the minimum requirement to force a statewide vote on a ballot measure that, if passed, would block corporations from pouring money into elections.
"Time and time again, Americans have demonstrated they want elected officials who are willing to stand up for them against the powerful and predatory corporations that attempt to dominate our daily lives," reads the Public Citizen report. "Lawmakers can demonstrate their fearlessness and independence from corporate influence by passing legislation that empowers the public while reducing the influence of Big Business demands to prioritize profit-maximization over Americans’ health, safety, and democracy."
The group called on Congress to pass the "Abolish Super PACs Act, the DISCLOSE Act, and, ultimately, a constitutional amendment to overturn Citizens United."
"The intense escalation of corporate spending we are now seeing," concludes the report, "shows that it is well past time for salvaging American democracy to be treated with the urgency that it deserves."