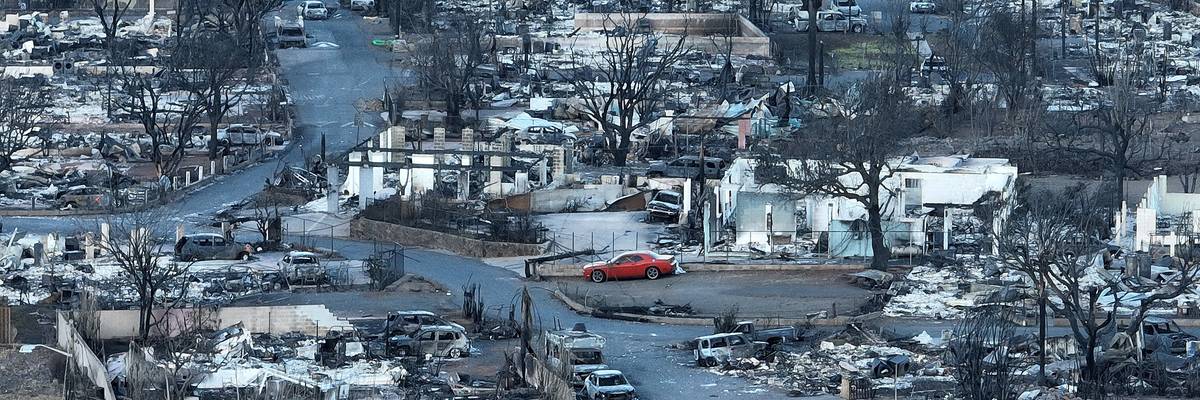
This August 18, 2023 aerial photo shows a neighborhood in Lahaina, Hawaii after deadly fires destroyed most of the historic Maui town.
Report Warns 'Today's Climate Crisis Is Tomorrow's Banking Crisis'
"This growing unseen and unacknowledged banking crisis is going to become visible soon as the climate-related disasters and losses pile up and insurance companies continue to go bankrupt."
Insurance companies bankrupted by climate disasters are the "canaries in the coal mine" portending "a much worse banking crisis," and regulators must act with urgency to avert financial crashes and costly bailouts, a report published Wednesday warned.
Amid increasingly frequent and severe fires, flooding, hurricanes, tornadoes, landslides, and hail storms across the U.S., "it's no surprise that there is a great deal of attention on the burgeoning crisis among insurance companies and their insured individuals and businesses," says the report, which was published by the financial reform advocacy group Better Markets.
"The U.S. property and casualty industry suffered losses of $5 billion in 2021, which ballooned to losses of $26.5 billion in 2022," Better Markets notes. "There have already been 15 confirmed weather/climate disaster events with losses exceeding $1 billion each in the U.S. as of August 8, 2023, with losses almost certain to exceed 2022."
That tally notably does not include the Hawaiian island of Maui, where a wildfire spread by hurricane-force winds leveled Lahaina, killing at least 115 people and causing an estimated $5.52 billion in damage.
"The number of insurance companies going bankrupt, withdrawing from states, limiting coverage, and significantly raising premiums is increasing by the day," the publication continues. "In addition, the reinsurance market, which is key for insuring major climate events, is facing a reduced investor demand, which is going to decrease coverage while increasing costs even more."
"However, this isn't just a crisis for insurance companies and their customers," Better Markets stresses. "The ongoing and worsening insurance crisis is the leading edge of a coming banking and financial crisis."
According to the report:
While climate risk is tragic for homeowners and problematic for insurance companies, it is exponentially worse for banks and the financial system. That's because insurance companies limiting their losses do not eliminate the losses entirely; they merely shift losses to other entities like banks which have large and increasingly concentrated portfolios of loans and other credit instruments to those now uninsured or underinsured real estate properties and businesses. When the inevitable climate disasters occur, those exposures will quickly become realized losses, potentially at levels that will cause banks to collapse, and possibly ignite a credit contraction, precipitate contagion, and result in a banking crisis if not a financial crash.
"There's a major untold story behind the unprecedented climate disasters pummeling the country and capturing the headlines: Today's climate crisis is tomorrow's banking crisis," said report author and Better Markets CEO Dennis Kelleher, who criticized federal regulators' lack of action.
"The Financial Stability Oversight Council (FSOC) and banking regulators' response thus far have been grossly inadequate and inconsistent with the material climate risks bearing down on banks and the financial system," he argued. "For example, the FSOC member agencies were called on just two years ago to bolster the financial system's resilience to climate-related financial risks. Yet, since then, the actions have been slow and half-hearted."
"This growing unseen and unacknowledged banking crisis is going to become visible soon as the climate-related disasters and losses pile up and insurance companies continue to go bankrupt and stop insuring homes, businesses, cars, and other bank assets in state after state," Kelleher warned.
"Just as insurance companies are acting to limit their losses, the FSOC and other banking and financial regulators must require banks and financial firms to assess their exposure to those losses and have an action plan to mitigate them before they materialize and cause banking crisis," he added. "Climate disasters are bad enough; a banking disaster on top of that will make everything much worse."
We are at a crossroads
This country and this world are at a monumental crossroads. In a few short weeks, US voters will have an opportunity to beat back the forces of fascism and confront the billionaires who are rigging the economy, our media system, and our democracy, making it increasingly impossible for ordinary people to get by. We’re not just talking about the election. We’re talking about what must be done once these fascist elements are vanquished from power. We need a bolder set of solutions than what either major party has so far been willing to offer and a working-class movement ready to fight like hell for it. Trump didn't emerge from nowhere. The conditions that fueled MAGA authoritarianism were created by decades of radical neoliberal economic policies and a corrupt political system dominated by corporate interests. They slashed taxes on the super-rich, promising that the benefits would trickle down. They said giveaways to the corporate titans would make life more affordable for the rest of us. It was all bullshit. And when a bitter, betrayed populace searches for someone to blame, right-wing demagogues have little trouble finding scapegoats. People know when they're being lied to, but you won't hear any of this from the corporate media. Only independent journalism—powered and funded by people who believe in building a better world—can deliver truly trustworthy daily news. Our Fall Campaign is underway, and we need your help. To power our newsroom through the rest of the year, we need to raise $125,000 by midnight on October 31. So if you share our vision, please contribute whatever you can to sustain our work. |
Insurance companies bankrupted by climate disasters are the "canaries in the coal mine" portending "a much worse banking crisis," and regulators must act with urgency to avert financial crashes and costly bailouts, a report published Wednesday warned.
Amid increasingly frequent and severe fires, flooding, hurricanes, tornadoes, landslides, and hail storms across the U.S., "it's no surprise that there is a great deal of attention on the burgeoning crisis among insurance companies and their insured individuals and businesses," says the report, which was published by the financial reform advocacy group Better Markets.
"The U.S. property and casualty industry suffered losses of $5 billion in 2021, which ballooned to losses of $26.5 billion in 2022," Better Markets notes. "There have already been 15 confirmed weather/climate disaster events with losses exceeding $1 billion each in the U.S. as of August 8, 2023, with losses almost certain to exceed 2022."
That tally notably does not include the Hawaiian island of Maui, where a wildfire spread by hurricane-force winds leveled Lahaina, killing at least 115 people and causing an estimated $5.52 billion in damage.
"The number of insurance companies going bankrupt, withdrawing from states, limiting coverage, and significantly raising premiums is increasing by the day," the publication continues. "In addition, the reinsurance market, which is key for insuring major climate events, is facing a reduced investor demand, which is going to decrease coverage while increasing costs even more."
"However, this isn't just a crisis for insurance companies and their customers," Better Markets stresses. "The ongoing and worsening insurance crisis is the leading edge of a coming banking and financial crisis."
According to the report:
While climate risk is tragic for homeowners and problematic for insurance companies, it is exponentially worse for banks and the financial system. That's because insurance companies limiting their losses do not eliminate the losses entirely; they merely shift losses to other entities like banks which have large and increasingly concentrated portfolios of loans and other credit instruments to those now uninsured or underinsured real estate properties and businesses. When the inevitable climate disasters occur, those exposures will quickly become realized losses, potentially at levels that will cause banks to collapse, and possibly ignite a credit contraction, precipitate contagion, and result in a banking crisis if not a financial crash.
"There's a major untold story behind the unprecedented climate disasters pummeling the country and capturing the headlines: Today's climate crisis is tomorrow's banking crisis," said report author and Better Markets CEO Dennis Kelleher, who criticized federal regulators' lack of action.
"The Financial Stability Oversight Council (FSOC) and banking regulators' response thus far have been grossly inadequate and inconsistent with the material climate risks bearing down on banks and the financial system," he argued. "For example, the FSOC member agencies were called on just two years ago to bolster the financial system's resilience to climate-related financial risks. Yet, since then, the actions have been slow and half-hearted."
"This growing unseen and unacknowledged banking crisis is going to become visible soon as the climate-related disasters and losses pile up and insurance companies continue to go bankrupt and stop insuring homes, businesses, cars, and other bank assets in state after state," Kelleher warned.
"Just as insurance companies are acting to limit their losses, the FSOC and other banking and financial regulators must require banks and financial firms to assess their exposure to those losses and have an action plan to mitigate them before they materialize and cause banking crisis," he added. "Climate disasters are bad enough; a banking disaster on top of that will make everything much worse."
- As Insurers Cut Coverage Due to Climate Disasters, Senators Probe Continued Backing of Fossil Fuels ›
- Opinion | How to Diffuse the Derivatives Time Bomb | Common Dreams ›