

SUBSCRIBE TO OUR FREE NEWSLETTER
Daily news & progressive opinion—funded by the people, not the corporations—delivered straight to your inbox.
5
#000000
#FFFFFF
To donate by check, phone, or other method, see our More Ways to Give page.
Daily news & progressive opinion—funded by the people, not the corporations—delivered straight to your inbox.
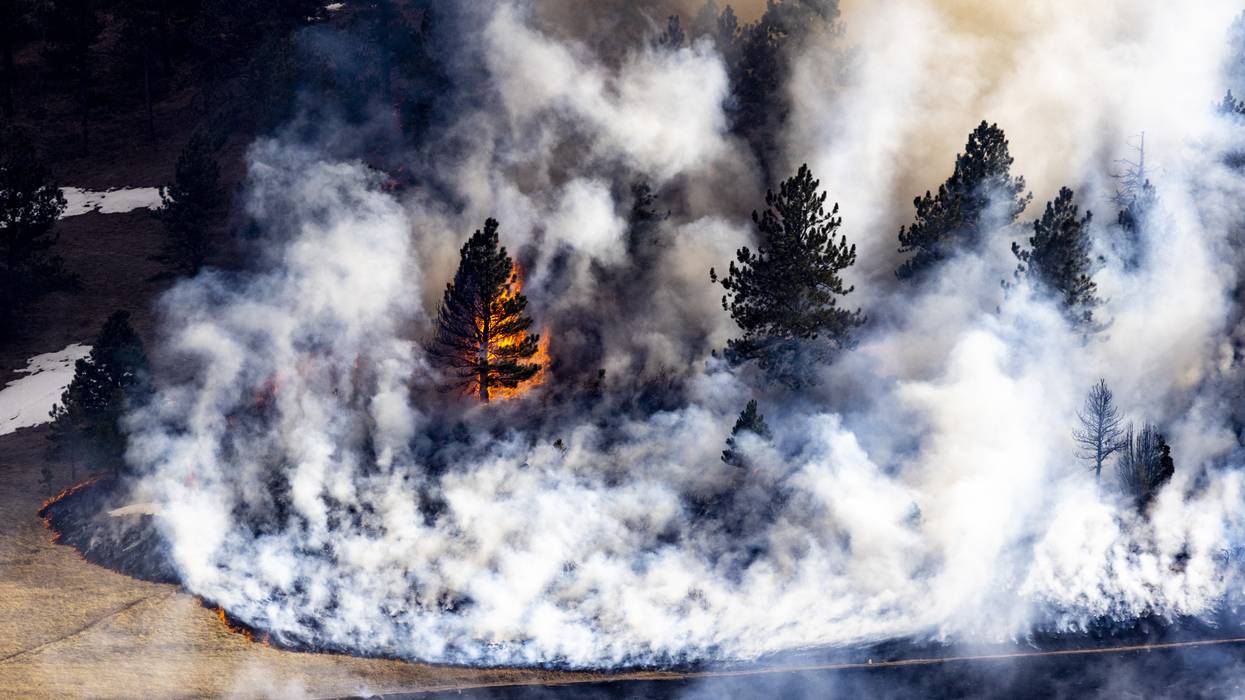
In recent years, insurers have pointed to growing climate risk as the reason for raising rates and dropping coverage. Now, they’re supporting the very industry driving that risk rather than the communities facing it. Why?
The US Supreme Court opens its new term on October 5 with oral arguments in Suncor v. Boulder—the most consequential climate case it has heard to date. The fossil fuel defendants are trying to block local governments from suing them for climate deception and harm. In an alarming display of corporate allegiance, the nation’s largest property insurance associations have sided with the oil companies seeking to avoid responsibility for climate losses, over the public entities and policyholders footing the growing bill.
In recent years, insurers have pointed to growing climate risk as the reason for raising rates and dropping coverage. Now, they’re supporting the very industry driving that risk rather than the communities facing it. Why?
From establishing cooling centers and flood protection plans to equipping firefighters and emergency responders, communities are shouldering the mounting costs of climate change. The burden is both untenable and unfair. That’s why a growing number of states and local governments have turned to courts to make fossil fuel companies pay their share for driving the climate crisis.
Fossil-fueled climate destruction threatens human life, health, the economy, and vital ecosystems on which all depend. That reality should incentivize insurers to break free from fossil fuels faster and protect the public from climate peril.
Of the nearly three dozen such suits pending across the US, Suncor v. Boulder is the first to reach the Supreme Court.
The case, brought by the city and county of Boulder, alleges Suncor and ExxonMobil knowingly contributed to climate change for decades by producing fossil fuels while deceiving the public about their dangers. Boulder argues the companies should be on the hook for the resulting climate harms and the rising costs of adapting to a warming world.
Rather than address the legal claims on their merits, the fossil fuel defendants have instead sought to get the case thrown out. They are urging the Supreme Court to bar Boulder’s suit on the grounds that it aims to regulate greenhouse gas emissions, something they claim only federal law can do. But as the plaintiffs and dozens of supporters explain, Boulder is seeking to recoup the costs of local harm and to hold the fossil fuel defendants accountable for misleading consumers, not pollution controls.
If the court rules for the defendants, it could close the door not just on this suit but others like it nationwide—leaving the public and local governments, rather than the companies that caused the harm, to keep covering the costs.
Nearly 70 friend-of-the-court briefs were filed in the case—many, like the Center for International Environmental Law’s, supporting the plaintiffs. Others, however, came in on the side of the fossil fuel industry. Among the 38 briefs backing Suncor and ExxonMobil, Consumer Watchdog found that 25 of them have documented financial ties to fossil fuel companies or the dark-money networks behind decades of climate denial.
Three major US insurance trade associations—the American Property Casualty Insurance Association (APCIA), the Complex Insurance Claims Litigation Association, and the Reinsurance Association of America—also submitted a brief in support of the defendants. These trade groups weren’t part of Consumer Watchdog’s analysis. But insurers, including members of these very associations, have their own story to tell of financial entanglement with the fossil fuel industry.
Like others helping the fossil fuel industry dodge accountability, the insurance sector has well-documented financial ties to oil and gas companies. Property and casualty insurers hold a growing financial stake in fossil fuels—the same products causing the climate losses that are driving insurers to hike premiums and withdraw coverage.
As of 2023, the US property and casualty insurance industry held $84.6 billion in fossil fuel investments. The share of insurers’ portfolios tied up in fossil fuels climbed from 3.8% in 2014 to 4.4% by 2023.
Every premium dollar that flows into those investments comes from policyholders, many of whom are already struggling to afford coverage in fire- and flood-prone areas. While warning it can no longer absorb climate risk, the insurance industry is betting on the very companies creating that risk.
In their published brief in support of the Suncor defendants, the insurance associations argue that allowing state tort claims like Boulder’s could make it harder for fossil fuel companies to get liability insurance—potentially creating uncertainty and instability in the insurance market.
But they ignore the actual uncertainty and instability facing tens of millions of homeowners and tenants in the US who are bearing the brunt of climate losses and a deepening insurance crisis. In 2025, the US saw more than 23 billion-dollar weather events. The country racked up the lion’s share of global insured losses last year from what the industry continues to call “natural catastrophes,” which include climate-intensified events.
Citing climate risk, insurers are raising rates, dropping policies, and widening the climate protection gap. Home insurance premiums in the US grew by almost 50% between 2020 and 2024—more than double the rate of inflation. And since 2018, insurers have dropped more than 1.9 million home insurance contracts nationwide, contributing to a rising number of uninsured homes.
Yet the insurance industry opposes efforts to make the fossil fuel companies responsible for rising climate risk pay their fair share for resulting climate harm. If insurers are sounding the alarm, it should be about the reality of climate change, not the prospect of climate accountability.
It’s no wonder fossil fuel companies are seeking to stay out of court. The facts are not on their side—and neither is the law. Why, then, are the insurers?
Make no mistake, real climate accountability would be destabilizing for the fossil fuel industry. But climate change is already more destabilizing—for everyone. The inevitable and transient upheaval that will come from holding polluters responsible for the harm they have caused will be far less destabilizing than the predicted and irreparable impacts of unchecked climate change.
Fossil-fueled climate destruction threatens human life, health, the economy, and vital ecosystems on which all depend. That reality should incentivize insurers to break free from fossil fuels faster and protect the public from climate peril, rather than insulate polluters from the climate costs they have knowingly unleashed.
The message to the insurance industry is clear: Insure our collective future and make fossil fuels a thing of the past.
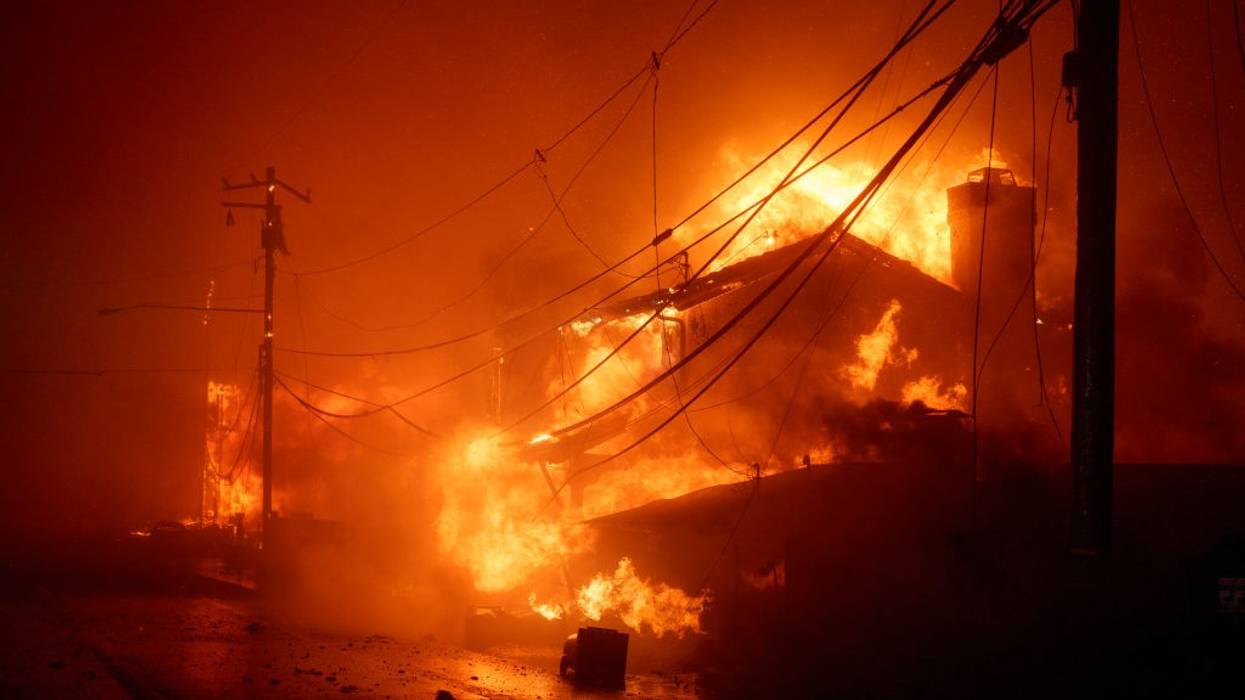
Recent personal experience suggests that the climate crisis can lead to financial disaster in the very short run; even those of us in our mid 80s are not immune.
Most people probably think that global warming will cause problems for their children and grandchildren, but not for themselves. I used to assume that those of us who are older need not worry.
But recent personal experience suggests that global warming can lead to financial disaster in the very short run. Even those of us in our mid 80s are not immune.
Several months ago, our house caught fire, forcing us into temporary accommodations. Only one room suffered major damage, but smoke permeated the whole house, requiring extensive remediation and destroying lots of furniture and clothing.
Fortunately, we had good insurance, which included coverage for contents and temporary housing as well as the cost of the repairs themselves.
If Dante were writing today, he could appropriately reserve a specially unpleasant level of his hell for the energy managers and politicians who are trying to stop the development of green energy.
Temporary housing is not cheap. We probably ran up $20,000 in hotel bills during the nearly two months before we could find more adequate housing. And temporary furnished housing itself is not cheap, easily amounting to thousands of dollars a month.
To state the obvious, owning a house without insuring it is highly risky. But what does this fact have to do with global warming?
Global warming has been setting off an increasing number of floods, fires, hurricanes, and tornadoes, damaging or destroying more and more homes. Up until now typical homes have been insured, which—as in our own case—has protected their owners from financial ruin.
But the money insurance companies pay for repairs or replacements has to be obtained through the premiums charged to homeowners. When the percentage of homes damaged by extreme weather increases, the insurance companies must increase what they charge for their coverage. If they do not do this, they will not be able to stay in business.
As a result, it is getting much more expensive to insure houses in many states, especially in California and some southeastern states. But the higher insurance premiums are making it more and more difficult for people to afford property insurance in the first place.
Some people may be forced to get no insurance, in effect self-insuring themselves. Since houses cost hundreds of thousands of dollars and are often the principal assets of families, those without insurance risk being wiped out financially.
And people cannot escape from this problem by renting a place to live instead of buying one. Landlords from whom people rent apartments and houses must increase rents in order to pay for the insurance they need.
Anybody following the news cannot help but be aware that floods, heat domes, hurricanes, and tornadoes are becoming more frequent and more devastating. And although climate has been always changing, the size and speed of the current changes cannot be explained away as just more of the same historical pattern.
A lot of future global heating is already “baked into” the world by carbon dioxide emitted by burning coal, oil, and gas during the last 200 years. But there is no reason why the human race should continue fouling its own nest now that we understand why climate change is accelerating.
At some point, people are going to stop falling for the propaganda emitted by coal, oil, and gas corporations; by political leaders these companies have bought; and by media organizations like Fox News catering to these wealthy and powerful interests.
Fortunately, new solar energy facilities are now cheaper than new atomic, coal, oil, or gas generators. And solar’s local intermittency, the principal weakness cited by anti-green spin doctors, will disappear when the already expanding distribution systems are united into a single worldwide high voltage direct current (HVDC) grid.
In recent decades we have seen similar movements to worldwide systems with telephones and computer networks. The technical and economic advantages of a worldwide electrical grid are so huge that it will be built.
Dante Alighieri (1265-1321) wrote about nine different “levels” of hell in "Inferno," the first part of his long narrative poem, The Divine Comedy. If Dante were writing today, he could appropriately reserve a specially unpleasant level of his hell for the energy managers and politicians who are trying to stop the development of green energy.
Hell has generally been considered a hot place. The longer these folks are allowed to continue putting their own interests over the general welfare, the more Earth itself may become like hell for its inhabitants.
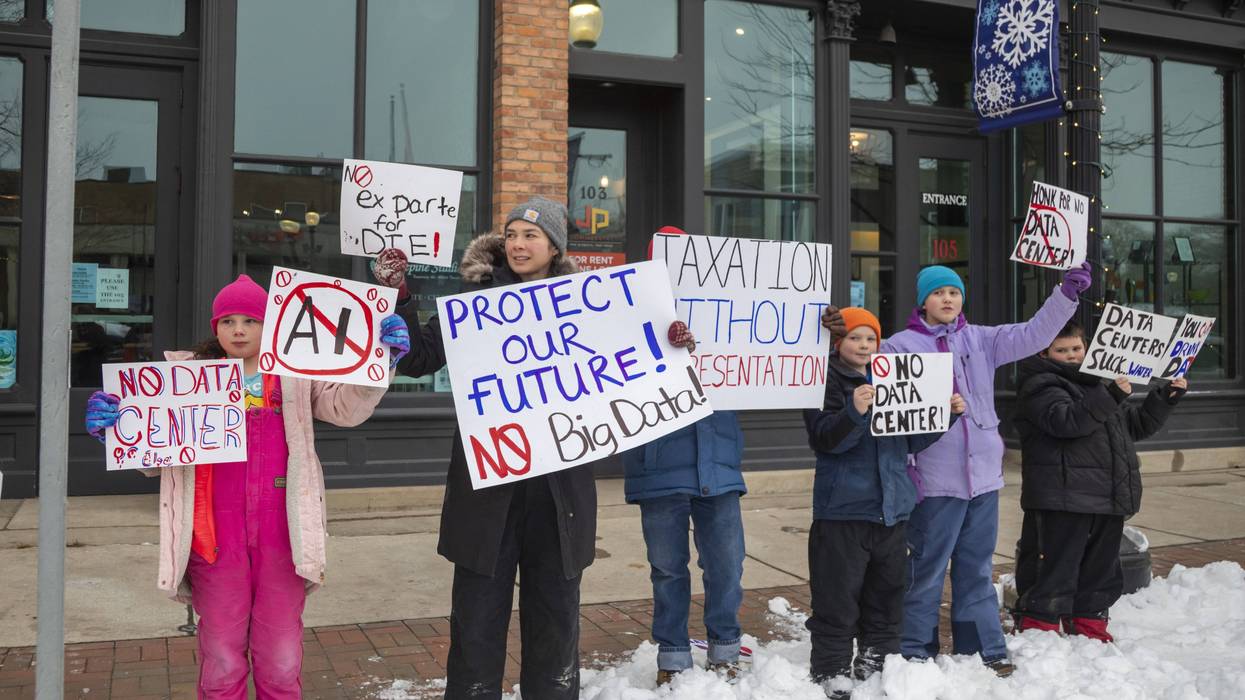
That’s why billionaire techno-fascists are trying so hard to imprison us within their AI-dominated world.
More focus is needed on the downsides of the AI “revolution,” which is better understood as a speculative bubble (built in part through shaky circular financing deals between chip maker Nvidia, cloud provider Oracle, and model builder OpenAI, among others) that’s liable to burst. If and when that happens, OpenAI CEO Sam Altman’s preemptive lobbying for a taxpayer-funded bailout is likely to pay off, leaving the public on the hook. That would be outrageous, of course, considering how much direct and indirect financial support tech giants have already received from federal and state governments, before and throughout the ongoing artificial intelligence frenzy. On the other hand, if AI “succeeds”—destroying millions of jobs, pillaging communities, and despoiling ecosystems in the process—working people will have subsidized our own subjugation. Widespread opposition to planned data centers across the political spectrum suggests that the public understands this.
Here’s a tangible downside: The prices of many essential goods are already rising as a result of the anti-democratic rush to build hyperscale data centers and the growing use of AI programs in numerous sectors. In what follows, we explain how the proliferation of both AI software (i.e., seemingly immaterial computational tools) and hardware (i.e., the resource-intensive and highly polluting infrastructure underpinning those tools) is driving up the costs of necessities now and in the future.
Energy-hungry AI systems require immense amounts of computing power. That’s why tech giants like Amazon, Google, Meta, and Microsoft are investing billions of dollars to expedite the construction of massive, primarily gas-powered data centers across the United States. This AI-driven surge in electricity demand, combined with the Trump administration’s ongoing attacks on renewable energy supply and battery storage, is putting increased strain on the power grid. The result? Higher utility bills.
According to a Bloomberg analysis published in 2025, “Wholesale electricity costs as much as 267% more than it did five years ago in areas near data centers. That’s being passed on to customers.” The rapid development of data centers connected to PJM Interconnection—the largest power grid operator in the United States, serving 67 million customers throughout the Midwest and Mid-Atlantic—increased the cost of procuring electricity by $9.3 billion from June 2024 to June 2025, with expenses only expected to rise further.
If this trend continues and data centers become the majority-users of a utility, then utilities may demand even deeper sacrifices from everyday ratepayers to keep their most powerful customers happy.
Residential ratepayers are shouldering this burden unfairly. As the beneficiaries of state-granted monopolies, for-profit utilities are subject to state regulation of prices. Public utility commissioners are supposed to set rates that enable customers to receive affordable power and utilities to cover operating costs and make enough profit to attract investors to fund infrastructure expansions and upgrades. For years, however, increasingly captured commissioners have been approving rate hike requests that pad the pockets of utility executives and shareholders (to the tune of $50 billion per year in excess profit, according to the American Economic Liberties Project).
Now, there’s mounting evidence that state regulators are subsidizing Big Tech’s out-of-control power consumption by forcing customers to fund discounted rates for data centers. This is a boon for investor-owned utilities, which profit from greater energy use. For the rest of us, it makes it harder to scrape by every month. If this trend continues and data centers become the majority-users of a utility, then utilities may demand even deeper sacrifices from everyday ratepayers to keep their most powerful customers happy.
Earlier this month, the US Centers for Medicare and Medicaid Services (CMS) launched the so-called Wasteful and Inappropriate Service Reduction (WISeR) Model. This pilot program allows six companies in six states to use AI to determine whether traditional Medicare enrollees’ requested medical care should be covered.
Reporting on this AI-powered prior authorization program last year, the New York Times noted that “similar algorithms used by insurers have been the subject of several high-profile lawsuits, which have asserted that the technology allowed the companies to swiftly deny large batches of claims and cut patients off from care in rehabilitation facilities.” Firms tapped to manage the WISeR Model “would have a strong financial incentive to deny claims,” the newspaper observed. “Medicare plans to pay them a share of the savings generated from rejections.”
An early warning that CMS Administrator Mehmet Oz is imposing “AI death panels” aimed at preventing seniors from accessing needed healthcare is apt. It’s also worth stressing that Medicare Advantage and private insurance plans have already been using AI-powered prior authorization, with costly and deadly effects for ordinary people.
Property insurers, too, are increasingly relying on AI to project—with zero transparency and questionable accuracy—climate risks, which is contributing to coverage withdrawals and rate hikes in communities around the United States. According to a recent report from McKinsey & Company, the insurance industry’s growing use of AI has led to “a 10 to 15% increase in premium growth.” While industry profits and executive compensation are on the rise, homeowners and renters alike are being hurt by the declining availability and affordability of home insurance. A climate and insurance-driven foreclosure wave, which would starve municipal budgets and could trigger a broader economic crisis, is a real possibility.
Two shoppers could walk into the same grocery store at the same time and purchase the same product—and yet be charged different prices. This was the conclusion of a recent experiment conducted by Groundwork Collaborative, Consumer Reports, and More Perfect Union. The study, which focused on online grocer Instacart, found that nearly three-quarters of items tested were offered to customers at multiple price points, with an average difference of 13% between the lowest and highest prices.
What the hell are we doing building ruinous housing for super-computers when we could—and should—be building healthy housing (and clean energy and mass transit) for people?
How is this possible? Unfortunately, this increasingly common practice of “surveillance pricing” is the logical outcome of allowing rent-seeking firms to transform our personal data into an asset that can be endlessly mined. AI is turbocharging this phenomenon, from RealPage’s rent-gouging software to Delta Air Line’s use of Fetcherr, an AI-fueled pricing technology.
AI is already wreaking profound havoc on public and environmental health. The rare earth elements used in the microchips that power AI systems tend to be mined in ecologically harmful ways. Data center construction implies habitat destruction, and completed facilities produce significant amounts of toxic electronic waste, which typically contains mercury, lead, and other hazardous materials. Data centers consume tremendous amounts of water, sometimes dispossessing local residents of access in the process. Making matters worse, Big Tech’s quest for cheap electricity is leading it to build data centers in all kinds of places, including drought-stricken states like Arizona and Nevada, compounding preexisting water shortages.
Moreover, most data centers are being powered by planet-heating fossil fuels, especially methane gas. In addition, forecasted AI-related energy shortfalls are leading utilities to keep aging coal plants running and even to revive particularly dirty “peaker” plants, while the use of on-site diesel generators is also growing.
On top of the fact that fossil fuel-powered data centers spew heat-trapping gasses into the atmosphere, research has shown that AI degrades air quality in other ways. Specifically, across its full lifecycle—from chip manufacturing to data center operation—AI contributes to the emission of fine particulate matter or soot, sulfur dioxide, and nitrogen dioxide. These pollutants are linked to numerous adverse health impacts, including lung cancer, asthma, heart attacks, cardiovascular disease, strokes, cognitive decline, and premature mortality. One study estimates that data centers are on track to account for at least 1,300 premature deaths and $20 billion in public health-related costs per year in the United States by 2030. These deleterious consequences are poised to hit already-disadvantaged populations the hardest. That includes the low-income, predominantly Black neighborhoods currently fighting back against Elon Musk’s xAI data centers in South Memphis.
What the hell are we doing building ruinous housing for super-computers when we could—and should—be building healthy housing (and clean energy and mass transit) for people? The opportunity costs of supporting Big Tech’s AI data center buildout are striking.
A new analysis from the Rhodium Group estimates that for the first time in two years, US greenhouse gas emissions increased in 2025. The 2.4% uptick in national GHG pollution was driven in large part by data centers and crypto mining. This regressive form of economic development is destabilizing the climate and leaving people less materially secure. It is also being pursued as a reactionary alternative to green economic populism.
It seems clear that a major reason why the ruling class is so heavily invested in AI’s triumph is because they dream of burying organized labor and worker demands once and for all.
Despite recent efforts to decouple climate and affordability, the two issues remain inextricably linked. There’s mounting evidence that climate inaction is exacerbating the cost-of-living crisis. The best way forward is to fight for policies that would simultaneously decarbonize and democratize our society, to confront climate chaos and grotesque inequality at the same time.
Failing to do so, as we are now amid AI-mania, will only lock-in more fossil fuel pollution, thus aggravating extreme weather and with it, supply chain disruptions and price shocks. Current and future generations will be forced to endure a more brutish and expensive world full of economic insecurity and uneven, but rampant, suffering.
Some AI-related costs have not yet been realized. But if Silicon Valley oligarchs succeed in empowering firms all across the economy to eliminate jobs (and deskill further pockets of the workforce), skyrocketing unemployment would empower bosses to suppress wages. It seems clear that a major reason why the ruling class is so heavily invested in AI’s triumph is because they dream of burying organized labor and worker demands once and for all. Meanwhile, the collision of declining pay and rising prices would push more and more people closer to the brink.
How are people supposed to enjoy the leisure time ostensibly provided by AI advancements if they can’t afford basic necessities? Is rapid access to information a net-positive no matter the quality of that information? Isn’t it more likely that society’s capacity for critical thinking will be further degraded? And if we deprive the next generation of literacy while immersing them in a poisoned information ecosystem, doesn’t that increase the likelihood that authoritarian demagogues will retain power?
That’s why billionaire techno-fascists are trying so hard to imprison us within their AI-dominated world. Whether by preempting regulation of AI inside existing borders or violently establishing new, regulation-free jurisdictions where they can impose their will, a tiny class of digital overlords and their political allies are seeking to end democracy so they can extract rents with no constraints. We can’t afford to let their dystopian vision become reality.
If the point of a healthcare system is to provide people with the healthcare they need, the Republican proposals are nonstarters.
During his first term, after repeatedly promising the country a terrific healthcare plan, Donald Trump famously commented, “Nobody knew that healthcare could be so complicated.” In fact, everyone who spent even a few minutes looking at the issue knew that healthcare was complicated. That is why Obamacare ended up being a hodgepodge that was pasted together to extend healthcare coverage as widely as possible. It is also the reason Trump and the Republicans never produced a healthcare plan in Trump’s first term.
The basic problem is that healthcare costs are hugely skewed. Ten percent of the population accounts for more than 60% of total spending, and just 1% accounts for 20% of spending. Most people have relatively low healthcare costs. The trick with healthcare is paying for small number of people who do have high costs.
The Republicans in Congress, along with Trump on alternate days, are pushing plans that are supposed to give choice to individuals and somehow take it away from insurers. It’s not clear what they think they are saying. They seem to still envision that people will buy insurance, as they do now in the Obamacare exchanges, but somehow that they will have more control in the Republican option.
There is one story they could envision, which would make it much easier for insurers to skew their pool. The Affordable Care Act (ACA) restricted what sort of plans could be offered in the exchanges in order to limit the ability for insurers to avoid high-cost individuals.
It would be possible to relax these restrictions to allow insurers to cherry pick their enrollees. For example, they could offer high-deductible plans, say $15,000 in payments, before any coverage kicked in.
The Republican healthcare plan is a rerun of the bluff and lie strategy they have been doing for more than 15 years.
No person with a serious health condition would buy this sort of plan since they know they would be paying at least $15,000 a year in medical expenses, and then a substantial fraction of everything above this amount, in addition to the premium itself. On the other hand, a low-cost plan with $15,000 deductible might look pretty good to someone in good health, whose medical expenses usually don’t run beyond the cost of annual checkup.
The Republicans can look like the great promoters of individual choice by allowing insurers to market these high-deductible plans. The problem is that healthy people will all gravitate to high-deductible plans, leaving only the people with serious health issues—the 10%—to buy plans with more modest deductibles.
These plans will then be ridiculously expensive since insurers are not going to insure people at a loss. If they have a pool with four or five times the average per person healthcare costs, they will charge a premium that is four five times the average cost, plus a margin for administrative costs and profits. This means that cancer survivors, people with heart disease, and other serious health conditions will be screwed, given the option of ridiculously expensive insurance or none at all.
The most painful part of this story is that we have all been around the block many times on this story. Unless Trump and the Republicans are extremely ignorant, which can never be ruled out, they are simply lying and hope that the media will let them get away with it. They have no brilliant plan to lower healthcare costs. They are simply proposing a scheme that will lower premiums for healthy people by screwing the ones who need healthcare most.
It amounts to lowering costs by not providing care. It’s like reducing the cost of food by not letting people eat. But if the point of a healthcare system is to provide people with the healthcare they need, the Republican proposals are nonstarters.
As a practical matter, contrary to what the Republicans and the media say, healthcare cost growth did slow sharply after Obamacare passed. That may not have been entirely due to Obamacare, but that is the reality. Too bad the Democratic consultants tell Democratic politicians not to talk about it.
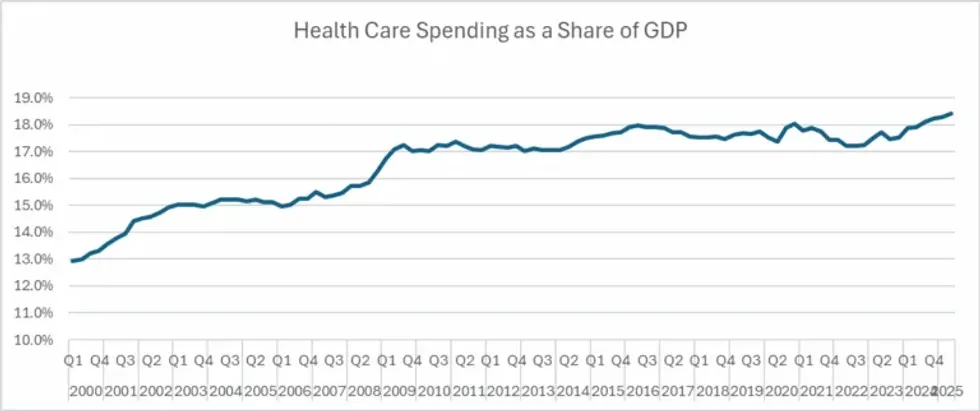
We do pay way too much for healthcare in the United States, but it is not because of Obamacare. We pay twice as much for our drugs, medical equipment, and doctors as people in other wealthy countries. These high payments persist because they are supported by powerful lobbies.
Some of us had hope that the Trump administration might take some steps to reduce these prices, especially in the case of drugs, since RFK, Jr. had railed against corruption in the pharmaceutical industry. Unfortunately, his tirades were limited to an evidence-free crusade against long-proven vaccines, which are not even a major source of profit for the industry.
Donald Trump talked about reducing drug prices 1,500% (really), but this mostly amounted to getting his name on a drug discount website for a small group of patients. We were spending 6.4% more on drugs in September of this year than in the same month in 2024. (September is the most recent month for which data are available.)
Trump has shown no interest in doing anything to lower the cost of medical equipment. And he has said nothing about lowering doctors’ fees, although some reshuffling of the Medicare reimbursement schedules may reduce overpayments to specialists and better pay for family practitioners. His immigration policies are going the wrong way here, making it even more difficult for foreign-trained medical students and doctors to practice here.
And there are the insurers themselves, which gobble up close to 25% of the money they pay out to providers in the form of administrative costs and profits. A recent study found that If we add in the cost imposed by insurers on hospitals, doctors’ offices, and other providers, they take up close to a third of healthcare expenses.
Trump has shown no interest in reining in the insurance industry apart from his silly talking point about giving people money directly to… wait, wait, buy their own unregulated insurance. That will do nothing to reduce the money flowing into the industry’s pockets.
The Republican healthcare plan is a rerun of the bluff and lie strategy they have been doing for more than 15 years. Given the right-wing control of much of the media, it could work for them politically. The tragic part of the story is that millions could end up without the healthcare they need.

"No matter how Republicans design their plan, their promise to take money out of the hands of big insurance companies and put it in the hands of patients will go unfulfilled."
US President Donald Trump and his Republican allies in Congress have made a show of criticizing insurance company greed as they stand firm against extending Affordable Care Act tax credits and offer ill-formed alternatives.
But a report published Wednesday by the office of Sen. Ron Wyden (D-Ore.) explains how a scheme endorsed by Trump and some top Republicans would further enrich insurance giants and big banks.
The report focuses on growing GOP support for a proposal that would give Americans money in tax-advantaged vehicles such as health savings accounts (HSAs) to help cover out-of-pocket costs. Last week, Trump championed the idea in the Oval Office, characterizing the proposal as a way to "forget this Obamacare madness."
In a social media post on Tuesday, Trump railed against "BIG, FAT, RICH INSURANCE COMPANIES" and doubled down on the idea of funding health savings accounts instead of extending the enhanced ACA tax credits.
But Wyden's report argues that "no matter how Republicans design their plan, their promise to take money out of the hands of big insurance companies and put it in the hands of patients will go unfulfilled, because the very arrangements they tout are administered by large financial institutions and the same big insurance companies."
The report notes that Optum Bank, a subsidiary of the corporate behemoth UnitedHealth Group, is one of the nation's largest administrators of HSAs and would be well-positioned to profit from the Republican plan.
"The numerous fees OptumBank charges, including a $20 Outbound Transfer Fee, a several-dollar monthly account maintenance fee, and a $2.50 ATM Transaction fee, flow directly out of consumers’ and patients’ pockets and into the coffers of the nation's largest health insurer," the report observes. "Even a fraction of these revenues adds up to massive profits."
"While some big insurance companies own HSA providers directly, others partner with large financial institutions to operate similar arrangements. Centene, for example, partners with Fidelity; Anthem partners with Bank of America," the report continues. "The common theme across these arrangements is massive profits for financial institutions and big insurance companies."
Wyden's report came as congressional Republicans worked to translate Trump's all-caps social media ramblings into coherent policy. Sen. Bill Cassidy (R-La.), chair of the Senate committee with jurisdiction over healthcare, is leading the effort as tens of millions of people brace for massive premium increases stemming from Republicans' refusal to extend enhanced ACA subsidies.
Cassidy has explained to reporters that the emerging GOP plan would entail Americans using existing ACA tax credits—not the enhanced subsidies that are set to lapse at the end of the year—to purchase high-deductible "bronze" plans on the insurance marketplace.
HSA funding from the federal government would then help enrollees cover out-of-pocket costs (HSA funds generally cannot be used to cover monthly premiums). Under the recently enacted Trump-GOP budget law, tax-advantaged HSAs are now available to everyone who buys a bronze plan on the ACA marketplace.
The average deductible for a bronze plan is $7,476 in 2026.
"Half-baked ideas that put more taxpayer dollars into health tax accounts will enrich big banks and insurance companies while saddling Americans with high premiums and deductibles," Wyden said in a statement on Wednesday. "Sending a few thousand dollars to Americans isn’t going to do them much good when they face a giant medical bill for a serious health diagnosis or even routine but expensive care, like giving birth in a hospital."
In a Fox News appearance on Wednesday, Cassidy likened his vision of an ideal health insurance marketplace to bargain-hunting for shampoo.
"By giving the patient the money herself... she becomes a wiser consumer," said Cassidy. "If she goes and gets two types of shampoo and one's a dollar cheaper, she'll get the cheaper one and the other one lowers their price."
Cassidy: "By giving the patient the money herself, she becomes a wiser consumer. If she goes and gets 2 types of shampoo and one is a dollar cheaper, she'll get the cheaper one and the other one lowers their price. One you give her the power of making the decision, she's gonna… pic.twitter.com/52u7IMJkFk
— Aaron Rupar (@atrupar) November 19, 2025
Ryan Cooper, managing editor of The American Prospect, wrote in response to the GOP healthcare scramble that "the stupidity is the point."
"For decades now, the Republican Party has been dedicated to the proposition that rich people are too highly taxed and the working and middle classes get too many benefits from the government. With the passage of the One Big Beautiful Bill, they have finally caught the car," Cooper wrote Tuesday. "Medicaid and Obamacare have been slashed to free up budget headroom for tax cuts heavily slanted to the wealthy."
"Republicans don’t have a 'healthcare plan' per se because this is their plan: to take your healthcare funding and give it to Elon Musk, Donald Trump, and the rest of the fascist billionaire class," he added.
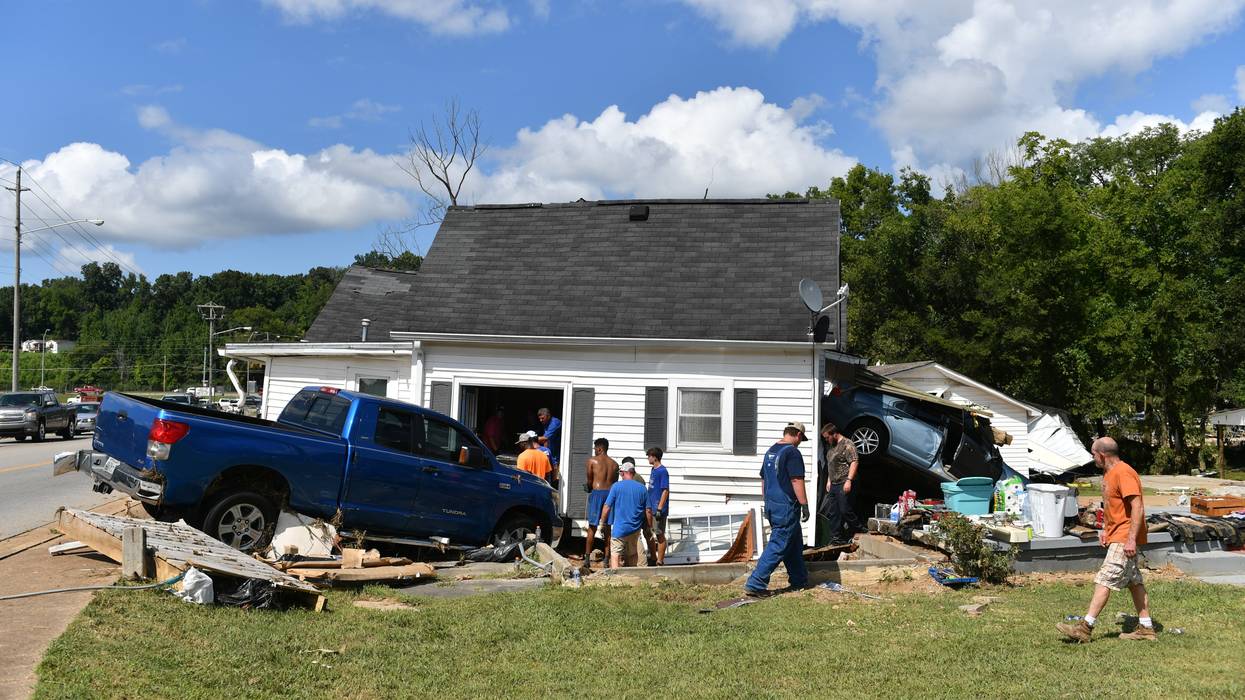
We too have a little bird trying to call our attention to a major problem. That bird is the insurance industry with its army of actuaries.
As the cost of insuring our houses escalates around the United States and the world, it appears that property insurance is acting like a canary in a coal mine.
Canaries used to be taken into coal mines because they served as an early warning system if dangerous gases were building up. Since the canaries were more sensitive to these gases than people, they protected the miners from life-threatening conditions. When the canary dropped dead, the miners could still get out.
Like the canaries, the actuaries who interpret data for insurance companies are more sensitive than most individual people to changes going on in the world. Actuaries earn big salaries because the financial health of their employers depends on them.
Things have already gotten so bad that the National Academies of Sciences, Engineering, and Medicine (NASEM) recently sponsored a webinar panel discussion: "Extreme Weather Events and Insurance: Households, Homeowners, and Risk." (This link will take you to a video of the event.)
Any coal miner who refused to evacuate a mine when the mine’s canary keeled over—perhaps saying, “I don’t believe there is any real danger here”—would not have been long for this world.
The panelists were located in the United States (Washington, DC and Madison, Wisconsin) and England (London and Cambridge). Climate changes are not limited to the United States, nor is awareness that we need to do something about them if we can.
The panelists were not grinding particular political axes. They were discussing the measured fact that an increasing number of extreme weather events are destroying valuable property—housing, commercial buildings, streets, bridges, etc.—requiring insurance company payouts to policyholders.
These insurance payouts must be financed by the premiums charged to people who are insuring their property. As damages increase, the premiums also have to increase. Although premiums may be regulated by state regulators, if they do not allow the needed increases insurance companies will pull out of doing business in that state.
As insurance companies pull out, it may become more and more difficult—perhaps even impossible—for people to insure their houses. But if a house cannot be insured, banks won’t finance a mortgage on it, and if it cannot be financed the owner may be unable to sell it.
For many people, their home is their primary investment, and they cannot afford to live in it if they cannot insure it. If it burned down or was otherwise destroyed, they would be wiped out financially. But if they cannot sell it, then the homeowner is a real pickle.
Disrupted housing markets can produce disastrous results for a country’s economy in general, as we Americans discovered during the recession beginning around 2008.
The impact of a world that is heating up is not being felt as much in the United States as in many other countries in Europe, Africa, and Asia which are suffering from unusually long bouts of very hot weather, flooding downpours alternating with extreme droughts, forest fires, etc. Some island nations may be literally wiped out as melting icebergs and glaciers increase sea level, putting them underwater.
But enough extreme weather events are already occurring in the United States that the insurance companies must make major increases in their prices.
Any coal miner who refused to evacuate a mine when the mine’s canary keeled over—perhaps saying, “I don’t believe there is any real danger here”—would not have been long for this world.
Americans who continue to politicize discussion of global warming—either denying its existence, its extent, its speed, or its seriousness—will be like that coal miner. We too have a little bird trying to call our attention to a major problem. That bird is the insurance industry with its army of actuaries. We ignore that warning at our own risk, and at the risk of our children and grandchildren.
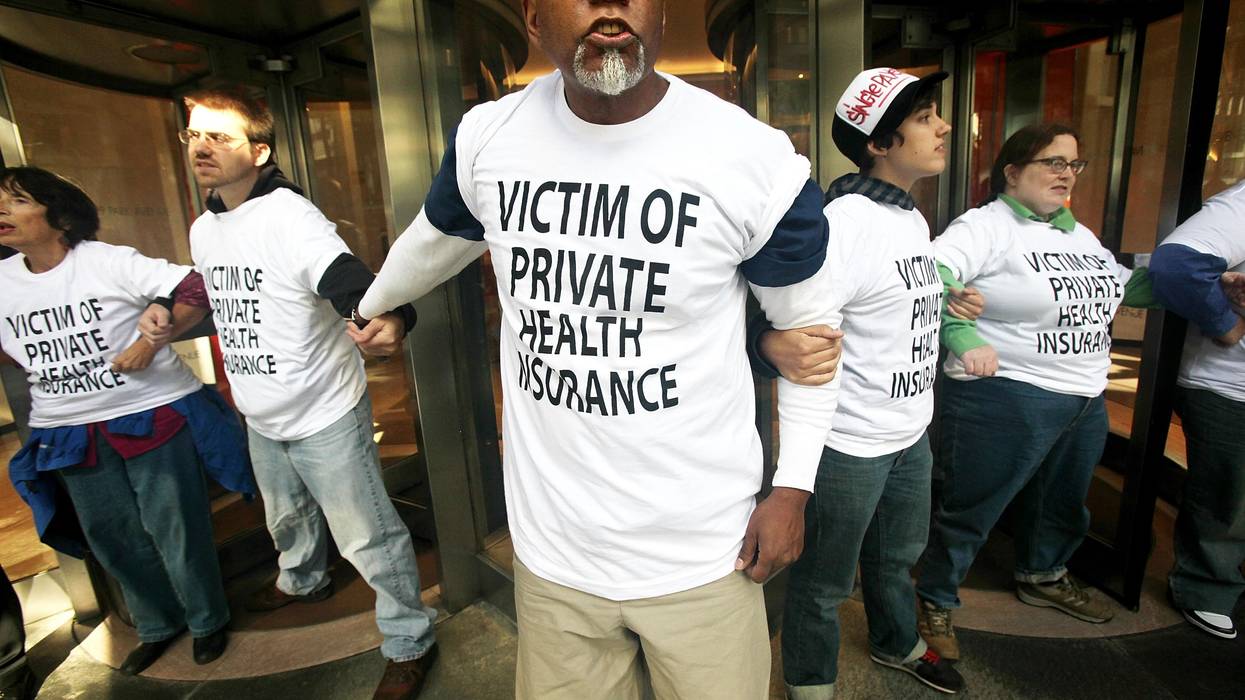
The harmful behaviors of profit-driven healthcare companies—from tax dodging to insurance denials to carelessness with patient safety—stem from the same illness: a disregard for the community they serve.
Even though most of us think of healthcare as a human right, the reality is that in the United States the provision of healthcare is big business. It places profits over people, demonstrating that priority through tax dodging, price gouging, insurance denials, and unsafe conditions for patients, as documented in a recent joint report from our two organizations, Americans for Tax Fairness and Community Catalyst.
The report, “Sick Profits,” highlights how seven healthcare corporations have together saved over $34 billion in federal taxes thanks to the 2017 Trump-GOP tax law recently extended by the current Trump administration and Republican Congress. They paid for those corporate tax breaks in part by cutting Medicaid and jeopardizing health coverage for 15 million people, and failing to preserve the enhanced premium tax credits for people buying health insurance through the Affordable Care Act (ACA) Marketplaces.
We currently have public policy that cuts taxes on corporations while ignoring nearly two-thirds of people who believe that big companies are not paying enough. Instead, healthcare corporations have each enjoyed hundreds of millions—in most cases, billions—of dollars in tax savings thanks to the Republican tax law, the most expensive part of which was a two-fifths cut in the corporate tax rate. They have also saved taxes by exploiting loopholes that the law (and its extension) failed to close, including in the accounting for stock options and the treatment of profits shifted offshore.
Not surprisingly, the companies examined in the report did not use their tax savings to lower prices, hire more providers, or improve patient care. No, the money went instead to higher executive compensation and increased payouts to shareholders through dividends and stock buybacks.
We must demand more transparency, fairer tax policy, and better oversight of these institutions.
Additionally, companies are maximizing their profits by simply not paying for care. By demanding “preauthorization” for a dizzying number of procedures then routinely denying approval, insurers can save billions at the expense of their policyholders. High percentages of initial denials are overturned on appeal, showing that “no” is simply the initial default position, taken in the hopes that patients and doctors won’t push the issue. Claim denials often result in medical debt and can also disrupt treatment for chronic medical conditions, delay or deny access to lifesaving care, and lead to avoidable complications—or even death.
Claim denials affect the health and well-being of people every day. They are people like Little John Cupp, who began feeling short of breath and experienced swelling in his feet and ankles. His doctor recommended a catheter exam to determine whether the arteries in his heart were blocked. However, the medical benefits management company EviCore (owned by Cigna) twice denied the catheter exam while eventually approving a much lower-cost stress test. The delay in diagnosis proved catastrophic. Less than two days after Mr. Cupp received the stress test, he died of cardiac arrest.
The tragedy of the end of Mr. Cupp’s life demonstrates the incredibly real risks that the first obstacle to getting care creates. Unfortunately, clearing that hurdle and receiving approval for care does not ensure quality. You could find yourself getting treatment at a facility saving money for shareholders by reducing staff and failing to maintain safe and hygienic conditions. NBC News aired a six-part investigation of hospital-operator HCA Holdings that uncovered, in the words of our report, “roaches in the operating room, leaking ceilings, essentially unmonitored vital signs, overworked nurses, overcrowded emergency rooms, closed departments, and other threats to patient health and safety.”
Or you may receive care at a facility owned or controlled by private equity interests. One cautionary tale is Prospect Medical Holdings, which operated hospitals and other health facilities in multiple states and was driven into bankruptcy after it was acquired by a private equity firm that extracted over $650 million in debt-financed dividends from the targeted company. While the private equity partners enjoyed lucrative payouts, patients suffered from unsanitary conditions, supply shortages, insufficient staffing, and shuttered departments.
Our diagnosis is simple but serious. The harmful behaviors of profit-driven healthcare companies—from tax dodging to insurance denials to carelessness with patient safety—stem from the same illness: a disregard for the community they serve. We must demand more transparency, fairer tax policy, and better oversight of these institutions. That means closing tax loopholes, raising the corporate tax rate, curbing the routine denials of coverage, and strengthening regulatory oversight of health facilities. That’s the only way to ensure that people’s needs are prioritized over corporate profits.
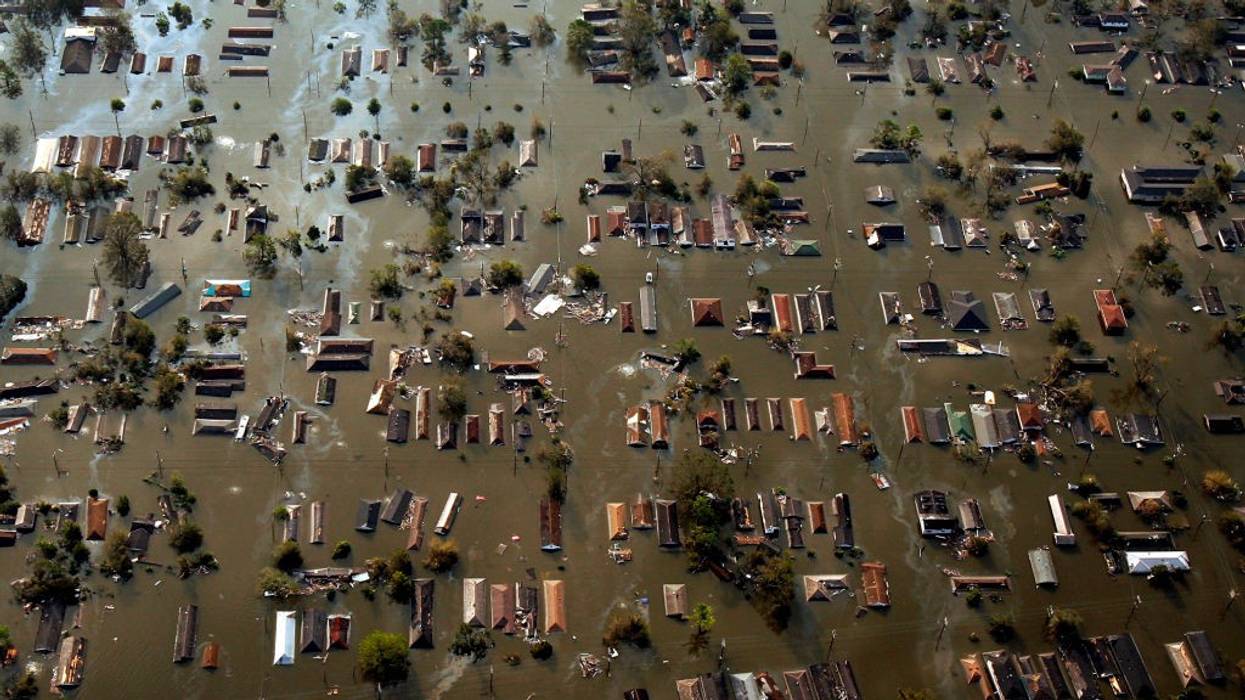
Hurricane Katrina not only exposed the vulnerability of communities to extreme weather events exacerbated by climate change, but also systemic injustices and a deeply flawed US insurance system.
It’s been 20 years since Hurricane Katrina struck the Gulf Coast of the United States, wreaking havoc in Louisiana, Mississippi, and Alabama. An estimated 1,833 people died in the hurricane and the flooding that ensued. The storm destroyed or damaged more than a million housing units and more than 200,000 homes, causing one of the largest relocations of people in US history.
In the months and years that followed, entrenched inequalities, questionable policy choices, and predatory practices by private insurers decided who could return home and rebuild. For instance, countless residents impacted by the hurricane learned too late that their standard homeowners’ insurance offered no protection against flood damage, leaving them to shoulder devastating repair costs themselves. In cities such as New Orleans, these dynamics further marginalized Black residents, who were more likely to live in flood-prone neighborhoods. The result was widespread and often permanent displacement, with longtime communities effectively erased from the map.
Hurricane Katrina not only exposed the vulnerability of communities to extreme weather events exacerbated by climate change, but also systemic injustices and a deeply flawed US insurance system. Private insurers pour billions of dollars into the fossil fuel industry, which is the main contributor to climate change. Thus, insurers help fuel the very crisis that is driving more frequent and severe climate disasters like Hurricane Katrina. Meanwhile, they are passing the financial risk of the escalating impact of climate change onto policyholders and forcing them to bear the costs of the crisis the industry itself helps perpetuate.
As climate-driven storms grow more frequent and increasingly destructive, the same insurance failures, housing crises, and inequitable recovery that followed Katrina now threaten communities nationwide. Two decades later, Katrina’s hard lessons cannot be ignored. Everyone deserves to live in safety and the opportunity to stay in the place they call home. Corporate greed and government negligence cannot continue to undermine these rights.
On August 29, 2005, Hurricane Katrina made landfall with winds that reached 140 miles per hour. These high-velocity winds drove a storm surge that raised sea levels 25 to 28 feet above normal along parts of the Mississippi coast, and 10 to 20 feet along the southeastern Louisiana coast. The surge breached protective levees, causing catastrophic flooding. Two days after the hurricane struck, 80% of the city of New Orleans was underwater. Other coastal towns and cities in Louisiana, Mississippi, Alabama, and along the western Florida panhandle also experienced significant storm surges and destructive winds, which caused widespread flooding and damage to homes.
Approximately 1.5 million people aged 16 years and older had to leave their residences in Louisiana, Mississippi, and Alabama because of Hurricane Katrina. In New Orleans, where the mayor issued a mandatory evacuation order, a population of around 500,000 was reduced to a few thousand people within a week of the storm.
As water was pumped out of the flooded areas and basic services and infrastructure were restored, New Orleanians were allowed to return. But tens of thousands were not able to do so. One year after Katrina, approximately 197,000 residents had not come back to the city; many relocated to the relatively close cities of Houston and Baton Rouge, but others as far away as Alaska and Massachusetts. Still today, many of those who evacuated the city, hoping to return, remain displaced. New Orleans’s metropolitan area population remains 20% below pre-Katrina levels.
The development of New Orleans has been fraught with injustices. Racial segregation, redlining, and chronic underinvestment in Black communities pushed residents and renters into areas with crumbling infrastructure, poorer-quality homes, and greater exposure to environmental hazards and contaminants.
When Katrina hit, Black residents were concentrated in the most vulnerable parts of New Orleans, located well below sea level and poorly protected by inadequate levees. Accordingly, neighborhoods with the highest percentages of Black residents saw greater housing destruction from the storm.
Did You Know?
The disparate impact of climate disasters on property and infrastructure in US minority communities is the result of nearly a century of discriminatory home lending and insurance policies.
In the 1930s, the US federal government used a rating system in its low-cost home loan program to assess lending risk. Assessors created maps ranking the perceived risk of lending in certain neighborhoods, with race often used as the determining factor in assessing a community’s risk level. Black and immigrant neighborhoods were typically rated as “hazardous” and outlined in red, warning lenders that the area was a perilous place to lend money. Known as redlining, these and other discriminatory practices led to a lack of investment in minority communities.
This lack of financial access resulted in shoddy construction and poor infrastructure that have made minority neighborhoods less resilient to climate disasters and more prone to other financial risks. For instance, insurers are more likely to increase premiums if they determine that properties are less resilient to climate damage. This new financial practice is known as bluelining, and it occurs when insurers raise their prices or pull out of areas that they perceive to be at greater environmental risk.
For Lousina’s Black residents, Katrina’s damage was compounded by discriminatory recovery policies that deepened inequalities. After the storm, the federally funded Road Home program was launched to help residents repair or rebuild damaged homes. It offered grants of up to $150,000 per homeowner, but payments were based on whichever was lower—the home’s pre-storm value or the cost to rebuild.
Because property values in Black neighborhoods were often far lower than in white neighborhoods, this meant many Black homeowners would receive only a fraction of what they needed to rebuild. In one case, a woman had rebuilding costs of over $150,000, but because the estimated value of her home pre-storm was much lower, she would’ve received an essentially useless grant of $1,400. As a result, the program was alleged to discriminate against Black homeowners, and a federal class action suit was filed on November 12, 2008, on behalf of 20,000 homeowners. The litigation settled with Louisiana agreeing to reward approximately 1,300 homeowners with $62 million in additional compensation.
Renters fared no better. Hurricane Katrina damaged or destroyed 82,000 rental units in Louisiana, 20% of which were affordable to extremely low-income households. The impact on public and federally subsidized rentals was especially severe. In New Orleans, public-housing residents were displaced at a rate of nearly 90%. And reconstruction policies only exacerbated the disparities these residents faced.
Consider this.
Before the storm hit and floodwaters rose, the Housing Authority of New Orleans evacuated all residents living in its 7,379 public housing units. After the waters receded, residents were allowed to return to approximately 1,600 units. Most other units were sealed off with steel doors and barbed wire—officially due to storm damage—before being slated for demolition. Yet, the redevelopment that followed included far fewer mixed-income apartments. By 2010, five years after the hurricane, less than half of the original 7,379 units were open in any form. The dramatic decrease in public housing contributed to the permanent displacement of many of New Orleans’ longtime residents.
After Katrina, renters faced a range of economic pressures. Many landlords delayed repairs or rebuilding, especially in low-income areas, which are seen as less profitable. Some used the disaster as an opportunity to renovate and target higher-paying tenants, further shrinking the supply of affordable rentals. Within five years of the Hurricane, the stock of mid-priced housing units in New Orleans had declined by more than two-thirds, pushing the median rent from $689 in 2004 to $876 in 2009. These rising costs hit Black residents hardest, forcing many to leave and permanently altering the city’s character.
Even those who could afford to return to New Orleans and buy a new home after Katrina faced soaring prices—up 14% in the first year alone—as demand outpaced the reduced housing supply. In addition, homeowners’ insurance premiums jumped 22% in Louisiana between 2005 and 2007, adding yet another barrier to homeownership.
Then, as now, and to the surprise of many victims of the Hurricane, standard home insurance policies in the US did not protect homeowners from floodwater damage. This means residents must buy additional flood insurance to be protected in the event of a disaster like Katrina.
New Orleans residents had among the highest participation rates in the country in the National Flood Insurance Program (NFIP), a federal government program that provides flood insurance to homeowners, renters, and businesses. However, the majority of residents in areas affected by Katrina had not purchased flood insurance. Uninsured property losses due to flooding were economically devastating, exceeding an estimated $41.1 billion (USD 100 billion in 2024 prices). In addition, the NFIP incurred some $16.1 billion in losses and a deficit exceeding $18 billion as a direct result of the flooding caused by Katrina.
Even for New Orleanians with flood insurance, coverage likely fell short. Policies typically covered about $152,000—the city’s median house price at the time. But this was rarely enough to replace the damaged household contents or to pay residents for temporary housing while their home was uninhabitable.
More and more, whether people hit by climate-driven storms get anything from their insurers depends not on the fact that their homes were damaged, but on how they were damaged.
While the standard home insurance policy does not cover water damage from a hurricane, it does cover wind damage. This gap left residents and insurers arguing about whether Katrina’s destruction to their homes was caused by its high-velocity winds or the flooding that followed, with multiple lawsuits challenging the validity of flood exclusions in insurance policies. Even before the flooding receded and residents of Louisiana and Mississippi could start to rebuild their lives, courts were inundated with litigation, with about 6,600 insurance-related lawsuits being instigated in the US District Court. Yet, Katrina’s destructive flooding was driven by a storm surge powered by the hurricane’s high winds—the very peril homeowners’ policies are supposed to cover.
On September 15, 2005, Mississippi’s Attorney General Jim Hood filed a case against five of the largest homeowners’ insurers in the state. Attorney General Hood sought a court declaration that the flood exclusion provision in standard home insurance policies was “void and unenforceable” and in violation “of the public policy of the State of Mississippi.” However, in that case and others, courts ruled that the flood exclusions were spelled out clearly in homeowners’ insurance policies and did not violate public policy.
The exclusion of water damage from insurance coverage remains a present issue for existing homeowners. According to the Federal Emergency Management Agency, since 1996, 99% of US counties have been impacted by flooding, but only 4% of homeowners have flood insurance. And, more importantly, over half (56%) of American homeowners don’t know that their home insurance policy excludes flood damage. As hurricane season intensifies, many homeowners will be shocked to learn that their insurance does not cover flood loss.
After Katrina, some insurers exploited the false dichotomy between wind and water damage, classifying losses as water damage to shift liability onto homeowners or the NFIP.
In 2013, a federal jury in Mississippi found that State Farm Fire and Casualty Co. defrauded the NFIP after avoiding covering a policyholder’s wind losses from Katrina by blaming the damage on storm surge, which is covered by federal flood insurance. Almost 10 years later, in August 2022, State Farm settled the case, agreeing to pay $100 million to the federal government.
State Farm was not the only insurer engaged in nefarious behavior, attributing Hurricane Katrina damage to flooding instead of wind. In oral argument before the Mississippi Supreme Court in 2009, insurance company USAA publicly admitted that it shifted its own costs to the NFIP and thus taxpayers.
The false dichotomy between the wind and water damage resulting from a hurricane remains nebulous. The damage caused by Hurricane Ian in Florida, North Carolina, and South Carolina in 2022, with its record-high wind speeds, generated $63 billion in private insurance claims. In contrast, 2018’s Hurricane Florence primarily caused water—not wind—damage in North and South Carolina, leaving uninsured flood losses estimated at nearly $20 billion and letting private insurers largely escape liability. More and more, whether people hit by climate-driven storms get anything from their insurers depends not on the fact that their homes were damaged, but on how they were damaged.
Hurricane Katrina exposed widespread gaps in home insurance coverage that persist today. In the 20 years since Katrina, unmitigated climate change has fueled rising temperatures and made extreme weather events such as hurricanes both more frequent and more severe. As storms grow costlier and more destructive, insurers have raised home insurance premiums and declined to renew many policies, leaving households with fewer options for protection. This escalating cycle has produced today’s insurance crisis.
Federal and state lawmakers must respond. The federal government must reform the NFIP to improve federal flood insurance and ensure it provides affordable coverage for more hazards. At the same time, the NFIP should do more to support community-based mitigation. States, meanwhile, must use their regulatory authority over insurance markets to address skyrocketing insurance costs and growing coverage gaps resulting from mounting climate change impacts.
Regulators should adopt legislation, like New York’s Insure Our Future bill, to prohibit insurers from underwriting new fossil fuel projects, require them to phase out support for existing projects, and force insurers to divest from fossil fuel companies.
The insurance industry cannot ignore its role in fueling the very crisis it now faces. Climate change-induced disasters are indisputably driven by fossil fuel emissions. And insurance companies facilitate climate change by investing in fossil fuel companies and underwriting fossil fuel projects. US insurance companies have investments of more than $500 billion in fossil fuel-related assets, including coal, oil, and gas. In 2022 alone, insurers worldwide collected $21 billion in premiums for underwriting fossil fuel projects—directly enabling their expansion.
Regulators should adopt legislation, like New York’s Insure Our Future bill, to prohibit insurers from underwriting new fossil fuel projects, require them to phase out support for existing projects, and force insurers to divest from fossil fuel companies. Without bold action, insurers will continue to profit from climate destruction while leaving families and communities to bear the costs.
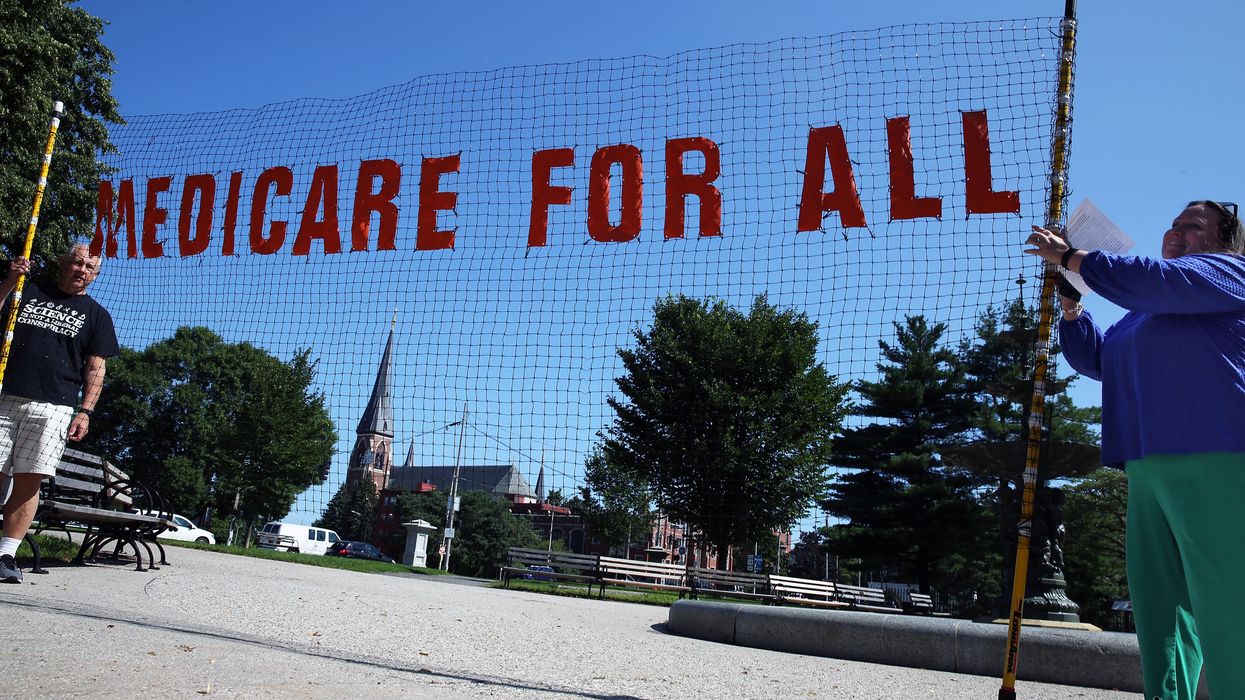
If Democrats want to convince voters that they will make their lives better, they need to be identified with policies that will make their lives better.
At a time when we don’t know if we will have real elections in 2026 and 2028, it may seem a bit absurd to be plotting an agenda for Democrats, but it is essential. While polls show approval for US President Donald Trump and Republicans is plummeting, people are not flocking back to the Democrats.
A major reason is that people don’t know what Democrats stand for, other than not being Donald Trump. While that is an important credential, democracy does still mean something to many people, and that alone is not likely to convince voters to come out and pull the Democratic lever.
Most people do feel they are being screwed by the rich. They have a good case, which has gotten a lot better in the seven months Donald Trump has been in office. His endless tax breaks for the rich and corporations, coupled with all sorts of government giveaways from his crypto scams to giving the right to dump their crap on our lawns (i.e. pollute without constraints), should convince any doubters that we have a government by and for the rich.
But the Democrats need to make the case that they are something different. That will be hard when so many are openly in bed with crypto scammers and other Wall Street high rollers.
Moving to universal Medicare will be difficult both politically and practically, but it can be done.
If they want to convince voters that they will make their lives better, they need to be identified with policies that will make their lives better. Some of these should be obvious.
Raising the minimum wage to $18 an hour is a straightforward one. Minimum wage hikes always poll well, and when referendums have appeared on the ballot, they win even in heavily Republican states like Arkansas. And there is now extensive research showing that modest increases in the minimum wage do not result in job loss.
Workers want to join unions but are stifled by current labor law. Strong protections for worker rights should go a long way here. Suppose we not only had a worker-friendly National Labor Relations Board, but we also had serious sanctions for violations. I suspect fewer bosses would break the law if they were looking at jail time.
That would at least be symmetric. A union official faces jail time if they ignore a court’s back to work order. It seems an employer who continually breaks the law to obstruct workers’ efforts to organize should face similar consequences.
But an item that really should be top of the list is universal Medicare. This had seemed like a big lift to me and many others, which would require a long phase-in period. But Trump and the Republicans’ radical attack on the current hodgepodge system of providing healthcare, coupled with Trump’s extreme uses of executive power, convinced me that we can move quickly in this direction.
In moving toward universal Medicare, it is important to recognize the distinction between the budgetary implications and the real demands on resources. There is no doubt that a universal Medicare program will require a large amount of additional spending, although the increase can be exaggerated.
We will save at least $400 billion a year (5% of the federal budget) on what we pay the insurance industry to shuffle papers and deny people care. Prescription drugs and other pharmaceutical products would also be cheap if the government didn’t give out patent monopolies for these items. We will spend over $700 billion this year for drugs that would likely cost around $150 billion in a free market. The difference of $550 billion comes to $4,400 per household annually.
Contrary to what is often asserted, government makes drugs expensive. We need less government to make them cheap, not more. The same is true for medical equipment, like scanning machines.
We do need to provide incentives to develop new drugs and equipment, but there are alternatives to granting patent monopolies. We can pay people. The National Institutes of Health and other government agencies used to spend over $50 billion a year on biomedical research.
Insofar as it is necessary to raise revenue, Trump has shown us how easy it can be.
We can triple this sum and make all findings fully open source so that new drugs can be produced as generics the day they are approved. This would both make drugs cheap and eliminate most of the motivation for corruption in the pharmaceutical industry.
It’s also worth pointing out that a major reason insurers are so determined to limit care is the high prices of drugs and medical equipment. If a year’s treatment with a drug costs $100,000, as is the case with some new cancer drugs, an insurer will try to avoid paying it. If the cost were around $1,000, which would likely be the case in the absence of patent monopolies, there would be little concern about using the drug, if a doctor determined it to be the best treatment.
But even moving quickly to bring costs down in the healthcare sector, we will still need considerably more money to pay for a universal healthcare system than what the government pays for our current system. This is a place where Trump’s erratic policies have done us a great service.
First, we need to remember that the actual constraint to the government’s spending is not revenue, it is the availability of real resources. In the case of universal Medicare that means the doctors, physicians’ assistants, nurses, medical technicians, home healthcare aides, and other people who directly provide healthcare to patients.
We currently have over 18 million employed in these jobs. We would need considerably more to adequately meet the country’s healthcare needs. We already have shortages in many occupations, and there is a huge problem of access in rural areas and some inner-city neighborhoods.
We can’t immediately fill this shortfall since many of these fields require years of training. If the country moved to universal Medicare, radically ramping up training programs in healthcare fields should be a top priority. We need to go the Immigration and Customs Enforcement route here and offer huge recruitment bonuses. People can be paid tens of thousands of dollars for entering and then completing programs in physical therapy, nursing, and other health-related fields.
We also should be turning to foreign countries for assistance. There already are large numbers of immigrants working in healthcare in the United States. The Trump administration is hard at work deporting many of them. That will make it more difficult to attract foreign healthcare workers in the future, but hopefully a progressive Democratic administration can convince the world that the United States has returned to sanity.
There is an issue that by bringing large numbers of healthcare workers to the United States, especially doctors, we will be depriving poorer countries of desperately needed healthcare providers. There is a simple answer to this. We pay these countries to train two or three healthcare workers for every one that comes here.
This is a classic story of the winners from trade compensating the losers that economists always talk about when pushing trade deals through Congress, but never actually happens after they take effect. The logic is actually solid; the problem is the political will. Anyhow, we can give this compensation and create a win-win situation, if there is political support for it.
Getting back to the budget situation, the problem from large deficits is that they can push the economy beyond its capacity and lead to inflation. That doesn’t seem to be the problem at present, where the economy is showing considerable weakness. It’s hard to say what the world will look like if and when a progressive Democratic administration comes into power.
Insofar as it is necessary to raise revenue, Trump has shown us how easy it can be. He set the country on a course to raise close to $400 billion a year in taxes (more than $4 trillion over a decade), without even getting approval from Congress.
His method of ad hoc tariffs is probably about the worst way to raise revenue, but it does show that it is possible to raise large amounts of revenue. The better routes would be raising income taxes on high-end earners and a corporate income tax that we actually collect. (Either mandate companies give the government non-voting shares of corporate stock, or make returns to shareholders the basis for the income tax; proposals that are too simple for great policy minds to understand.)
We also should apply a modest sales tax to stock trades of say 0.1%. This will hugely reduce the bloat in the financial sector and cost the vast majority of households nothing. The politicians whining that a middle-class family with $400,000 in a 401(k) could end up paying another $100 a year in taxes should be told to eat shit and die. They are shilling for Wall Street: full stop.
Anyhow, the dire budget calculations showing that if we never do anything about deficits, in 2040 or 2050 we will have an incredibly high interest burden might be a good way to employ budget wonks, but they should not be treated as serious basis for policy. We can and do change budgets all the time, and if we do face problems where deficits are pushing the economy beyond its capacity, we know how to raise taxes and, if need be, cut less useful spending.
Moving to universal Medicare will be difficult both politically and practically, but it can be done. Democrats really should have it at the center of their political agenda.
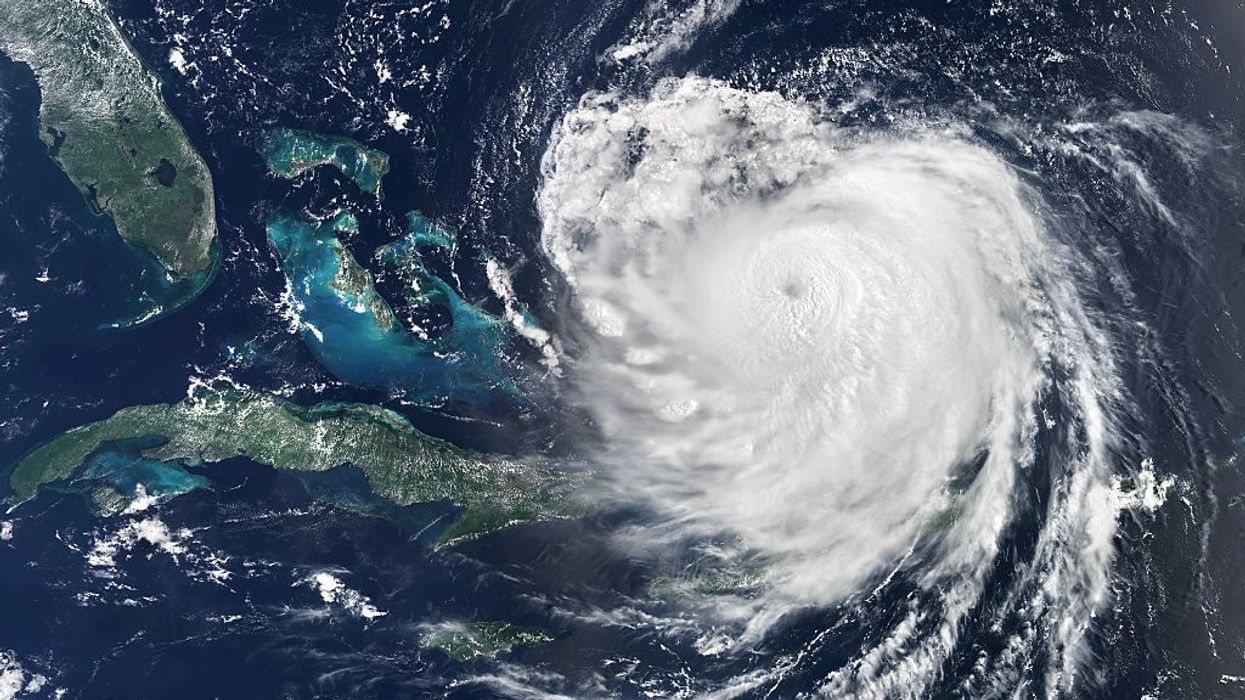
With the federal government abdicating its responsibility, state and local leaders must step up. They have the power and duty to act.
A deadly storm has already claimed at least 120 lives and caused widespread devastation in Texas. Hurricane Erin has now unleashed catastrophic flooding in North Carolina before racing toward the Northeast—and hurricane season has only just begun. Storms are growing more destructive, driven by fossil fuels that warm our oceans and destabilize the climate, while the vulnerable petrochemical infrastructure in their path multiplies the danger. As the storms strengthen, US protections are unraveling, leaving millions exposed.
Every year, hurricanes grow more intense—fueled by warming oceans and a rapidly changing climate driven by fossil fuels. But it’s not just the storms becoming more dangerous. It’s the fossil fuel infrastructure in their path. It’s the toxic pollution released when storms strike. It’s the insurance companies abandoning communities in the aftermath. And it’s the US government retreating from its duty to protect.
The Gulf Coast—home to more than 84% of US plastics’ production and to nearly half of US petroleum refining capacity—is bracing for more than five major hurricanes predicted for the Atlantic Ocean this year. With each hurricane comes the risk of fires, explosions, and toxic releases—not just for these facilities, but for the surrounding communities. More than 870 highly hazardous chemical facilities are located within 50 miles of the hurricane-prone Gulf Coast, and more than 4 million residents and 1,500 schools sit within a 1.5-mile radius of a high-risk chemical facility in the region.
Nationally, 39% of the US population lives within 3 miles of a high-risk chemical facility.
And yet, as we brace for the next deadly storm, US President Donald Trump has axed critical weather forecasting jobs and announced plans to eliminate the Federal Emergency Management Agency (FEMA) altogether, leaving communities even more vulnerable in the face of escalating disaster.
But the threats don’t stop there. The US government is systematically dismantling our first line of defense. Since Trump took office in 2024, the administration has:
Fossil fuel infrastructure isn’t just at risk during storms—it supercharges the storms themselves. The industry is a major driver of global warming, accelerating the rising temperatures and warming oceans that exacerbate hurricanes. And even as storms grow more destructive, the industry is doubling down: 80% of proposed new petrochemical projects are sited within 20 miles of a hurricane or tropical storm’s path over the past decade. This means entire corridors already battered by climate disasters are being locked into even greater danger.
When disaster strikes, oil, gas, and petrochemical facilities release hazardous pollutants into the air and water, compounding the crisis for nearby communities, which are often low-income and disproportionately Black, brown, and Indigenous.
When Hurricane Katrina struck, it slammed into 466 facilities that handle hazardous chemicals and petrochemicals. More than 200 onshore releases of hazardous chemicals, petroleum, or natural gas were reported. The storm caused at least 10 oil spills, releasing more than 7.4 million gallons of oil into Gulf Coast waterways—more than two-thirds the volume spilled during the Exxon Valdez disaster, one of the worst in US history. Together, Hurricanes Katrina and Rita, just a month apart, shut down nearly a quarter of the country’s refining capacity.
And during Hurricane Harvey, Houston’s petrochemical plants and refineries released millions of pounds of pollutants. Flooding at the Arkema Petrochemical plant disabled the plant’s refrigeration system, triggering a massive explosion that sent black plumes and toxic fumes into the skies and forced evacuations across a community already on edge. An investigation by the Chemical Safety Board—recently dismantled by the Trump administration—determined that requirements of the Environmental Protection Agency’s Risk Management Program—currently being rolled back by the EPA—could have prevented this very disaster.
As extreme weather events surge, so do insurance premiums—while coverage vanishes for those living in harm’s way.
For many climate-vulnerable communities, home insurance is no longer affordable—or available. Since 2019, US home insurance rates have jumped nearly 38%. Louisiana, Texas, and Pennsylvania—all major fossil fuel corridors—rank among the top six most expensive states to insure a home. Home insurance premiums rose by 10% or more across 40 states from 2021 to 2024. Renters aren’t immune as landlords pass along skyrocketing insurance costs.
Insurance math: Communities facing hurricanes, flooding, and fires? Too risky to insure. Companies driving the disasters? Coverage and cash.
Insurers claim payouts from climate disasters are driving up costs. The truth is, insurers are investing in the very industries making those disasters worse—and raking in profits. In Louisiana, insurance companies are making $55 in profits for every $1 in underwriting losses. This profitability is not unique: NAIC data shows the property and casualty sector made an all-time high of $167 billion profits in 2024—up 91% from 2023, and 330% from 2022.
At the same time, the US insurance industry continues to bankroll fossil fuels, holding more than $500 billion in fossil fuel-related assets as of 2019 (the most recent data set available); a pattern of investing that is unlikely to have substantially changed since. While refusing to insure homeowners in climate-exposed communities, many insurers are simultaneously underwriting new fossil fuel infrastructure. At least 35 insurance companies are backing methane gas (LNG) export terminals across the Gulf South—some of the very same companies, including AIG, Chubb, and Liberty Mutual, that are raising premiums or pulling out of the housing market in vulnerable regions entirely.
Insurance math: Communities facing hurricanes, flooding, and fires? Too risky to insure. Companies driving the disasters? Coverage and cash.
Rather than confronting the crisis, insurance companies are fueling it—protecting profits and abandoning people. This isn’t just hypocrisy, it’s a business model, one built on extraction and shifting costs onto the public.
The system is rigged. Those most responsible are rewarded, while those most vulnerable are left to suffer the storms alone.
We all deserve somewhere safe to live—free from the dread of the next hurricane, the next explosion, or the next rollback of basic protections. But fossil fuel polluters—and the insurance companies profiting from their harm—are robbing us.
We will not accept this endless cycle of crisis. We deserve safety, especially from the governments whose duty it is to protect us. We deserve safety from storms and from toxic spills. We deserve a government that protects its people—and agencies that do their jobs: defending public health and the environment, not doing the bidding of polluters.
With the federal government abdicating its responsibility, state and local leaders must step up. They have the power and duty to act. It’s time for states, especially those in the eye of the storm, to lead where the federal government is failing. States must:
When Hurricane Katrina devastated Louisiana, it left behind a $170 billion bill. The federal government stepped in for $120 billion. But with FEMA on the chopping block, that kind of relief may never come again. If federal protections vanish, the financial and human cost of the next disaster will fall squarely on states—and the people who live in them.
The climate crisis isn’t waiting. The storms are here. Will our leaders meet the moment—or leave us to weather the disaster alone?