SUBSCRIBE TO OUR FREE NEWSLETTER
Daily news & progressive opinion—funded by the people, not the corporations—delivered straight to your inbox.
5
#000000
#FFFFFF
To donate by check, phone, or other method, see our More Ways to Give page.
Daily news & progressive opinion—funded by the people, not the corporations—delivered straight to your inbox.
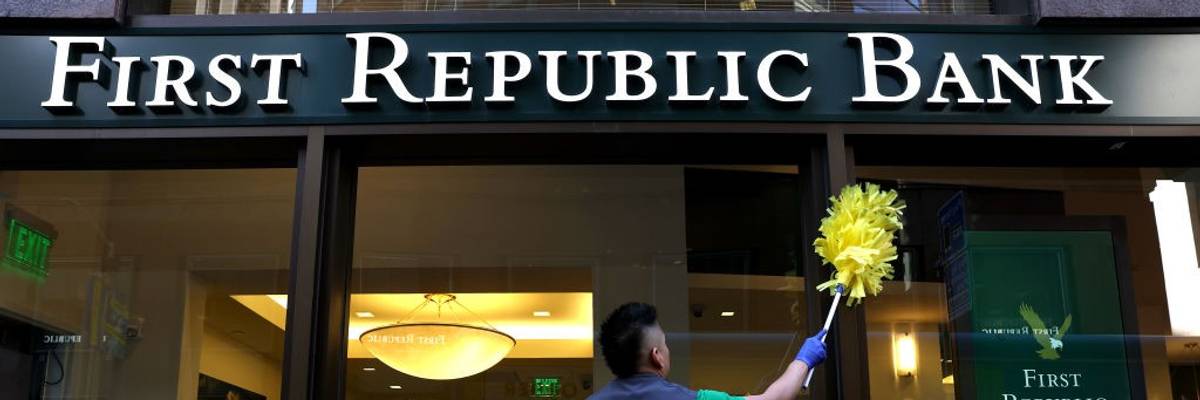
A worker cleans the exterior of a First Republic bankon April 26, 2023 in San Francisco, California.
"Ultimately taxpayers will be on the hook," said the Democratic senator from Massachusetts.
Sen. Elizabeth Warren said Monday that the latest government bailout of a failing Wall Street institution shows how much the financial system remains rigged in favor of powerful banks and that it is beyond time for Congress to step up with increased oversight and reforms.
Federal regulators Monday announced they had seized the entirety of First Republic Bank and sold it to JPMorgan Chase for an undisclosed price—the latest fallout from a deregulated banking system in which the U.S. government has stepped in to backstop Wall Street.
"The failure of First Republic Bank shows how deregulation has made the too big to fail problem even worse," said Warren in response to the news. "A poorly supervised bank was snapped up by an even bigger bank—ultimately taxpayers will be on the hook. Congress needs to make major reforms to fix a broken banking system."
"Once again, we're reaping the bitter harvest of financial deregulation." —Lisa Gilbert, Public Citizen
Last week, as Common Dreams reported, the Federal Reserve issued the results of an internal investigation which showed the collapse of Silicon Valley Bank earlier this year was at least partly due to the 2018 deregulation of mid-sized banks that was approved by Congress and signed into law by former President Donald Trump.
In an early morning statement, the Federal Deposit Insurance Corporation (FDIC) said First Republic—which has been teetering on collapse for weeks—was first closed before being sold to banking giant JPMorgan following a bidding process for the smaller bank's assets.
"As part of the transaction," said the FDIC, "First Republic Bank's 84 offices in eight states will reopen as branches of JPMorgan Chase Bank, National Association, today during normal business hours. All depositors of First Republic Bank will become depositors of JPMorgan Chase Bank, National Association, and will have full access to all of their deposits."
According to the Washington Post:
The acquisition makes JPMorgan, already the nation’s largest bank, even bigger and could draw political scrutiny from progressive Democrats in Washington.
First Republic failed despite having received a $30 billion lifeline from 11 of the country's largest banks in March. JPMorgan said the $30 billion would be repaid after the deal closes. Overall, First Republic will go down in history as the second largest U.S. bank by assets to collapse after Washington Mutual, which failed during the financial crisis of 2008.
FDIC said the cost of the deal to the Deposit Insurance Fund which it manages will be approximately $13 billion.
"In other words, good banks and their customers pay to insure bad banks," said Richard Painter, law professor and former White House ethics chief. "How much did First Republic's execs who created this mess have to pay? If we made them pay, First Republic might not have failed."
In a statement on Friday in anticipation of First Republic's collapse, Lisa Gilbert, executive vice president of Public Citizen, said, "Once again, we're reaping the bitter harvest of financial deregulation."
Gilbert's colleague, financial policy expert Bart Naylor, said, "Bankers at First Republic make reckless decisions, encouraged by bad pay-related incentives."
"Lawmakers understood this was a problem throughout the industry following the 2008 financial crash and required a rule to stop it," Naylor added. "But dangerously, that rule has not yet been implemented. With the failure of First Republic following the failure of Silicon Valley Bank, regulators must reform banker pay immediately."
This country and this world are at a monumental crossroads. US voters have an opportunity to beat back the forces of fascism and confront the billionaires who are rigging the economy, our media system, and our democracy, making it increasingly impossible for ordinary people to get by. We’re not just talking about the election. We’re talking about what must be done once these fascist elements are vanquished from power. We need a bolder set of solutions than what either major party has so far been willing to offer and a working-class movement ready to fight like hell for it. Trump didn't emerge from nowhere. The conditions that fueled MAGA authoritarianism were created by decades of radical neoliberal economic policies and a corrupt political system dominated by corporate interests. They slashed taxes on the super-rich, promising that the benefits would trickle down. They said giveaways to the corporate titans would make life more affordable for the rest of us. It was all bullshit. And when a bitter, betrayed populace searches for someone to blame, right-wing demagogues have little trouble finding scapegoats. People know when they're being lied to, but you won't hear any of this from the corporate media. Only independent journalism—powered and funded by people who believe in building a better world—can deliver truly trustworthy daily news. If you share our vision, please contribute whatever you can to sustain our work. |
Sen. Elizabeth Warren said Monday that the latest government bailout of a failing Wall Street institution shows how much the financial system remains rigged in favor of powerful banks and that it is beyond time for Congress to step up with increased oversight and reforms.
Federal regulators Monday announced they had seized the entirety of First Republic Bank and sold it to JPMorgan Chase for an undisclosed price—the latest fallout from a deregulated banking system in which the U.S. government has stepped in to backstop Wall Street.
"The failure of First Republic Bank shows how deregulation has made the too big to fail problem even worse," said Warren in response to the news. "A poorly supervised bank was snapped up by an even bigger bank—ultimately taxpayers will be on the hook. Congress needs to make major reforms to fix a broken banking system."
"Once again, we're reaping the bitter harvest of financial deregulation." —Lisa Gilbert, Public Citizen
Last week, as Common Dreams reported, the Federal Reserve issued the results of an internal investigation which showed the collapse of Silicon Valley Bank earlier this year was at least partly due to the 2018 deregulation of mid-sized banks that was approved by Congress and signed into law by former President Donald Trump.
In an early morning statement, the Federal Deposit Insurance Corporation (FDIC) said First Republic—which has been teetering on collapse for weeks—was first closed before being sold to banking giant JPMorgan following a bidding process for the smaller bank's assets.
"As part of the transaction," said the FDIC, "First Republic Bank's 84 offices in eight states will reopen as branches of JPMorgan Chase Bank, National Association, today during normal business hours. All depositors of First Republic Bank will become depositors of JPMorgan Chase Bank, National Association, and will have full access to all of their deposits."
According to the Washington Post:
The acquisition makes JPMorgan, already the nation’s largest bank, even bigger and could draw political scrutiny from progressive Democrats in Washington.
First Republic failed despite having received a $30 billion lifeline from 11 of the country's largest banks in March. JPMorgan said the $30 billion would be repaid after the deal closes. Overall, First Republic will go down in history as the second largest U.S. bank by assets to collapse after Washington Mutual, which failed during the financial crisis of 2008.
FDIC said the cost of the deal to the Deposit Insurance Fund which it manages will be approximately $13 billion.
"In other words, good banks and their customers pay to insure bad banks," said Richard Painter, law professor and former White House ethics chief. "How much did First Republic's execs who created this mess have to pay? If we made them pay, First Republic might not have failed."
In a statement on Friday in anticipation of First Republic's collapse, Lisa Gilbert, executive vice president of Public Citizen, said, "Once again, we're reaping the bitter harvest of financial deregulation."
Gilbert's colleague, financial policy expert Bart Naylor, said, "Bankers at First Republic make reckless decisions, encouraged by bad pay-related incentives."
"Lawmakers understood this was a problem throughout the industry following the 2008 financial crash and required a rule to stop it," Naylor added. "But dangerously, that rule has not yet been implemented. With the failure of First Republic following the failure of Silicon Valley Bank, regulators must reform banker pay immediately."
Sen. Elizabeth Warren said Monday that the latest government bailout of a failing Wall Street institution shows how much the financial system remains rigged in favor of powerful banks and that it is beyond time for Congress to step up with increased oversight and reforms.
Federal regulators Monday announced they had seized the entirety of First Republic Bank and sold it to JPMorgan Chase for an undisclosed price—the latest fallout from a deregulated banking system in which the U.S. government has stepped in to backstop Wall Street.
"The failure of First Republic Bank shows how deregulation has made the too big to fail problem even worse," said Warren in response to the news. "A poorly supervised bank was snapped up by an even bigger bank—ultimately taxpayers will be on the hook. Congress needs to make major reforms to fix a broken banking system."
"Once again, we're reaping the bitter harvest of financial deregulation." —Lisa Gilbert, Public Citizen
Last week, as Common Dreams reported, the Federal Reserve issued the results of an internal investigation which showed the collapse of Silicon Valley Bank earlier this year was at least partly due to the 2018 deregulation of mid-sized banks that was approved by Congress and signed into law by former President Donald Trump.
In an early morning statement, the Federal Deposit Insurance Corporation (FDIC) said First Republic—which has been teetering on collapse for weeks—was first closed before being sold to banking giant JPMorgan following a bidding process for the smaller bank's assets.
"As part of the transaction," said the FDIC, "First Republic Bank's 84 offices in eight states will reopen as branches of JPMorgan Chase Bank, National Association, today during normal business hours. All depositors of First Republic Bank will become depositors of JPMorgan Chase Bank, National Association, and will have full access to all of their deposits."
According to the Washington Post:
The acquisition makes JPMorgan, already the nation’s largest bank, even bigger and could draw political scrutiny from progressive Democrats in Washington.
First Republic failed despite having received a $30 billion lifeline from 11 of the country's largest banks in March. JPMorgan said the $30 billion would be repaid after the deal closes. Overall, First Republic will go down in history as the second largest U.S. bank by assets to collapse after Washington Mutual, which failed during the financial crisis of 2008.
FDIC said the cost of the deal to the Deposit Insurance Fund which it manages will be approximately $13 billion.
"In other words, good banks and their customers pay to insure bad banks," said Richard Painter, law professor and former White House ethics chief. "How much did First Republic's execs who created this mess have to pay? If we made them pay, First Republic might not have failed."
In a statement on Friday in anticipation of First Republic's collapse, Lisa Gilbert, executive vice president of Public Citizen, said, "Once again, we're reaping the bitter harvest of financial deregulation."
Gilbert's colleague, financial policy expert Bart Naylor, said, "Bankers at First Republic make reckless decisions, encouraged by bad pay-related incentives."
"Lawmakers understood this was a problem throughout the industry following the 2008 financial crash and required a rule to stop it," Naylor added. "But dangerously, that rule has not yet been implemented. With the failure of First Republic following the failure of Silicon Valley Bank, regulators must reform banker pay immediately."