SUBSCRIBE TO OUR FREE NEWSLETTER
Daily news & progressive opinion—funded by the people, not the corporations—delivered straight to your inbox.
5
#000000
#FFFFFF
To donate by check, phone, or other method, see our More Ways to Give page.
Daily news & progressive opinion—funded by the people, not the corporations—delivered straight to your inbox.
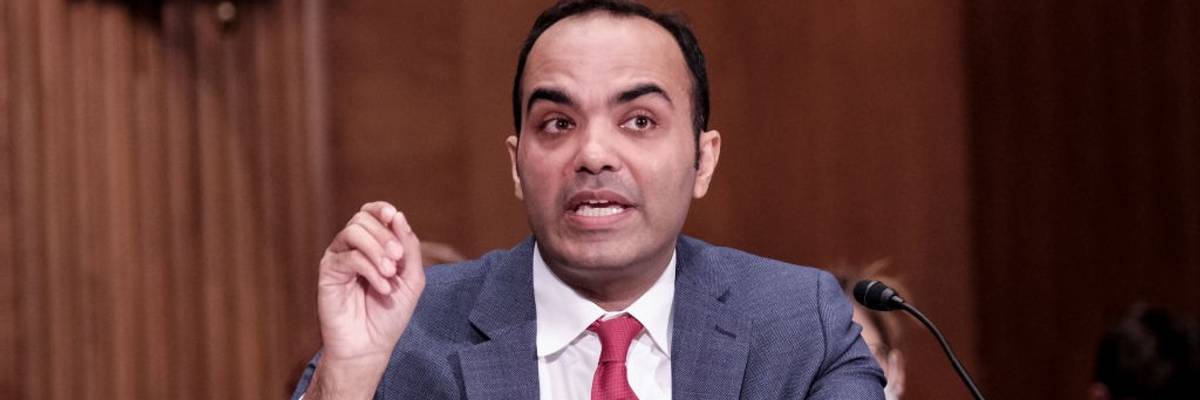
U.S. Consumer Financial Protection Bureau Director Rohit Chopra speaks during a June 13, 2023 Senate hearing in Washington, D.C.
"The CFPB is proposing clear, enforceable rules that will reduce overdraft fees and save Americans billions, closing another lucrative regulatory loophole banks use to prey on consumers," said one advocate.
In a move cheered by progressive advocates, the U.S. Consumer Financial Protection Bureau on Wednesday proposed a new rule limiting how the nation's biggest banks can charge overdraft fees.
The CFPB said its proposal "would close an outdated loophole that exempts overdraft lending services from long-standing provisions of the Truth in Lending Act and other consumer financial protection laws."
"For decades, very large financial institutions have been able to issue highly profitable overdraft loans, which have garnered them billions of dollars in revenue annually," the agency explained. "Under the proposal, large banks would be free to extend overdraft loans if they complied with long-standing lending laws, including disclosing any applicable interest rate."
The Federal Reserve Board initially created an exemption from the Truth in Lending Act—which required lenders to clearly disclose the cost of credit to borrowers—half a century ago to allow banks to recover costs incurred when they honored checks from customers who inadvertently overdrew their accounts. This was deemed necessary at a time when most workers were paid by mailed checks with uncertain clearance periods.
However, as the CFPB noted:
In the 1990s and early 2000s, with the rise of debit cards, institutions began raising fees and using the exemption to churn high volumes of overdraft loans on debit card transactions. Annual overdraft fee revenue in 2019 was an estimated $12.6 billion. And, in 2022, Wells Fargo and JPMorgan Chase led the way—accounting for one-third of overdraft revenue reported by banks over $1 billion.
According to a January report from the watchdog Accountable.US, the 10 largest U.S. banks raked in more than $2.3 billion in overdraft fees during just the first nine months of 2023.
"Today, we are proposing rules to close a long-standing loophole that allowed many large banks to transform overdraft into a massive junk fee harvesting machine," CFPB Director Rohit Chopra said in a statement.
President Joe Biden touted the proposal in a statement noting that "for too long, some banks have charged exorbitant overdraft fees—sometimes $30 or more—that often hit the most vulnerable Americans the hardest, all while banks pad their bottom lines."
"Banks call it a service—I call it exploitation," the president added. "Today's proposal would cut the average overdraft fee by more than half, saving the typical American family that pays these fees $150 a year."
Groups including Accountable.US, the American Economic Liberties Project, Demand Progress, and the Revolving Door Project hailed the proposed rule.
"American consumers strongly support the Biden administration's crackdown on overdraft fees that will lower their costs by billions of dollars every year," said Liz Zelnick, director of the Economic Security & Corporate Power Program at Accountable.US. "While the administration is once again siding with consumers over greedy corporations, Republicans in Congress are lining up behind bank and credit union CEOs and lobbyists who gouge consumers to pad their massive profits."
"The last thing many families living paycheck to paycheck need is a surprise $35 overdraft charge on a gallon of milk or loaf of bread, yet many Republicans in Congress say Americans should be grateful for the hard lesson in corporate greed," added Zelnick.
Shahid Naeem, senior policy analyst at the American Economic Liberties Project, asserted that "while some banks have already responded to CFPB pressure and reduced or eliminated these fees, Americans shouldn't have to rely on the discretion of individual banks."
"The CFPB is proposing clear, enforceable rules that will reduce overdraft fees and save Americans billions, closing another lucrative regulatory loophole banks use to prey on consumers," he added.
Emily Peterson-Cassin, Demand Progress Education Fund director of Corporate Power, argued that "we must put an end to big banks stealing money directly from the pockets of the American people through their junk fees on bank account overdrafts."
"These fees add up to billions of dollars for banks—and most of that money comes from households struggling to make ends meet, where a few dollars could mean having to choose between paying rent on time, affording a critical prescription, or putting enough food on the table," she continued.
"We applaud the CFPB for taking a step toward restoring a more appropriate balance between customer and bank, where customers can trust their banks not to exploit them," Peterson-Cassin added.
Revolving Door Project executive director Jeff Hauser said that "the CFPB is doing what it was designed to do, and now the biggest threat is that America's most exploitative companies want payoff for decades of corrupt investment in our nation's courts by having the Supreme Court gut the bureau itself."
Along with noting the court's forthcoming CFPB decision, Hauser argued, "Civil society must plan to bring enormous pushback on Supreme Court justices and other judges corrupted by the likes of Charles Koch and Harlan Crow if any of the CFPB's commonsense consumer protections are overturned by our sadly activist judiciary."
This country and this world are at a monumental crossroads. US voters have an opportunity to beat back the forces of fascism and confront the billionaires who are rigging the economy, our media system, and our democracy, making it increasingly impossible for ordinary people to get by. We’re not just talking about the election. We’re talking about what must be done once these fascist elements are vanquished from power. We need a bolder set of solutions than what either major party has so far been willing to offer and a working-class movement ready to fight like hell for it. Trump didn't emerge from nowhere. The conditions that fueled MAGA authoritarianism were created by decades of radical neoliberal economic policies and a corrupt political system dominated by corporate interests. They slashed taxes on the super-rich, promising that the benefits would trickle down. They said giveaways to the corporate titans would make life more affordable for the rest of us. It was all bullshit. And when a bitter, betrayed populace searches for someone to blame, right-wing demagogues have little trouble finding scapegoats. People know when they're being lied to, but you won't hear any of this from the corporate media. Only independent journalism—powered and funded by people who believe in building a better world—can deliver truly trustworthy daily news. If you share our vision, please contribute whatever you can to sustain our work. |
In a move cheered by progressive advocates, the U.S. Consumer Financial Protection Bureau on Wednesday proposed a new rule limiting how the nation's biggest banks can charge overdraft fees.
The CFPB said its proposal "would close an outdated loophole that exempts overdraft lending services from long-standing provisions of the Truth in Lending Act and other consumer financial protection laws."
"For decades, very large financial institutions have been able to issue highly profitable overdraft loans, which have garnered them billions of dollars in revenue annually," the agency explained. "Under the proposal, large banks would be free to extend overdraft loans if they complied with long-standing lending laws, including disclosing any applicable interest rate."
The Federal Reserve Board initially created an exemption from the Truth in Lending Act—which required lenders to clearly disclose the cost of credit to borrowers—half a century ago to allow banks to recover costs incurred when they honored checks from customers who inadvertently overdrew their accounts. This was deemed necessary at a time when most workers were paid by mailed checks with uncertain clearance periods.
However, as the CFPB noted:
In the 1990s and early 2000s, with the rise of debit cards, institutions began raising fees and using the exemption to churn high volumes of overdraft loans on debit card transactions. Annual overdraft fee revenue in 2019 was an estimated $12.6 billion. And, in 2022, Wells Fargo and JPMorgan Chase led the way—accounting for one-third of overdraft revenue reported by banks over $1 billion.
According to a January report from the watchdog Accountable.US, the 10 largest U.S. banks raked in more than $2.3 billion in overdraft fees during just the first nine months of 2023.
"Today, we are proposing rules to close a long-standing loophole that allowed many large banks to transform overdraft into a massive junk fee harvesting machine," CFPB Director Rohit Chopra said in a statement.
President Joe Biden touted the proposal in a statement noting that "for too long, some banks have charged exorbitant overdraft fees—sometimes $30 or more—that often hit the most vulnerable Americans the hardest, all while banks pad their bottom lines."
"Banks call it a service—I call it exploitation," the president added. "Today's proposal would cut the average overdraft fee by more than half, saving the typical American family that pays these fees $150 a year."
Groups including Accountable.US, the American Economic Liberties Project, Demand Progress, and the Revolving Door Project hailed the proposed rule.
"American consumers strongly support the Biden administration's crackdown on overdraft fees that will lower their costs by billions of dollars every year," said Liz Zelnick, director of the Economic Security & Corporate Power Program at Accountable.US. "While the administration is once again siding with consumers over greedy corporations, Republicans in Congress are lining up behind bank and credit union CEOs and lobbyists who gouge consumers to pad their massive profits."
"The last thing many families living paycheck to paycheck need is a surprise $35 overdraft charge on a gallon of milk or loaf of bread, yet many Republicans in Congress say Americans should be grateful for the hard lesson in corporate greed," added Zelnick.
Shahid Naeem, senior policy analyst at the American Economic Liberties Project, asserted that "while some banks have already responded to CFPB pressure and reduced or eliminated these fees, Americans shouldn't have to rely on the discretion of individual banks."
"The CFPB is proposing clear, enforceable rules that will reduce overdraft fees and save Americans billions, closing another lucrative regulatory loophole banks use to prey on consumers," he added.
Emily Peterson-Cassin, Demand Progress Education Fund director of Corporate Power, argued that "we must put an end to big banks stealing money directly from the pockets of the American people through their junk fees on bank account overdrafts."
"These fees add up to billions of dollars for banks—and most of that money comes from households struggling to make ends meet, where a few dollars could mean having to choose between paying rent on time, affording a critical prescription, or putting enough food on the table," she continued.
"We applaud the CFPB for taking a step toward restoring a more appropriate balance between customer and bank, where customers can trust their banks not to exploit them," Peterson-Cassin added.
Revolving Door Project executive director Jeff Hauser said that "the CFPB is doing what it was designed to do, and now the biggest threat is that America's most exploitative companies want payoff for decades of corrupt investment in our nation's courts by having the Supreme Court gut the bureau itself."
Along with noting the court's forthcoming CFPB decision, Hauser argued, "Civil society must plan to bring enormous pushback on Supreme Court justices and other judges corrupted by the likes of Charles Koch and Harlan Crow if any of the CFPB's commonsense consumer protections are overturned by our sadly activist judiciary."
In a move cheered by progressive advocates, the U.S. Consumer Financial Protection Bureau on Wednesday proposed a new rule limiting how the nation's biggest banks can charge overdraft fees.
The CFPB said its proposal "would close an outdated loophole that exempts overdraft lending services from long-standing provisions of the Truth in Lending Act and other consumer financial protection laws."
"For decades, very large financial institutions have been able to issue highly profitable overdraft loans, which have garnered them billions of dollars in revenue annually," the agency explained. "Under the proposal, large banks would be free to extend overdraft loans if they complied with long-standing lending laws, including disclosing any applicable interest rate."
The Federal Reserve Board initially created an exemption from the Truth in Lending Act—which required lenders to clearly disclose the cost of credit to borrowers—half a century ago to allow banks to recover costs incurred when they honored checks from customers who inadvertently overdrew their accounts. This was deemed necessary at a time when most workers were paid by mailed checks with uncertain clearance periods.
However, as the CFPB noted:
In the 1990s and early 2000s, with the rise of debit cards, institutions began raising fees and using the exemption to churn high volumes of overdraft loans on debit card transactions. Annual overdraft fee revenue in 2019 was an estimated $12.6 billion. And, in 2022, Wells Fargo and JPMorgan Chase led the way—accounting for one-third of overdraft revenue reported by banks over $1 billion.
According to a January report from the watchdog Accountable.US, the 10 largest U.S. banks raked in more than $2.3 billion in overdraft fees during just the first nine months of 2023.
"Today, we are proposing rules to close a long-standing loophole that allowed many large banks to transform overdraft into a massive junk fee harvesting machine," CFPB Director Rohit Chopra said in a statement.
President Joe Biden touted the proposal in a statement noting that "for too long, some banks have charged exorbitant overdraft fees—sometimes $30 or more—that often hit the most vulnerable Americans the hardest, all while banks pad their bottom lines."
"Banks call it a service—I call it exploitation," the president added. "Today's proposal would cut the average overdraft fee by more than half, saving the typical American family that pays these fees $150 a year."
Groups including Accountable.US, the American Economic Liberties Project, Demand Progress, and the Revolving Door Project hailed the proposed rule.
"American consumers strongly support the Biden administration's crackdown on overdraft fees that will lower their costs by billions of dollars every year," said Liz Zelnick, director of the Economic Security & Corporate Power Program at Accountable.US. "While the administration is once again siding with consumers over greedy corporations, Republicans in Congress are lining up behind bank and credit union CEOs and lobbyists who gouge consumers to pad their massive profits."
"The last thing many families living paycheck to paycheck need is a surprise $35 overdraft charge on a gallon of milk or loaf of bread, yet many Republicans in Congress say Americans should be grateful for the hard lesson in corporate greed," added Zelnick.
Shahid Naeem, senior policy analyst at the American Economic Liberties Project, asserted that "while some banks have already responded to CFPB pressure and reduced or eliminated these fees, Americans shouldn't have to rely on the discretion of individual banks."
"The CFPB is proposing clear, enforceable rules that will reduce overdraft fees and save Americans billions, closing another lucrative regulatory loophole banks use to prey on consumers," he added.
Emily Peterson-Cassin, Demand Progress Education Fund director of Corporate Power, argued that "we must put an end to big banks stealing money directly from the pockets of the American people through their junk fees on bank account overdrafts."
"These fees add up to billions of dollars for banks—and most of that money comes from households struggling to make ends meet, where a few dollars could mean having to choose between paying rent on time, affording a critical prescription, or putting enough food on the table," she continued.
"We applaud the CFPB for taking a step toward restoring a more appropriate balance between customer and bank, where customers can trust their banks not to exploit them," Peterson-Cassin added.
Revolving Door Project executive director Jeff Hauser said that "the CFPB is doing what it was designed to do, and now the biggest threat is that America's most exploitative companies want payoff for decades of corrupt investment in our nation's courts by having the Supreme Court gut the bureau itself."
Along with noting the court's forthcoming CFPB decision, Hauser argued, "Civil society must plan to bring enormous pushback on Supreme Court justices and other judges corrupted by the likes of Charles Koch and Harlan Crow if any of the CFPB's commonsense consumer protections are overturned by our sadly activist judiciary."