SUBSCRIBE TO OUR FREE NEWSLETTER
Daily news & progressive opinion—funded by the people, not the corporations—delivered straight to your inbox.
5
#000000
#FFFFFF
To donate by check, phone, or other method, see our More Ways to Give page.
Daily news & progressive opinion—funded by the people, not the corporations—delivered straight to your inbox.
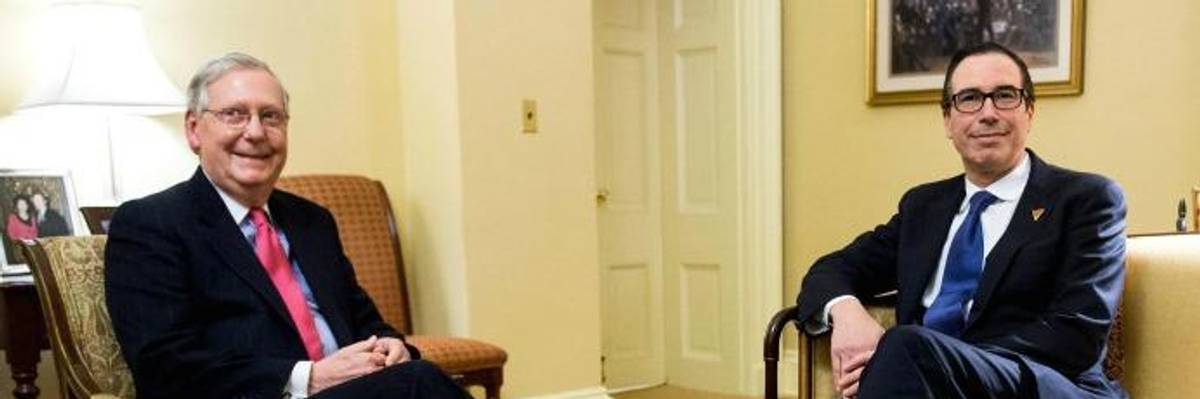
Senate Majority Leader Mitch McConnell (R-Ky.) meets with Treasury Secretary nominee Steven Mnuchin at the U.S. Capitol on December 6, 2016 in Washington, D.C. (Photo: Win McNamee/Getty Images)
Hours before the Senate is set to vote Tuesday on whether to repeal the Consumer Financial Protection Bureau's (CFPB) broadly popular arbitration rule--which bars companies from using "rip off clauses" to prevent consumers from filing or joining class action lawsuits--Public Citizen and other advocacy groups warned that any move to scrap the CFPB's measure would permit "predatory banks, payday lenders, credit card companies, and other financial institutions to cheat and defraud their customers."
"Big banks, the financial industry and their allies in Congress are trying to overturn the arbitration rule because it will deprive them of a means to rip off consumers with impunity."
--Amanda Werner, Public Citizen"The vote on this rule is a litmus test of whose side you're on: Main Street consumers or big banks," Amanda Werner, arbitration campaign manager for Public Citizen and Americans for Financial Reform, said in a statement on Tuesday. "Big banks, the financial industry and their allies in Congress are trying to overturn the arbitration rule because it will deprive them of a means to rip off consumers with impunity."
While it is not clear which way the Senate will vote--Majority Leader Mitch McConnell (R-Ky.) needs 50 senators to support the move, and five Republicans have yet to indicate that they are a "yes"--the Trump White House has not shied away from indicating that it is firmly on the side of Wall Street.
The Treasury Department, headed by ex-Goldman Sachs banker Steve Mnuchin, took what has been described as an "unusual" step on Monday by publicly releasing a report (pdf) slamming the CFPB's rule, arguing that it is a "giveaway to class-action attorneys."
But in a piece for The Intercept on Tuesday, David Dayen notes that Treasury's report relies "heavily on a discredited industry theory."
"Claims that CFPB used misleading data and failed to recognize that consumers fare better in arbitration (which isn't true) come directly from a Koch-funded Mercatus Center study, which the Treasury report cites," Dayen notes.
The Treasury Department also attempts to argue that the CFPB's rule opens the door to "frivolous" lawsuits and so-called "blackmail settlements." But Dayen notes that the "blackmail theory" is a meritless "rhetorical weapon" used by corporations that want "blanket protection from lawsuits of any kind."
"They would rather steer consumer disputes away from the courts entirely and put them into an arbitration setting where the deck is stacked against the ordinary person from gaining any restitution," Dayen concludes.
Judging by opinion polls, the public appears to agree with Dayen and the pro-consumer Fair Arbitration Now coalition, which announced on Tuesday that nearly 100,000 Americans have signed a petition supporting the CFPB's rule.
Survey after survey conducted by both progressive and conservative organizations has found that Americans overwhelmingly support for the CFPB's ban on forced arbitration, which Werner of Public Citizen denounced as a "rigged game, one that the bank nearly always wins."
"It's no secret why lawmakers want to hand financial companies a Get Out of Jail Free card. The financial industry has given more than $100 million in campaign contributions to lawmakers opposed to the rule," Werner observed. "These contributions help explain why lawmakers are willing to aid and abet big banks in ripping off their own constituents despite overwhelming bipartisan support for the rule."
Ahead of the Senate's expected vote on Tuesday, Sen. Elizabeth Warren (D-Mass.)--who spearheaded the creation of the CFPB--posted a video outlining the what is at stake for consumers.
This country and this world are at a monumental crossroads. US voters have an opportunity to beat back the forces of fascism and confront the billionaires who are rigging the economy, our media system, and our democracy, making it increasingly impossible for ordinary people to get by. We’re not just talking about the election. We’re talking about what must be done once these fascist elements are vanquished from power. We need a bolder set of solutions than what either major party has so far been willing to offer and a working-class movement ready to fight like hell for it. Trump didn't emerge from nowhere. The conditions that fueled MAGA authoritarianism were created by decades of radical neoliberal economic policies and a corrupt political system dominated by corporate interests. They slashed taxes on the super-rich, promising that the benefits would trickle down. They said giveaways to the corporate titans would make life more affordable for the rest of us. It was all bullshit. And when a bitter, betrayed populace searches for someone to blame, right-wing demagogues have little trouble finding scapegoats. People know when they're being lied to, but you won't hear any of this from the corporate media. Only independent journalism—powered and funded by people who believe in building a better world—can deliver truly trustworthy daily news. If you share our vision, please contribute whatever you can to sustain our work. |
Hours before the Senate is set to vote Tuesday on whether to repeal the Consumer Financial Protection Bureau's (CFPB) broadly popular arbitration rule--which bars companies from using "rip off clauses" to prevent consumers from filing or joining class action lawsuits--Public Citizen and other advocacy groups warned that any move to scrap the CFPB's measure would permit "predatory banks, payday lenders, credit card companies, and other financial institutions to cheat and defraud their customers."
"Big banks, the financial industry and their allies in Congress are trying to overturn the arbitration rule because it will deprive them of a means to rip off consumers with impunity."
--Amanda Werner, Public Citizen"The vote on this rule is a litmus test of whose side you're on: Main Street consumers or big banks," Amanda Werner, arbitration campaign manager for Public Citizen and Americans for Financial Reform, said in a statement on Tuesday. "Big banks, the financial industry and their allies in Congress are trying to overturn the arbitration rule because it will deprive them of a means to rip off consumers with impunity."
While it is not clear which way the Senate will vote--Majority Leader Mitch McConnell (R-Ky.) needs 50 senators to support the move, and five Republicans have yet to indicate that they are a "yes"--the Trump White House has not shied away from indicating that it is firmly on the side of Wall Street.
The Treasury Department, headed by ex-Goldman Sachs banker Steve Mnuchin, took what has been described as an "unusual" step on Monday by publicly releasing a report (pdf) slamming the CFPB's rule, arguing that it is a "giveaway to class-action attorneys."
But in a piece for The Intercept on Tuesday, David Dayen notes that Treasury's report relies "heavily on a discredited industry theory."
"Claims that CFPB used misleading data and failed to recognize that consumers fare better in arbitration (which isn't true) come directly from a Koch-funded Mercatus Center study, which the Treasury report cites," Dayen notes.
The Treasury Department also attempts to argue that the CFPB's rule opens the door to "frivolous" lawsuits and so-called "blackmail settlements." But Dayen notes that the "blackmail theory" is a meritless "rhetorical weapon" used by corporations that want "blanket protection from lawsuits of any kind."
"They would rather steer consumer disputes away from the courts entirely and put them into an arbitration setting where the deck is stacked against the ordinary person from gaining any restitution," Dayen concludes.
Judging by opinion polls, the public appears to agree with Dayen and the pro-consumer Fair Arbitration Now coalition, which announced on Tuesday that nearly 100,000 Americans have signed a petition supporting the CFPB's rule.
Survey after survey conducted by both progressive and conservative organizations has found that Americans overwhelmingly support for the CFPB's ban on forced arbitration, which Werner of Public Citizen denounced as a "rigged game, one that the bank nearly always wins."
"It's no secret why lawmakers want to hand financial companies a Get Out of Jail Free card. The financial industry has given more than $100 million in campaign contributions to lawmakers opposed to the rule," Werner observed. "These contributions help explain why lawmakers are willing to aid and abet big banks in ripping off their own constituents despite overwhelming bipartisan support for the rule."
Ahead of the Senate's expected vote on Tuesday, Sen. Elizabeth Warren (D-Mass.)--who spearheaded the creation of the CFPB--posted a video outlining the what is at stake for consumers.
Hours before the Senate is set to vote Tuesday on whether to repeal the Consumer Financial Protection Bureau's (CFPB) broadly popular arbitration rule--which bars companies from using "rip off clauses" to prevent consumers from filing or joining class action lawsuits--Public Citizen and other advocacy groups warned that any move to scrap the CFPB's measure would permit "predatory banks, payday lenders, credit card companies, and other financial institutions to cheat and defraud their customers."
"Big banks, the financial industry and their allies in Congress are trying to overturn the arbitration rule because it will deprive them of a means to rip off consumers with impunity."
--Amanda Werner, Public Citizen"The vote on this rule is a litmus test of whose side you're on: Main Street consumers or big banks," Amanda Werner, arbitration campaign manager for Public Citizen and Americans for Financial Reform, said in a statement on Tuesday. "Big banks, the financial industry and their allies in Congress are trying to overturn the arbitration rule because it will deprive them of a means to rip off consumers with impunity."
While it is not clear which way the Senate will vote--Majority Leader Mitch McConnell (R-Ky.) needs 50 senators to support the move, and five Republicans have yet to indicate that they are a "yes"--the Trump White House has not shied away from indicating that it is firmly on the side of Wall Street.
The Treasury Department, headed by ex-Goldman Sachs banker Steve Mnuchin, took what has been described as an "unusual" step on Monday by publicly releasing a report (pdf) slamming the CFPB's rule, arguing that it is a "giveaway to class-action attorneys."
But in a piece for The Intercept on Tuesday, David Dayen notes that Treasury's report relies "heavily on a discredited industry theory."
"Claims that CFPB used misleading data and failed to recognize that consumers fare better in arbitration (which isn't true) come directly from a Koch-funded Mercatus Center study, which the Treasury report cites," Dayen notes.
The Treasury Department also attempts to argue that the CFPB's rule opens the door to "frivolous" lawsuits and so-called "blackmail settlements." But Dayen notes that the "blackmail theory" is a meritless "rhetorical weapon" used by corporations that want "blanket protection from lawsuits of any kind."
"They would rather steer consumer disputes away from the courts entirely and put them into an arbitration setting where the deck is stacked against the ordinary person from gaining any restitution," Dayen concludes.
Judging by opinion polls, the public appears to agree with Dayen and the pro-consumer Fair Arbitration Now coalition, which announced on Tuesday that nearly 100,000 Americans have signed a petition supporting the CFPB's rule.
Survey after survey conducted by both progressive and conservative organizations has found that Americans overwhelmingly support for the CFPB's ban on forced arbitration, which Werner of Public Citizen denounced as a "rigged game, one that the bank nearly always wins."
"It's no secret why lawmakers want to hand financial companies a Get Out of Jail Free card. The financial industry has given more than $100 million in campaign contributions to lawmakers opposed to the rule," Werner observed. "These contributions help explain why lawmakers are willing to aid and abet big banks in ripping off their own constituents despite overwhelming bipartisan support for the rule."
Ahead of the Senate's expected vote on Tuesday, Sen. Elizabeth Warren (D-Mass.)--who spearheaded the creation of the CFPB--posted a video outlining the what is at stake for consumers.