SUBSCRIBE TO OUR FREE NEWSLETTER
Daily news & progressive opinion—funded by the people, not the corporations—delivered straight to your inbox.
5
#000000
#FFFFFF
To donate by check, phone, or other method, see our More Ways to Give page.
Daily news & progressive opinion—funded by the people, not the corporations—delivered straight to your inbox.
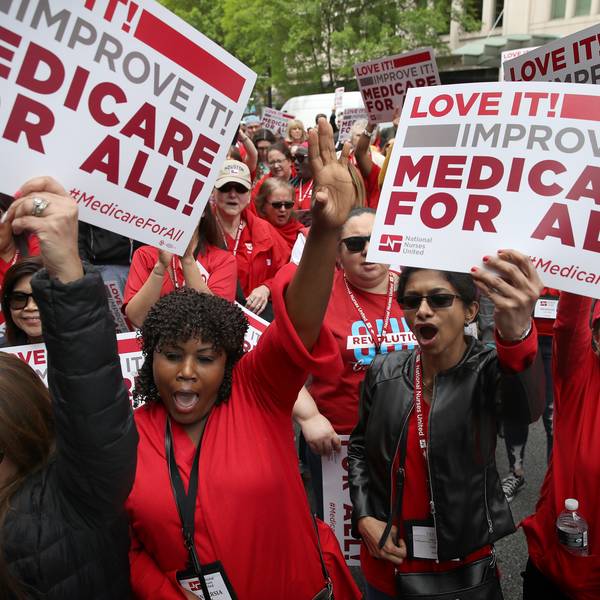
The best argument for a single-payer health plan is the recent decision by giant health insurer Aetna to bail out next year from 11 of the 15 states where it sells Obamacare plans.Aetna's decision follows similar moves by UnitedHealth Group, the nation's largest health insurer, and by Humana, another one of the giants.
All claim they're not making enough money because too many people with serious health problems are using the Obamacare exchanges, and not enough healthy people are signing up.
The best argument for a single-payer health plan is the recent decision by giant health insurer Aetna to bail out next year from 11 of the 15 states where it sells Obamacare plans.Aetna's decision follows similar moves by UnitedHealth Group, the nation's largest health insurer, and by Humana, another one of the giants.
All claim they're not making enough money because too many people with serious health problems are using the Obamacare exchanges, and not enough healthy people are signing up.
The problem isn't Obamacare per se. It lies in the structure of private markets for health insurance - which creates powerful incentives to avoid sick people and attract healthy ones. Obamacare is just making this structural problem more obvious.
In a nutshell, the more sick people and the fewer healthy people a private for-profit insurer attracts, the less competitive that insurer becomes relative to other insurers that don't attract as high a percentage of the sick but a higher percentage of the healthy.
Eventually, insurers that take in too many sick and too few healthy people are driven out of business.
If insurers had no idea who'd be sick and who'd be healthy when they sign up for insurance (and keep them insured at the same price even after they become sick), this wouldn't be a problem. But they do know - and they're developing more and more sophisticated ways of finding out.
Health insurers spend lots of time, effort, and money trying to attract people who have high odds of staying healthy (the young and the fit) while doing whatever they can to fend off those who have high odds of getting sick (the older, infirm, and the unfit).
As a result we end up with the most bizarre health-insurance system imaginable: One ever better designed to avoid sick people.
If this weren't enough to convince rational people to do what most other advanced nations have done - create a single-payer system that insures everyone, funded by taxpayers - consider that America's giant health insurers are now busily consolidating into ever-larger behemoths.
UnitedHealth is already humongous.
Aetna, meanwhile, is trying to buy Humana in a deal that will create the second-largest health insurer in the nation, with 33 million members. The Justice Department has so far blocked the deal.
Insurers say they're consolidating in order to reap economies of scale. But there's little evidence that large size generates cost savings.
In reality, they're becoming huge to get more bargaining leverage over everyone they do business with - hospitals, doctors, employers, the government, and consumers. That way they make even bigger profits.
But these bigger profits come at the expense of hospitals, doctors, employers, the government, and, ultimately, taxpayers and consumers.
There's abundant evidence, for example, that when health insurers merge, premiums rise. researchers found, for example, that after Aetna merged with Prudential HealthCare in 1999, premiums rose 7 percent higher than had the merger not occurred.
What to do? In the short term, Obamacare can be patched up by enlarging government subsidies for purchasing insurance, and ensuring that healthy Americans buy insurance, as the law requires.
But these are band aids. The real choice in the future is either a hugely expensive for-profit oligopoly with the market power to charge high prices even to healthy people and stop insuring sick people.
Or else a government-run single payer system - such as is in place in almost every other advanced economy - dedicated to lower premiums and better care for everyone.
We're going to have to choose eventually.
This country and this world are at a monumental crossroads. US voters have an opportunity to beat back the forces of fascism and confront the billionaires who are rigging the economy, our media system, and our democracy, making it increasingly impossible for ordinary people to get by. We’re not just talking about the election. We’re talking about what must be done once these fascist elements are vanquished from power. We need a bolder set of solutions than what either major party has so far been willing to offer and a working-class movement ready to fight like hell for it. Trump didn't emerge from nowhere. The conditions that fueled MAGA authoritarianism were created by decades of radical neoliberal economic policies and a corrupt political system dominated by corporate interests. They slashed taxes on the super-rich, promising that the benefits would trickle down. They said giveaways to the corporate titans would make life more affordable for the rest of us. It was all bullshit. And when a bitter, betrayed populace searches for someone to blame, right-wing demagogues have little trouble finding scapegoats. People know when they're being lied to, but you won't hear any of this from the corporate media. Only independent journalism—powered and funded by people who believe in building a better world—can deliver truly trustworthy daily news. If you share our vision, please contribute whatever you can to sustain our work. |
The best argument for a single-payer health plan is the recent decision by giant health insurer Aetna to bail out next year from 11 of the 15 states where it sells Obamacare plans.Aetna's decision follows similar moves by UnitedHealth Group, the nation's largest health insurer, and by Humana, another one of the giants.
All claim they're not making enough money because too many people with serious health problems are using the Obamacare exchanges, and not enough healthy people are signing up.
The problem isn't Obamacare per se. It lies in the structure of private markets for health insurance - which creates powerful incentives to avoid sick people and attract healthy ones. Obamacare is just making this structural problem more obvious.
In a nutshell, the more sick people and the fewer healthy people a private for-profit insurer attracts, the less competitive that insurer becomes relative to other insurers that don't attract as high a percentage of the sick but a higher percentage of the healthy.
Eventually, insurers that take in too many sick and too few healthy people are driven out of business.
If insurers had no idea who'd be sick and who'd be healthy when they sign up for insurance (and keep them insured at the same price even after they become sick), this wouldn't be a problem. But they do know - and they're developing more and more sophisticated ways of finding out.
Health insurers spend lots of time, effort, and money trying to attract people who have high odds of staying healthy (the young and the fit) while doing whatever they can to fend off those who have high odds of getting sick (the older, infirm, and the unfit).
As a result we end up with the most bizarre health-insurance system imaginable: One ever better designed to avoid sick people.
If this weren't enough to convince rational people to do what most other advanced nations have done - create a single-payer system that insures everyone, funded by taxpayers - consider that America's giant health insurers are now busily consolidating into ever-larger behemoths.
UnitedHealth is already humongous.
Aetna, meanwhile, is trying to buy Humana in a deal that will create the second-largest health insurer in the nation, with 33 million members. The Justice Department has so far blocked the deal.
Insurers say they're consolidating in order to reap economies of scale. But there's little evidence that large size generates cost savings.
In reality, they're becoming huge to get more bargaining leverage over everyone they do business with - hospitals, doctors, employers, the government, and consumers. That way they make even bigger profits.
But these bigger profits come at the expense of hospitals, doctors, employers, the government, and, ultimately, taxpayers and consumers.
There's abundant evidence, for example, that when health insurers merge, premiums rise. researchers found, for example, that after Aetna merged with Prudential HealthCare in 1999, premiums rose 7 percent higher than had the merger not occurred.
What to do? In the short term, Obamacare can be patched up by enlarging government subsidies for purchasing insurance, and ensuring that healthy Americans buy insurance, as the law requires.
But these are band aids. The real choice in the future is either a hugely expensive for-profit oligopoly with the market power to charge high prices even to healthy people and stop insuring sick people.
Or else a government-run single payer system - such as is in place in almost every other advanced economy - dedicated to lower premiums and better care for everyone.
We're going to have to choose eventually.
The best argument for a single-payer health plan is the recent decision by giant health insurer Aetna to bail out next year from 11 of the 15 states where it sells Obamacare plans.Aetna's decision follows similar moves by UnitedHealth Group, the nation's largest health insurer, and by Humana, another one of the giants.
All claim they're not making enough money because too many people with serious health problems are using the Obamacare exchanges, and not enough healthy people are signing up.
The problem isn't Obamacare per se. It lies in the structure of private markets for health insurance - which creates powerful incentives to avoid sick people and attract healthy ones. Obamacare is just making this structural problem more obvious.
In a nutshell, the more sick people and the fewer healthy people a private for-profit insurer attracts, the less competitive that insurer becomes relative to other insurers that don't attract as high a percentage of the sick but a higher percentage of the healthy.
Eventually, insurers that take in too many sick and too few healthy people are driven out of business.
If insurers had no idea who'd be sick and who'd be healthy when they sign up for insurance (and keep them insured at the same price even after they become sick), this wouldn't be a problem. But they do know - and they're developing more and more sophisticated ways of finding out.
Health insurers spend lots of time, effort, and money trying to attract people who have high odds of staying healthy (the young and the fit) while doing whatever they can to fend off those who have high odds of getting sick (the older, infirm, and the unfit).
As a result we end up with the most bizarre health-insurance system imaginable: One ever better designed to avoid sick people.
If this weren't enough to convince rational people to do what most other advanced nations have done - create a single-payer system that insures everyone, funded by taxpayers - consider that America's giant health insurers are now busily consolidating into ever-larger behemoths.
UnitedHealth is already humongous.
Aetna, meanwhile, is trying to buy Humana in a deal that will create the second-largest health insurer in the nation, with 33 million members. The Justice Department has so far blocked the deal.
Insurers say they're consolidating in order to reap economies of scale. But there's little evidence that large size generates cost savings.
In reality, they're becoming huge to get more bargaining leverage over everyone they do business with - hospitals, doctors, employers, the government, and consumers. That way they make even bigger profits.
But these bigger profits come at the expense of hospitals, doctors, employers, the government, and, ultimately, taxpayers and consumers.
There's abundant evidence, for example, that when health insurers merge, premiums rise. researchers found, for example, that after Aetna merged with Prudential HealthCare in 1999, premiums rose 7 percent higher than had the merger not occurred.
What to do? In the short term, Obamacare can be patched up by enlarging government subsidies for purchasing insurance, and ensuring that healthy Americans buy insurance, as the law requires.
But these are band aids. The real choice in the future is either a hugely expensive for-profit oligopoly with the market power to charge high prices even to healthy people and stop insuring sick people.
Or else a government-run single payer system - such as is in place in almost every other advanced economy - dedicated to lower premiums and better care for everyone.
We're going to have to choose eventually.