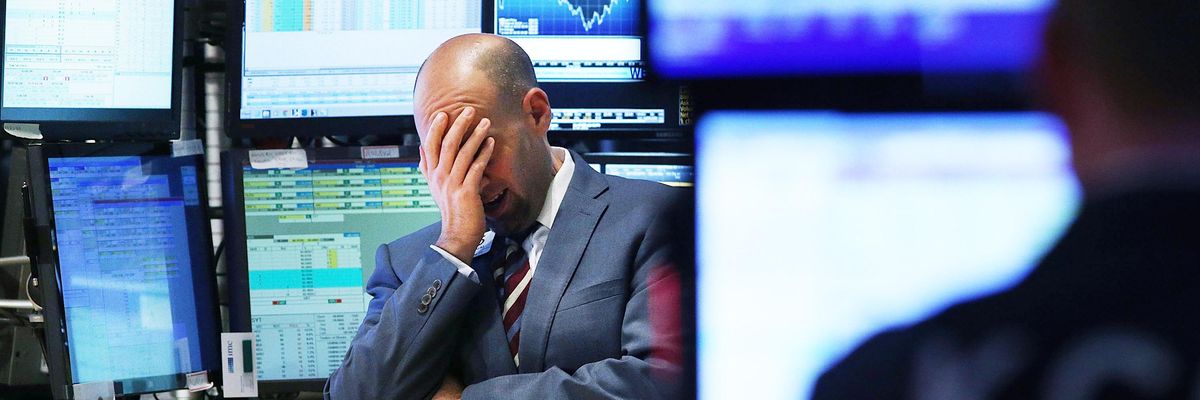
A trader works on the floor of the New York Stock Exchange (NYSE) in New York City. (Photo: Spencer Platt/Getty Images)
Senate Democrats Just Took a Bite Out of Stock Buybacks
Reining in stock buybacks can help reorient our economy to one that prioritizes the long-term needs of companies, workers, consumers, communities, and the planet.
"I hate stock buybacks," Senate Majority Leader Chuck Schumer said this past Friday.
Schumer uttered those words as the Senate was on the brink of passing the Inflation Reduction Act -- the compromise reconciliation bill that resulted from prolonged, heated negotiations amongst Democrats. The version that will go to President Biden includes something brand-new in U.S. economic policy: a one percent excise tax on stock buybacks, which reached an astonishing $882 billion last year.
"Power concedes nothing without a demand," as Frederick Douglass famously said, and Schumer's statement is proof that pressure works. The inclusion of this buybacks tax in the reconciliation package, which comes after years of work by Americans for Financial Reform, the Take on Wall Street Coalition, and their partners to highlight their bad effects and track their rise (see here for a concise fact sheet) marks a sea-change in the way the U.S. government views buybacks. And it comes about a year after Senators Sherrod Brown and Ron Wyden proposed a bill to tax them.
Moreover, it is a big win for those who want financial markets to serve the real economy -- companies with productive capacity, their workers, and research and development -- instead of the real economy serving financial markets. The latter arrangement, which is our current reality, prioritizes payouts to corporate executives and wealthy shareholders at the expense of workers, consumers, and the long-term investments necessary for sustainable and equitable economic growth. Buybacks also exacerbate economic inequality and the racial wealth gap.
Stock buybacks occur when a company purchases its own shares, resulting in fewer outstanding shares, which in turn results in higher earnings per share (EPS). This artificial boost in EPS benefits executives, who often receive compensation packages that are more than 80 percent stock awards and stock options.
Not only do executives benefit from the higher EPS the execution of stock buybacks results in, but they also benefit from the short-term bump in share price that results from a company's announcement of buybacks. Indeed, research conducted by then SEC Commissioner Robert Jackson found that executives sold five times more shares in the eight days following a buyback announcement compared to the days before the announcement.
Meanwhile, every dollar spent on stock buybacks is a dollar not spent on raising worker wages, research and development, and other productivity-boosting investments. Studies have shown that stock buybacks are associated with wage stagnation and layoffs, investment slowdowns, and reduced innovation.
"I think they're one of the most self-serving things that corporate America does," Schumer continued. "Instead of investing in workers and in training and in research and in equipment, they simply -- they don't do a thing to make their company better and they artificially raise the stock price by just reducing the number of shares."
Instead of workers being treated as important partners in ensuring the long-term well-being of companies and the economy as a whole, labor is treated as a cost to minimize so that shareholders and corporate executives can be rewarded in the short term.
The rampant use of buybacks at the height of the Covid-19 pandemic, even as many workers were losing their jobs and many others were being forced to work in unsafe conditions, is a perfect example of how buybacks unfairly prioritize short-term shareholder returns and the wealth of corporate executives over the safety and urgent needs of workers and their communities.
The Institute for Policy Studies revealed how companies that pay low wages also engaged in rampant stock buybacks, amplifying the CEO-worker pay gap. And at every step of the fight, unions, including the Communications Workers of America, have emphasized how stock buybacks hurt workers and society.
The racial disparity in stock ownership turns buybacks into an accelerator of the racial wealth gap. White households, as of the fourth quarter of 2021, owned almost 90 percent of corporate equity and mutual fund value, while Black households owned 1.1 percent and Latinx households owned 0.4 percent. Additionally, Lenore Palladino, a professor at UMass Amherst, meticulously documented how the proportion of the racial wealth gap attributable to corporate equity ownership has grown over time.
Excessive stock buybacks hurt consumers and our society as a whole. Abbott, a maker of baby formula, spent billions on stock buybacks while skimping on investments needed to keep their product safe and in production.
Reining in stock buybacks, then, can help reorient our economy to one that prioritizes the long-term needs of companies, workers, consumers, communities, and the planet. The 1 percent excise tax on stock buybacks included in the reconciliation package is a significant step forward. Other progress includes: the Commerce Department's recent announcement that they will give priority in awarding CHIPS funds to companies that do not engage in stock buybacks; the SEC's proposed rule requiring daily disclosures of stock buybacks; and President Biden's expressed support in his FY23 budget proposal of legislation "requiring executives to hold on to company shares that they receive for several years after receiving them, and prohibiting them from selling shares in the years after a stock buyback."
Congress should also pass the Reward Work Act, which would ban open-market stock buybacks. Congress should also ensure that public money benefits the public by including common-sense guardrails -- including a ban on stock buybacks -- whenever it passes legislation giving money to companies. The Biden administration should prohibit federal contractors from engaging in stock buybacks for the duration of the contract. Lastly, the SEC should rescind the stock buybacks safe harbor it created in 1982, which some argue amounted to legalizing stock market manipulation. Before then, companies had to worry about being held liable for market manipulation under the Securities Act.
It is time to move away from a financial system that exacerbates inequality and systemic racism, and toward one that promotes a just and sustainable economy. Curbing stock buybacks will help get us there. A small tax on buybacks is a start, but there is still much more to do.
Originally published by Americans for Financial Reform.
We are at a crossroads
This country and this world are at a monumental crossroads. In a few short weeks, US voters will have an opportunity to beat back the forces of fascism and confront the billionaires who are rigging the economy, our media system, and our democracy, making it increasingly impossible for ordinary people to get by. We’re not just talking about the election. We’re talking about what must be done once these fascist elements are vanquished from power. We need a bolder set of solutions than what either major party has so far been willing to offer and a working-class movement ready to fight like hell for it. Trump didn't emerge from nowhere. The conditions that fueled MAGA authoritarianism were created by decades of radical neoliberal economic policies and a corrupt political system dominated by corporate interests. They slashed taxes on the super-rich, promising that the benefits would trickle down. They said giveaways to the corporate titans would make life more affordable for the rest of us. It was all bullshit. And when a bitter, betrayed populace searches for someone to blame, right-wing demagogues have little trouble finding scapegoats. People know when they're being lied to, but you won't hear any of this from the corporate media. Only independent journalism—powered and funded by people who believe in building a better world—can deliver truly trustworthy daily news. Our Fall Campaign is underway, and we need your help. To power our newsroom through the rest of the year, we need to raise $125,000 by midnight on October 31. So if you share our vision, please contribute whatever you can to sustain our work. |
"I hate stock buybacks," Senate Majority Leader Chuck Schumer said this past Friday.
Schumer uttered those words as the Senate was on the brink of passing the Inflation Reduction Act -- the compromise reconciliation bill that resulted from prolonged, heated negotiations amongst Democrats. The version that will go to President Biden includes something brand-new in U.S. economic policy: a one percent excise tax on stock buybacks, which reached an astonishing $882 billion last year.
"Power concedes nothing without a demand," as Frederick Douglass famously said, and Schumer's statement is proof that pressure works. The inclusion of this buybacks tax in the reconciliation package, which comes after years of work by Americans for Financial Reform, the Take on Wall Street Coalition, and their partners to highlight their bad effects and track their rise (see here for a concise fact sheet) marks a sea-change in the way the U.S. government views buybacks. And it comes about a year after Senators Sherrod Brown and Ron Wyden proposed a bill to tax them.
Moreover, it is a big win for those who want financial markets to serve the real economy -- companies with productive capacity, their workers, and research and development -- instead of the real economy serving financial markets. The latter arrangement, which is our current reality, prioritizes payouts to corporate executives and wealthy shareholders at the expense of workers, consumers, and the long-term investments necessary for sustainable and equitable economic growth. Buybacks also exacerbate economic inequality and the racial wealth gap.
Stock buybacks occur when a company purchases its own shares, resulting in fewer outstanding shares, which in turn results in higher earnings per share (EPS). This artificial boost in EPS benefits executives, who often receive compensation packages that are more than 80 percent stock awards and stock options.
Not only do executives benefit from the higher EPS the execution of stock buybacks results in, but they also benefit from the short-term bump in share price that results from a company's announcement of buybacks. Indeed, research conducted by then SEC Commissioner Robert Jackson found that executives sold five times more shares in the eight days following a buyback announcement compared to the days before the announcement.
Meanwhile, every dollar spent on stock buybacks is a dollar not spent on raising worker wages, research and development, and other productivity-boosting investments. Studies have shown that stock buybacks are associated with wage stagnation and layoffs, investment slowdowns, and reduced innovation.
"I think they're one of the most self-serving things that corporate America does," Schumer continued. "Instead of investing in workers and in training and in research and in equipment, they simply -- they don't do a thing to make their company better and they artificially raise the stock price by just reducing the number of shares."
Instead of workers being treated as important partners in ensuring the long-term well-being of companies and the economy as a whole, labor is treated as a cost to minimize so that shareholders and corporate executives can be rewarded in the short term.
The rampant use of buybacks at the height of the Covid-19 pandemic, even as many workers were losing their jobs and many others were being forced to work in unsafe conditions, is a perfect example of how buybacks unfairly prioritize short-term shareholder returns and the wealth of corporate executives over the safety and urgent needs of workers and their communities.
The Institute for Policy Studies revealed how companies that pay low wages also engaged in rampant stock buybacks, amplifying the CEO-worker pay gap. And at every step of the fight, unions, including the Communications Workers of America, have emphasized how stock buybacks hurt workers and society.
The racial disparity in stock ownership turns buybacks into an accelerator of the racial wealth gap. White households, as of the fourth quarter of 2021, owned almost 90 percent of corporate equity and mutual fund value, while Black households owned 1.1 percent and Latinx households owned 0.4 percent. Additionally, Lenore Palladino, a professor at UMass Amherst, meticulously documented how the proportion of the racial wealth gap attributable to corporate equity ownership has grown over time.
Excessive stock buybacks hurt consumers and our society as a whole. Abbott, a maker of baby formula, spent billions on stock buybacks while skimping on investments needed to keep their product safe and in production.
Reining in stock buybacks, then, can help reorient our economy to one that prioritizes the long-term needs of companies, workers, consumers, communities, and the planet. The 1 percent excise tax on stock buybacks included in the reconciliation package is a significant step forward. Other progress includes: the Commerce Department's recent announcement that they will give priority in awarding CHIPS funds to companies that do not engage in stock buybacks; the SEC's proposed rule requiring daily disclosures of stock buybacks; and President Biden's expressed support in his FY23 budget proposal of legislation "requiring executives to hold on to company shares that they receive for several years after receiving them, and prohibiting them from selling shares in the years after a stock buyback."
Congress should also pass the Reward Work Act, which would ban open-market stock buybacks. Congress should also ensure that public money benefits the public by including common-sense guardrails -- including a ban on stock buybacks -- whenever it passes legislation giving money to companies. The Biden administration should prohibit federal contractors from engaging in stock buybacks for the duration of the contract. Lastly, the SEC should rescind the stock buybacks safe harbor it created in 1982, which some argue amounted to legalizing stock market manipulation. Before then, companies had to worry about being held liable for market manipulation under the Securities Act.
It is time to move away from a financial system that exacerbates inequality and systemic racism, and toward one that promotes a just and sustainable economy. Curbing stock buybacks will help get us there. A small tax on buybacks is a start, but there is still much more to do.
Originally published by Americans for Financial Reform.