SUBSCRIBE TO OUR FREE NEWSLETTER
Daily news & progressive opinion—funded by the people, not the corporations—delivered straight to your inbox.
5
#000000
#FFFFFF
To donate by check, phone, or other method, see our More Ways to Give page.
Daily news & progressive opinion—funded by the people, not the corporations—delivered straight to your inbox.
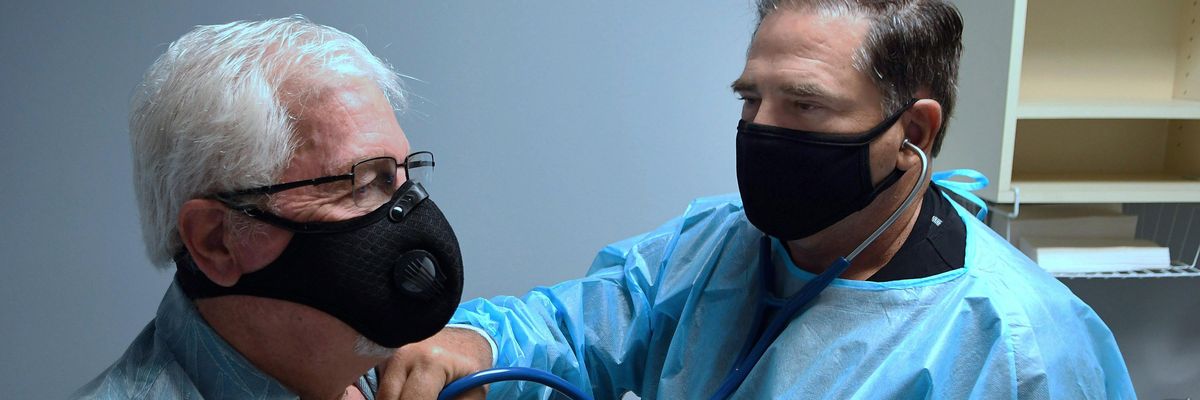
Original Medicare enrollees who do not have supplemental coverage are at substantial financial and health risk. (Photo: Paul Hennessy/NurPhoto via Getty Images)
It's well understood that health care costs are out of control in America. Older and disabled Americans are hit hardest because we use three times more health care services than working people. Congress can and should ensure health care is affordable to us through a reasonable Medicare out-of-pocket cap.
To be clear, original Medicare works well for many who can afford supplemental coverage that picks up most of Medicare's out-of-pocket costs. They can buy great health care protection and they don't have to decide between their rent and a hospital procedure.
Over half of all people with Medicare live on annual incomes under $30,000.
However, millions of people with Medicare cannot afford private supplemental coverage. Higher health care costs are driving premium, deductible, co-pay and coinsurance costs up. According to the 2020 Medicare Trustees' Report, the Center for Medicare Services (CMS) projects Medicare payments more than double from $797 billion in 2019 to $1.6 trillion by 2029. That's an increase of $649 per enrollee per month - $7,778 annually!
This imminent tsunami will be especially tragic for those in original Medicare who are not protected by a reasonable out-of-pocket cap. Today, over half of all people with Medicare live on annual incomes under $30,000. At this level and even at much higher incomes, sticker shock is already very real today. In 7-8 years, it will be catastrophic.
Millions more people with Medicare cannot buy supplemental coverage even if they can afford it. They have no guaranteed right to buy it in most cases, after their initial enrollment period in Medicare. Consider the example of a 65-year-olds who enroll in in a Medicare Advantage (MA) plan, but later switch to original Medicare without an out-of-pocket cap. If they contract cancer 2 years later and then try to purchase Medigap coverage, insurers will often deny them.
Original Medicare enrollees who do not have supplemental coverage are at substantial financial and health risk. A single chronic illness or catastrophic health event can lead to bankruptcy. With the Affordable Care Act (ACA), Congress ensured that everyone with private health insurance had an out-of-pocket limit for their health care. However, people with Medicare are not covered by the ACA.
MA plans, which offer Medicare benefits through private health insurers, are required to provide out-of-pocket financial protection to their enrollees. (That said, the limit is exorbitant at as much as $7,550 in 2021.) Congress should ensure that everyone with Medicare has a reasonable limit on financial liability for their care.
A low out-of-pocket cap in Medicare would save lives and help millions of lower and middle-income people with Medicare who are skipping needed care.
A reasonable out-of-pocket cap would ensure that those over age-65 have meaningful access to three alternative choices. They could enroll in original Medicare with an out-of-pocket cap or Medigap or in a MA plan knowing their costs would be limited. People with complex conditions, people under 65 with disabilities, people who live in rural communities and people who move throughout the year, among others, often need optional choices. Adding an out-of-pocket cap to original Medicare would satisfy these needs.
Giving people a meaningful choice of original Medicare has programmatic benefits as well as health benefits. Since its inception, Medicare Advantage has cost the Medicare Trust Fund significantly more per person than original Medicare. Medicare Advantage also drives up Part B premiums. Original Medicare is far more cost-effective.
Adding an out-of-pocket cap to original Medicare can be a steppingstone toward addressing long-term care (LTC) services that can cost $15,000 a month today, much more by 2029. Over 61 million Americans use LTC services today.
MedPAC and the Medicare Trustees' report data reveal that private MA plans have captured over 44% of the Medicare market. In 2021, over $41 billion in federal rebates will be doled out to MA plan insurers. That's $140 per month per MA plan enrollee. Why not apply some of that $140 a month to cap out-of-pocket costs for everyone in Medicare?
The last published U.S. Census projected that by 2060, when our grandchildren and greatgrandchildren will need affordable health care coverage in retirement, there will be 100 million Americans over age 65--nearly 25 percent of the U.S. population.
Now is the time for Congress to set forward-looking health care policies. That includes adding an out-of-pocket cap to original Medicare so that it can continue as a better choice than the more costly Medicare Advantage private plans and can offer a competitive alternative to Medigap private plans.
This country and this world are at a monumental crossroads. US voters have an opportunity to beat back the forces of fascism and confront the billionaires who are rigging the economy, our media system, and our democracy, making it increasingly impossible for ordinary people to get by. We’re not just talking about the election. We’re talking about what must be done once these fascist elements are vanquished from power. We need a bolder set of solutions than what either major party has so far been willing to offer and a working-class movement ready to fight like hell for it. Trump didn't emerge from nowhere. The conditions that fueled MAGA authoritarianism were created by decades of radical neoliberal economic policies and a corrupt political system dominated by corporate interests. They slashed taxes on the super-rich, promising that the benefits would trickle down. They said giveaways to the corporate titans would make life more affordable for the rest of us. It was all bullshit. And when a bitter, betrayed populace searches for someone to blame, right-wing demagogues have little trouble finding scapegoats. People know when they're being lied to, but you won't hear any of this from the corporate media. Only independent journalism—powered and funded by people who believe in building a better world—can deliver truly trustworthy daily news. If you share our vision, please contribute whatever you can to sustain our work. |
It's well understood that health care costs are out of control in America. Older and disabled Americans are hit hardest because we use three times more health care services than working people. Congress can and should ensure health care is affordable to us through a reasonable Medicare out-of-pocket cap.
To be clear, original Medicare works well for many who can afford supplemental coverage that picks up most of Medicare's out-of-pocket costs. They can buy great health care protection and they don't have to decide between their rent and a hospital procedure.
Over half of all people with Medicare live on annual incomes under $30,000.
However, millions of people with Medicare cannot afford private supplemental coverage. Higher health care costs are driving premium, deductible, co-pay and coinsurance costs up. According to the 2020 Medicare Trustees' Report, the Center for Medicare Services (CMS) projects Medicare payments more than double from $797 billion in 2019 to $1.6 trillion by 2029. That's an increase of $649 per enrollee per month - $7,778 annually!
This imminent tsunami will be especially tragic for those in original Medicare who are not protected by a reasonable out-of-pocket cap. Today, over half of all people with Medicare live on annual incomes under $30,000. At this level and even at much higher incomes, sticker shock is already very real today. In 7-8 years, it will be catastrophic.
Millions more people with Medicare cannot buy supplemental coverage even if they can afford it. They have no guaranteed right to buy it in most cases, after their initial enrollment period in Medicare. Consider the example of a 65-year-olds who enroll in in a Medicare Advantage (MA) plan, but later switch to original Medicare without an out-of-pocket cap. If they contract cancer 2 years later and then try to purchase Medigap coverage, insurers will often deny them.
Original Medicare enrollees who do not have supplemental coverage are at substantial financial and health risk. A single chronic illness or catastrophic health event can lead to bankruptcy. With the Affordable Care Act (ACA), Congress ensured that everyone with private health insurance had an out-of-pocket limit for their health care. However, people with Medicare are not covered by the ACA.
MA plans, which offer Medicare benefits through private health insurers, are required to provide out-of-pocket financial protection to their enrollees. (That said, the limit is exorbitant at as much as $7,550 in 2021.) Congress should ensure that everyone with Medicare has a reasonable limit on financial liability for their care.
A low out-of-pocket cap in Medicare would save lives and help millions of lower and middle-income people with Medicare who are skipping needed care.
A reasonable out-of-pocket cap would ensure that those over age-65 have meaningful access to three alternative choices. They could enroll in original Medicare with an out-of-pocket cap or Medigap or in a MA plan knowing their costs would be limited. People with complex conditions, people under 65 with disabilities, people who live in rural communities and people who move throughout the year, among others, often need optional choices. Adding an out-of-pocket cap to original Medicare would satisfy these needs.
Giving people a meaningful choice of original Medicare has programmatic benefits as well as health benefits. Since its inception, Medicare Advantage has cost the Medicare Trust Fund significantly more per person than original Medicare. Medicare Advantage also drives up Part B premiums. Original Medicare is far more cost-effective.
Adding an out-of-pocket cap to original Medicare can be a steppingstone toward addressing long-term care (LTC) services that can cost $15,000 a month today, much more by 2029. Over 61 million Americans use LTC services today.
MedPAC and the Medicare Trustees' report data reveal that private MA plans have captured over 44% of the Medicare market. In 2021, over $41 billion in federal rebates will be doled out to MA plan insurers. That's $140 per month per MA plan enrollee. Why not apply some of that $140 a month to cap out-of-pocket costs for everyone in Medicare?
The last published U.S. Census projected that by 2060, when our grandchildren and greatgrandchildren will need affordable health care coverage in retirement, there will be 100 million Americans over age 65--nearly 25 percent of the U.S. population.
Now is the time for Congress to set forward-looking health care policies. That includes adding an out-of-pocket cap to original Medicare so that it can continue as a better choice than the more costly Medicare Advantage private plans and can offer a competitive alternative to Medigap private plans.
It's well understood that health care costs are out of control in America. Older and disabled Americans are hit hardest because we use three times more health care services than working people. Congress can and should ensure health care is affordable to us through a reasonable Medicare out-of-pocket cap.
To be clear, original Medicare works well for many who can afford supplemental coverage that picks up most of Medicare's out-of-pocket costs. They can buy great health care protection and they don't have to decide between their rent and a hospital procedure.
Over half of all people with Medicare live on annual incomes under $30,000.
However, millions of people with Medicare cannot afford private supplemental coverage. Higher health care costs are driving premium, deductible, co-pay and coinsurance costs up. According to the 2020 Medicare Trustees' Report, the Center for Medicare Services (CMS) projects Medicare payments more than double from $797 billion in 2019 to $1.6 trillion by 2029. That's an increase of $649 per enrollee per month - $7,778 annually!
This imminent tsunami will be especially tragic for those in original Medicare who are not protected by a reasonable out-of-pocket cap. Today, over half of all people with Medicare live on annual incomes under $30,000. At this level and even at much higher incomes, sticker shock is already very real today. In 7-8 years, it will be catastrophic.
Millions more people with Medicare cannot buy supplemental coverage even if they can afford it. They have no guaranteed right to buy it in most cases, after their initial enrollment period in Medicare. Consider the example of a 65-year-olds who enroll in in a Medicare Advantage (MA) plan, but later switch to original Medicare without an out-of-pocket cap. If they contract cancer 2 years later and then try to purchase Medigap coverage, insurers will often deny them.
Original Medicare enrollees who do not have supplemental coverage are at substantial financial and health risk. A single chronic illness or catastrophic health event can lead to bankruptcy. With the Affordable Care Act (ACA), Congress ensured that everyone with private health insurance had an out-of-pocket limit for their health care. However, people with Medicare are not covered by the ACA.
MA plans, which offer Medicare benefits through private health insurers, are required to provide out-of-pocket financial protection to their enrollees. (That said, the limit is exorbitant at as much as $7,550 in 2021.) Congress should ensure that everyone with Medicare has a reasonable limit on financial liability for their care.
A low out-of-pocket cap in Medicare would save lives and help millions of lower and middle-income people with Medicare who are skipping needed care.
A reasonable out-of-pocket cap would ensure that those over age-65 have meaningful access to three alternative choices. They could enroll in original Medicare with an out-of-pocket cap or Medigap or in a MA plan knowing their costs would be limited. People with complex conditions, people under 65 with disabilities, people who live in rural communities and people who move throughout the year, among others, often need optional choices. Adding an out-of-pocket cap to original Medicare would satisfy these needs.
Giving people a meaningful choice of original Medicare has programmatic benefits as well as health benefits. Since its inception, Medicare Advantage has cost the Medicare Trust Fund significantly more per person than original Medicare. Medicare Advantage also drives up Part B premiums. Original Medicare is far more cost-effective.
Adding an out-of-pocket cap to original Medicare can be a steppingstone toward addressing long-term care (LTC) services that can cost $15,000 a month today, much more by 2029. Over 61 million Americans use LTC services today.
MedPAC and the Medicare Trustees' report data reveal that private MA plans have captured over 44% of the Medicare market. In 2021, over $41 billion in federal rebates will be doled out to MA plan insurers. That's $140 per month per MA plan enrollee. Why not apply some of that $140 a month to cap out-of-pocket costs for everyone in Medicare?
The last published U.S. Census projected that by 2060, when our grandchildren and greatgrandchildren will need affordable health care coverage in retirement, there will be 100 million Americans over age 65--nearly 25 percent of the U.S. population.
Now is the time for Congress to set forward-looking health care policies. That includes adding an out-of-pocket cap to original Medicare so that it can continue as a better choice than the more costly Medicare Advantage private plans and can offer a competitive alternative to Medigap private plans.