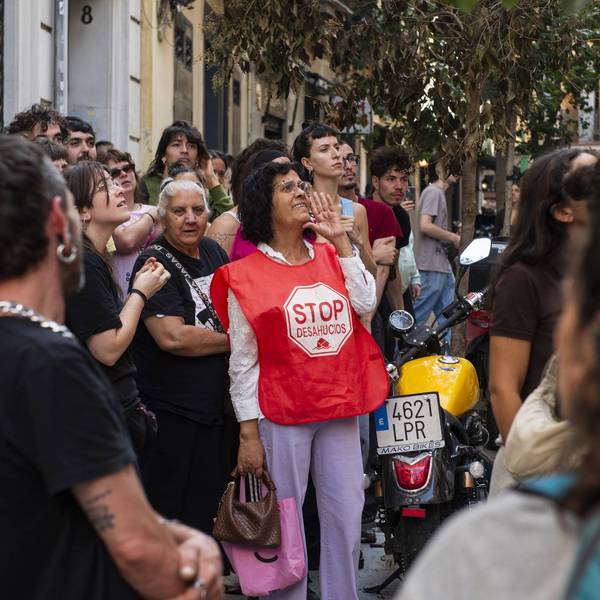

If homeowners and government workers are not able to create sufficient demand to restore economic growth the federal government must step in. (Photo: Erik McGregor/LightRocket via Getty Images)
Whoever Wins the Election Will Face Severe Eviction Crisis, as 30 Million Brace for Homelessness
Despite the massive mortgage debt overhang and the impending foreclosure crisis there is very little talk about how debt might be restructured or how to house the many who will be left homeless.
Whoever wins Tuesday's election is virtually certain to be confronted by a severe foreclosure and eviction crisis as state and local governments face acute budget shortfalls. These crises interact with each other and in ways that intensify the economic damage they inflict. The harm is also psychological and political. There are lessons to be learned from the last great foreclosure, 2008-2009.
US households were in tenuous shape for years leading up to the onset of COVID--19, Consequently we should not be surprised by the implications tfor the housing market. The Wall Street Journal reports: "about a quarter of American renter households with children are now carrying debt from not paying rent, U.S. Census Bureau surveys show... Mounting rental debt could also impede the path to a U.S. economic recovery, when 30 million to 40 million people from New York City to San Francisco face potential eviction once moratoriums expire."...
If foreclosures and evictions are standing in the way of recovery, it is also safe to say that the draconian cuts in budgets of state and local governments translate into wage reductions and/or unemployment for pubic sector workers and thus more pressures on the housing market.
If homeowners and government workers are not able to create sufficient demand to restore economic growth the federal government must step in. State governments are constitutionally prohibited from borrowing for daily expenses.
Resolution of the subprime mortgage crisis required a federal bailout of the banks holding these toxic instruments. But did saving the banking system require saving the bankers whose malfeasance caused the crisis? Borrowers lost their homes and savings even as bankers reaped multi million dollar bonuses. Borrowers alone were punished despite the fact that for every improvident borrower there is a reckless or manipulative lender.
The bailout legislation in effect recognized this more truth and allotted a portion of the bailout relief for homeowners. Nonetheless, the Obama Administration chose not to implement that part of the legislation even though assistance to ordinary borrowers would have been at least as effective in saving the banking system. This despite the fact that this controversial legislation was passed only by commitment to foreclosure relief as a part of the TARP program
The implications of this neglect were significant and long-lasting. Michael Olenick argues: "This frustration, the betrayal from the right and the left, led to enormous anger. People wanted to burn something down and, at just the right time, Trump came down the escalator promising to do exactly that."
Despite the massive mortgage debt overhang and the impending foreclosure crisis there is very little talk about how debt might be restructured or how to house the many who will be left homeless. What talk there is once again seems to blame the debtors. Yves Smith, founder of the blog Naked Capitalism, reprints an especially nasty example of this genre from the Letters column of the Wall Street Journal:
Howard S
- "Single mothers are suddenly discovering why its good to have a responsible husband who works and supports his family before you start making babies. Bad decisions have bad consequences."
Like the authors of the first bailout, Howard S has also forgotten that for every irresponsible borrower there is a reckless lender. In any case however much some may rant and rave, these debts are far too massive ever to be paid down in full.. They will be restructured either by major depressions, war, bankruptcy courts,- or democratic political movements.
As regards the last alternative, in Debunking Economics Australian economist Steve Keen presents a provocative intervention into debates about debt forgiveness. He acknowledges that debt forgiveness can hurt creditors, a class that might include workers' pension funds as well as affluent investors. He advocates instead a simple one- time grant of say $50,000, which can be spent only after it has been used to pay down any personal debt. This proposal has several merits. Because it is universal, it would help the thrifty homeowners sufficiently who have paid off most of their mortgage while also aiding those under water from home or student loans. With another debt foreclosure crisis coming it is imperative that such ideas receive a fair hearing.
We are at a crossroads
This country and this world are at a monumental crossroads. In a few short weeks, US voters will have an opportunity to beat back the forces of fascism and confront the billionaires who are rigging the economy, our media system, and our democracy, making it increasingly impossible for ordinary people to get by. We’re not just talking about the election. We’re talking about what must be done once these fascist elements are vanquished from power. We need a bolder set of solutions than what either major party has so far been willing to offer and a working-class movement ready to fight like hell for it. Trump didn't emerge from nowhere. The conditions that fueled MAGA authoritarianism were created by decades of radical neoliberal economic policies and a corrupt political system dominated by corporate interests. They slashed taxes on the super-rich, promising that the benefits would trickle down. They said giveaways to the corporate titans would make life more affordable for the rest of us. It was all bullshit. And when a bitter, betrayed populace searches for someone to blame, right-wing demagogues have little trouble finding scapegoats. People know when they're being lied to, but you won't hear any of this from the corporate media. Only independent journalism—powered and funded by people who believe in building a better world—can deliver truly trustworthy daily news. Our Fall Campaign is underway, and we need your help. To power our newsroom through the rest of the year, we need to raise $125,000 by midnight on October 31. So if you share our vision, please contribute whatever you can to sustain our work. |
Whoever wins Tuesday's election is virtually certain to be confronted by a severe foreclosure and eviction crisis as state and local governments face acute budget shortfalls. These crises interact with each other and in ways that intensify the economic damage they inflict. The harm is also psychological and political. There are lessons to be learned from the last great foreclosure, 2008-2009.
US households were in tenuous shape for years leading up to the onset of COVID--19, Consequently we should not be surprised by the implications tfor the housing market. The Wall Street Journal reports: "about a quarter of American renter households with children are now carrying debt from not paying rent, U.S. Census Bureau surveys show... Mounting rental debt could also impede the path to a U.S. economic recovery, when 30 million to 40 million people from New York City to San Francisco face potential eviction once moratoriums expire."...
If foreclosures and evictions are standing in the way of recovery, it is also safe to say that the draconian cuts in budgets of state and local governments translate into wage reductions and/or unemployment for pubic sector workers and thus more pressures on the housing market.
If homeowners and government workers are not able to create sufficient demand to restore economic growth the federal government must step in. State governments are constitutionally prohibited from borrowing for daily expenses.
Resolution of the subprime mortgage crisis required a federal bailout of the banks holding these toxic instruments. But did saving the banking system require saving the bankers whose malfeasance caused the crisis? Borrowers lost their homes and savings even as bankers reaped multi million dollar bonuses. Borrowers alone were punished despite the fact that for every improvident borrower there is a reckless or manipulative lender.
The bailout legislation in effect recognized this more truth and allotted a portion of the bailout relief for homeowners. Nonetheless, the Obama Administration chose not to implement that part of the legislation even though assistance to ordinary borrowers would have been at least as effective in saving the banking system. This despite the fact that this controversial legislation was passed only by commitment to foreclosure relief as a part of the TARP program
The implications of this neglect were significant and long-lasting. Michael Olenick argues: "This frustration, the betrayal from the right and the left, led to enormous anger. People wanted to burn something down and, at just the right time, Trump came down the escalator promising to do exactly that."
Despite the massive mortgage debt overhang and the impending foreclosure crisis there is very little talk about how debt might be restructured or how to house the many who will be left homeless. What talk there is once again seems to blame the debtors. Yves Smith, founder of the blog Naked Capitalism, reprints an especially nasty example of this genre from the Letters column of the Wall Street Journal:
Howard S
- "Single mothers are suddenly discovering why its good to have a responsible husband who works and supports his family before you start making babies. Bad decisions have bad consequences."
Like the authors of the first bailout, Howard S has also forgotten that for every irresponsible borrower there is a reckless lender. In any case however much some may rant and rave, these debts are far too massive ever to be paid down in full.. They will be restructured either by major depressions, war, bankruptcy courts,- or democratic political movements.
As regards the last alternative, in Debunking Economics Australian economist Steve Keen presents a provocative intervention into debates about debt forgiveness. He acknowledges that debt forgiveness can hurt creditors, a class that might include workers' pension funds as well as affluent investors. He advocates instead a simple one- time grant of say $50,000, which can be spent only after it has been used to pay down any personal debt. This proposal has several merits. Because it is universal, it would help the thrifty homeowners sufficiently who have paid off most of their mortgage while also aiding those under water from home or student loans. With another debt foreclosure crisis coming it is imperative that such ideas receive a fair hearing.