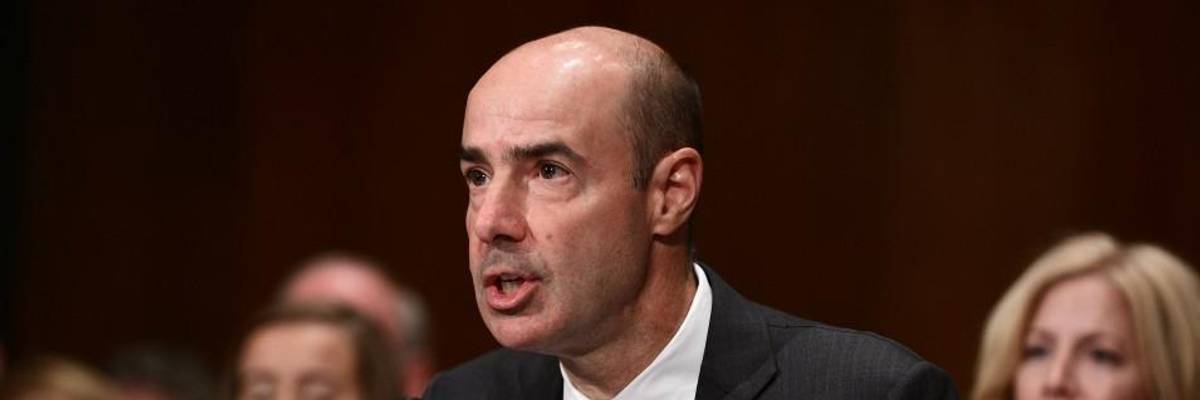
Eugene Scalia attends his confirmation hearing to become the next U.S. labor secretary in front of the the U.S. Senate Committee on Health, Education, Labor and Pensions (HELP) on Sept. 19, 2019. (Photo: Astrid Riecken/Getty Images)
New Labor Department Guidance Allows Risky Private Equity Investments in Workers' 401(k) Accounts
Scalia has rolled back rules that protected workers' retirement security. This should be seen as a gift to private equity firms, not a favor to workers.
Private Equity (PE) firms have had their eye on workers' retirement nest eggs -- 401(k) and IRA accounts -- since late 2013 when rules on advertising to individuals were relaxed. Obama's labor department stymied private equity's efforts to expose ordinary people to high levels of financial risk.
Yesterday, under cover of pandemic and protests, Labor Secretary Scalia set those concerns aside and issued a letter to allow private equity investments to be included in workers' retirement accounts. Scalia claims he was acting on President Trump's instructions to "remove barriers ... to economic prosperity."
But PE is certainly not constrained by a lack of dollars for acquiring Main Street companies. It is not held back by barriers. On the contrary, PE firms are sitting on well over a trillion dollars of dry powder waiting to be put to use buying up companies beaten down by the coronavirus. Whether it is wise to allow this is clearly debatable. Other countries are protecting their businesses from being acquired by private equity firms at fire-sale prices by halting mergers and acquisitions until the pandemic is past and companies have recovered from the economic shock of the lockdown.
Investing retirement savings in private equity exposes ordinary retirees to high risk. In the letter, Scalia himself acknowledges the "potential cost, complexity, [lack of] disclosures, and liquidity issues" these investments pose. Unsophisticated investors, self-interested financial advisors, and opaque private equity firms -- what could go wrong?
Scalia hedges on the payoff to workers from this higher risk, noting that investing in PE "often provide[s] strong returns," meaning workers can't count on these returns, no matter what the industry hype suggests. In fact, returns for the typical PE fund launched since 2006, properly measured, have tended to match the stock market's returns with little to no added premium for the added risk. About half the funds launched in each year since then have underperformed the stock market. The high-performing funds of PE firms are oversubscribed -- ordinary individuals will likely have difficulty accessing them.
Workers have socked away $6.2 trillion in 401(k) accounts and another $2.5 trillion in IRA accounts. PE has been lobbying for years to get its hands on even a fraction of these funds. If just 5 percent of the money in these retirement funds were available to private equity, it would be a windfall of $435 billion -- real money even to private equity millionaires and billionaires. The value proposition for workers, whose retirement income will likely be eaten up by fees for returns that may not materialize, is much less clear.
Scalia has rolled back rules that protected workers' retirement security. This should be seen as a gift to private equity firms, not a favor to workers who are unlikely to cash in on mythical high PE returns.
We are at a crossroads
This country and this world are at a monumental crossroads. In a few short weeks, US voters will have an opportunity to beat back the forces of fascism and confront the billionaires who are rigging the economy, our media system, and our democracy, making it increasingly impossible for ordinary people to get by. We’re not just talking about the election. We’re talking about what must be done once these fascist elements are vanquished from power. We need a bolder set of solutions than what either major party has so far been willing to offer and a working-class movement ready to fight like hell for it. Trump didn't emerge from nowhere. The conditions that fueled MAGA authoritarianism were created by decades of radical neoliberal economic policies and a corrupt political system dominated by corporate interests. They slashed taxes on the super-rich, promising that the benefits would trickle down. They said giveaways to the corporate titans would make life more affordable for the rest of us. It was all bullshit. And when a bitter, betrayed populace searches for someone to blame, right-wing demagogues have little trouble finding scapegoats. People know when they're being lied to, but you won't hear any of this from the corporate media. Only independent journalism—powered and funded by people who believe in building a better world—can deliver truly trustworthy daily news. Our Fall Campaign is underway, and we need your help. To power our newsroom through the rest of the year, we need to raise $125,000 by midnight on October 31. So if you share our vision, please contribute whatever you can to sustain our work. |
Private Equity (PE) firms have had their eye on workers' retirement nest eggs -- 401(k) and IRA accounts -- since late 2013 when rules on advertising to individuals were relaxed. Obama's labor department stymied private equity's efforts to expose ordinary people to high levels of financial risk.
Yesterday, under cover of pandemic and protests, Labor Secretary Scalia set those concerns aside and issued a letter to allow private equity investments to be included in workers' retirement accounts. Scalia claims he was acting on President Trump's instructions to "remove barriers ... to economic prosperity."
But PE is certainly not constrained by a lack of dollars for acquiring Main Street companies. It is not held back by barriers. On the contrary, PE firms are sitting on well over a trillion dollars of dry powder waiting to be put to use buying up companies beaten down by the coronavirus. Whether it is wise to allow this is clearly debatable. Other countries are protecting their businesses from being acquired by private equity firms at fire-sale prices by halting mergers and acquisitions until the pandemic is past and companies have recovered from the economic shock of the lockdown.
Investing retirement savings in private equity exposes ordinary retirees to high risk. In the letter, Scalia himself acknowledges the "potential cost, complexity, [lack of] disclosures, and liquidity issues" these investments pose. Unsophisticated investors, self-interested financial advisors, and opaque private equity firms -- what could go wrong?
Scalia hedges on the payoff to workers from this higher risk, noting that investing in PE "often provide[s] strong returns," meaning workers can't count on these returns, no matter what the industry hype suggests. In fact, returns for the typical PE fund launched since 2006, properly measured, have tended to match the stock market's returns with little to no added premium for the added risk. About half the funds launched in each year since then have underperformed the stock market. The high-performing funds of PE firms are oversubscribed -- ordinary individuals will likely have difficulty accessing them.
Workers have socked away $6.2 trillion in 401(k) accounts and another $2.5 trillion in IRA accounts. PE has been lobbying for years to get its hands on even a fraction of these funds. If just 5 percent of the money in these retirement funds were available to private equity, it would be a windfall of $435 billion -- real money even to private equity millionaires and billionaires. The value proposition for workers, whose retirement income will likely be eaten up by fees for returns that may not materialize, is much less clear.
Scalia has rolled back rules that protected workers' retirement security. This should be seen as a gift to private equity firms, not a favor to workers who are unlikely to cash in on mythical high PE returns.