SUBSCRIBE TO OUR FREE NEWSLETTER
Daily news & progressive opinion—funded by the people, not the corporations—delivered straight to your inbox.
5
#000000
#FFFFFF
To donate by check, phone, or other method, see our More Ways to Give page.
Daily news & progressive opinion—funded by the people, not the corporations—delivered straight to your inbox.
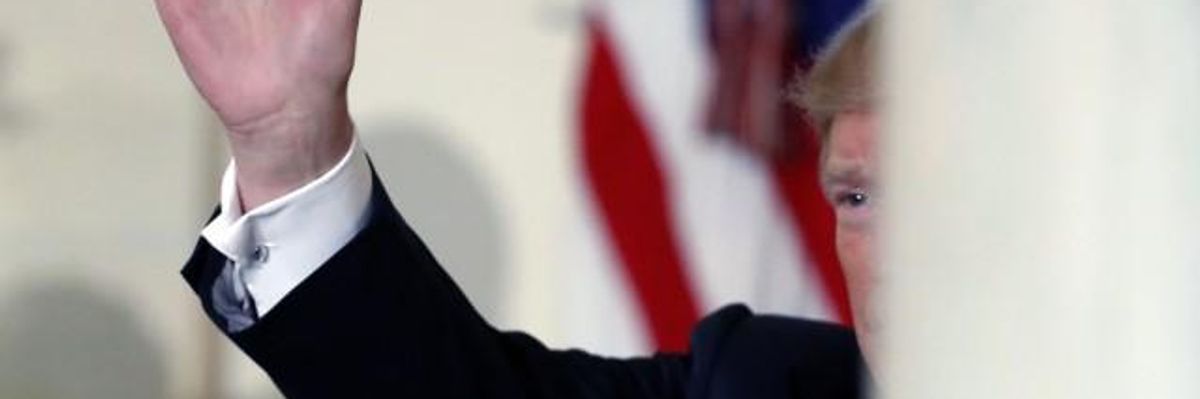
President Donald Trump waves as he leaves after speaking about tax reform in the Grand Foyer of the White House. (Photo: AP Photo/Alex Brandon)
With the economy producing rising growth rates and falling unemployment, will Donald Trump and the Republican tax bill be able to take political credit for the boom of 2017-2018? Maybe not.
For starters, the boom was already roaring along in 2015 and 2016, before Trump took office, as the post-recession recovery finally kicked in. The year 2015 showed the strongest GDP growth in more than a decade, and 2016 was not far behind.
Unemployment was already down to 4.7 percent when Trump took office and its further drop to 4.1 is entirely the result of policies established before Trump, under one Barack Obama.
Even with these low rates of joblessness, profound structural changes in the labor market fail to translate low unemployment into significant gains in earnings or career prospects. The rise of gig employment, the bashing of trade unions, the elimination of reliable career paths--all of this is intensifying. A slight uptick in median wages doesn't change that.
The job market is still unreliable for most working people, and most still experience it as lousy. The ratio of employed people to population is unchanged this year, at just 60.1 percent.
The changes in the tax code will do nothing to alter that. And the tax bill will only widen inequality of after-tax income.
Moreover, the huge corporate tax breaks are not likely to generate jobs, because corporations in recent years have used their outsized profits more for stock buybacks (to pump up share values) than for new domestic investment. If anything, the tax bill will only exacerbate that imbalance, as corporations literally have more after-tax profits than they know what to do with.
This is well into bubble territory, and the last bubble did not end well.
With its favoritism for corporations, the bill will likely prolong and intensify what many analysts consider a stock market already dangerously overvalued. The Dow Jones Industrial Average is up 24.74 percent percent this year, after rising 13.42 last year. This is well into bubble territory, and the last bubble did not end well.
What might prick the bubble? Consider the Federal Reserve.
Last week, the Fed responded to the pending success of the tax bill by raising interest rates. Most Fed economists and members of the board of governors consider the economy to be at full employment. The Fed's well-advertised plan is to keep raising interest rates.
At some point, investors decide that they've had a great ride, and sell out before the inevitable "correction." Given the famous herd-instinct of Wall Street, the sell mentality becomes a self-fulfilling prophesy. Or some unanticipated crisis sets off a wave of selling.
And while the increase of the federal deficit by $1.5 trillion over a decade does create some fiscal stimulus (other things being equal), other things in fact are not equal. The more the deficit guns growth, the more the Fed raises rates. And the more the Fed raises rates, the more investors shift from stocks to bonds.
So, while the Trump boom looks pretty good now, my bet is that it won't look so great by November 2018.
Imagine what else might have been accomplished by a $1.5 trillion increase in the federal deficit. We could have invested in a massive public infrastructure program. That would have created more good jobs directly, and as public jobs they would have been better defended against the Fed hiking rates. But that sort of stimulus program requires Democrats.
One more detail: The Republicans, partly by accident and partly as payback to punish blue state voters, actually backed into good tax policy, in one respect. That is the cap on property tax deductions.
Housing--especially housing for the well-to-do--is over-subsidized by multiple tax breaks. All those tax breaks bid up the price of housing, creating a windfall for those who already own homes but a punishment for those trying to buy in.
Republicans, looking for some way to make up the massive revenue losses from their tax cuts, searched for loopholes to close. They ended up capping the deductibility of both state sales taxes and local property taxes, at a total of $10,000.
This hits mainly the upper middle class and mainly homeowners in high tax states.
About two-thirds of Americans take the standard deduction, which is to be increased in the tax bill. But if your family makes, say, $150,000 a year and pays property and sales taxes totaling $20,000, you will now be paying tax on $10,000 more income than last year because of the cap's limit on what you can deduct.
According to Zillow, it makes sense under current law for about 44 percent of homeowners to itemize their deductions. Under the new law, that will drop to 14 percent.
The result will be to damp down price pressures on housing in high-cost areas, since the shift makes investment in a house slightly less valuable. The double taxation in denying deductions for state and local taxes paid is a travesty, and it would have been even better policy to further cut the deduction for mortgage interest. It would have been still better policy to take the proceeds from capping the several tax breaks for expensive homes, and put them into creation of affordable housing. But that also requires Democrats.
The Republicans, as noted, backed into this cap. Imagine the Republican outcry if Democrats had proposed it. And of course there were no hearings, no expert testimony, no weighing of alternatives.
But capping the property tax deduction is good housing policy. As the old saying goes, even a stopped clock is right twice a day.
This country and this world are at a monumental crossroads. US voters have an opportunity to beat back the forces of fascism and confront the billionaires who are rigging the economy, our media system, and our democracy, making it increasingly impossible for ordinary people to get by. We’re not just talking about the election. We’re talking about what must be done once these fascist elements are vanquished from power. We need a bolder set of solutions than what either major party has so far been willing to offer and a working-class movement ready to fight like hell for it. Trump didn't emerge from nowhere. The conditions that fueled MAGA authoritarianism were created by decades of radical neoliberal economic policies and a corrupt political system dominated by corporate interests. They slashed taxes on the super-rich, promising that the benefits would trickle down. They said giveaways to the corporate titans would make life more affordable for the rest of us. It was all bullshit. And when a bitter, betrayed populace searches for someone to blame, right-wing demagogues have little trouble finding scapegoats. People know when they're being lied to, but you won't hear any of this from the corporate media. Only independent journalism—powered and funded by people who believe in building a better world—can deliver truly trustworthy daily news. If you share our vision, please contribute whatever you can to sustain our work. |
With the economy producing rising growth rates and falling unemployment, will Donald Trump and the Republican tax bill be able to take political credit for the boom of 2017-2018? Maybe not.
For starters, the boom was already roaring along in 2015 and 2016, before Trump took office, as the post-recession recovery finally kicked in. The year 2015 showed the strongest GDP growth in more than a decade, and 2016 was not far behind.
Unemployment was already down to 4.7 percent when Trump took office and its further drop to 4.1 is entirely the result of policies established before Trump, under one Barack Obama.
Even with these low rates of joblessness, profound structural changes in the labor market fail to translate low unemployment into significant gains in earnings or career prospects. The rise of gig employment, the bashing of trade unions, the elimination of reliable career paths--all of this is intensifying. A slight uptick in median wages doesn't change that.
The job market is still unreliable for most working people, and most still experience it as lousy. The ratio of employed people to population is unchanged this year, at just 60.1 percent.
The changes in the tax code will do nothing to alter that. And the tax bill will only widen inequality of after-tax income.
Moreover, the huge corporate tax breaks are not likely to generate jobs, because corporations in recent years have used their outsized profits more for stock buybacks (to pump up share values) than for new domestic investment. If anything, the tax bill will only exacerbate that imbalance, as corporations literally have more after-tax profits than they know what to do with.
This is well into bubble territory, and the last bubble did not end well.
With its favoritism for corporations, the bill will likely prolong and intensify what many analysts consider a stock market already dangerously overvalued. The Dow Jones Industrial Average is up 24.74 percent percent this year, after rising 13.42 last year. This is well into bubble territory, and the last bubble did not end well.
What might prick the bubble? Consider the Federal Reserve.
Last week, the Fed responded to the pending success of the tax bill by raising interest rates. Most Fed economists and members of the board of governors consider the economy to be at full employment. The Fed's well-advertised plan is to keep raising interest rates.
At some point, investors decide that they've had a great ride, and sell out before the inevitable "correction." Given the famous herd-instinct of Wall Street, the sell mentality becomes a self-fulfilling prophesy. Or some unanticipated crisis sets off a wave of selling.
And while the increase of the federal deficit by $1.5 trillion over a decade does create some fiscal stimulus (other things being equal), other things in fact are not equal. The more the deficit guns growth, the more the Fed raises rates. And the more the Fed raises rates, the more investors shift from stocks to bonds.
So, while the Trump boom looks pretty good now, my bet is that it won't look so great by November 2018.
Imagine what else might have been accomplished by a $1.5 trillion increase in the federal deficit. We could have invested in a massive public infrastructure program. That would have created more good jobs directly, and as public jobs they would have been better defended against the Fed hiking rates. But that sort of stimulus program requires Democrats.
One more detail: The Republicans, partly by accident and partly as payback to punish blue state voters, actually backed into good tax policy, in one respect. That is the cap on property tax deductions.
Housing--especially housing for the well-to-do--is over-subsidized by multiple tax breaks. All those tax breaks bid up the price of housing, creating a windfall for those who already own homes but a punishment for those trying to buy in.
Republicans, looking for some way to make up the massive revenue losses from their tax cuts, searched for loopholes to close. They ended up capping the deductibility of both state sales taxes and local property taxes, at a total of $10,000.
This hits mainly the upper middle class and mainly homeowners in high tax states.
About two-thirds of Americans take the standard deduction, which is to be increased in the tax bill. But if your family makes, say, $150,000 a year and pays property and sales taxes totaling $20,000, you will now be paying tax on $10,000 more income than last year because of the cap's limit on what you can deduct.
According to Zillow, it makes sense under current law for about 44 percent of homeowners to itemize their deductions. Under the new law, that will drop to 14 percent.
The result will be to damp down price pressures on housing in high-cost areas, since the shift makes investment in a house slightly less valuable. The double taxation in denying deductions for state and local taxes paid is a travesty, and it would have been even better policy to further cut the deduction for mortgage interest. It would have been still better policy to take the proceeds from capping the several tax breaks for expensive homes, and put them into creation of affordable housing. But that also requires Democrats.
The Republicans, as noted, backed into this cap. Imagine the Republican outcry if Democrats had proposed it. And of course there were no hearings, no expert testimony, no weighing of alternatives.
But capping the property tax deduction is good housing policy. As the old saying goes, even a stopped clock is right twice a day.
With the economy producing rising growth rates and falling unemployment, will Donald Trump and the Republican tax bill be able to take political credit for the boom of 2017-2018? Maybe not.
For starters, the boom was already roaring along in 2015 and 2016, before Trump took office, as the post-recession recovery finally kicked in. The year 2015 showed the strongest GDP growth in more than a decade, and 2016 was not far behind.
Unemployment was already down to 4.7 percent when Trump took office and its further drop to 4.1 is entirely the result of policies established before Trump, under one Barack Obama.
Even with these low rates of joblessness, profound structural changes in the labor market fail to translate low unemployment into significant gains in earnings or career prospects. The rise of gig employment, the bashing of trade unions, the elimination of reliable career paths--all of this is intensifying. A slight uptick in median wages doesn't change that.
The job market is still unreliable for most working people, and most still experience it as lousy. The ratio of employed people to population is unchanged this year, at just 60.1 percent.
The changes in the tax code will do nothing to alter that. And the tax bill will only widen inequality of after-tax income.
Moreover, the huge corporate tax breaks are not likely to generate jobs, because corporations in recent years have used their outsized profits more for stock buybacks (to pump up share values) than for new domestic investment. If anything, the tax bill will only exacerbate that imbalance, as corporations literally have more after-tax profits than they know what to do with.
This is well into bubble territory, and the last bubble did not end well.
With its favoritism for corporations, the bill will likely prolong and intensify what many analysts consider a stock market already dangerously overvalued. The Dow Jones Industrial Average is up 24.74 percent percent this year, after rising 13.42 last year. This is well into bubble territory, and the last bubble did not end well.
What might prick the bubble? Consider the Federal Reserve.
Last week, the Fed responded to the pending success of the tax bill by raising interest rates. Most Fed economists and members of the board of governors consider the economy to be at full employment. The Fed's well-advertised plan is to keep raising interest rates.
At some point, investors decide that they've had a great ride, and sell out before the inevitable "correction." Given the famous herd-instinct of Wall Street, the sell mentality becomes a self-fulfilling prophesy. Or some unanticipated crisis sets off a wave of selling.
And while the increase of the federal deficit by $1.5 trillion over a decade does create some fiscal stimulus (other things being equal), other things in fact are not equal. The more the deficit guns growth, the more the Fed raises rates. And the more the Fed raises rates, the more investors shift from stocks to bonds.
So, while the Trump boom looks pretty good now, my bet is that it won't look so great by November 2018.
Imagine what else might have been accomplished by a $1.5 trillion increase in the federal deficit. We could have invested in a massive public infrastructure program. That would have created more good jobs directly, and as public jobs they would have been better defended against the Fed hiking rates. But that sort of stimulus program requires Democrats.
One more detail: The Republicans, partly by accident and partly as payback to punish blue state voters, actually backed into good tax policy, in one respect. That is the cap on property tax deductions.
Housing--especially housing for the well-to-do--is over-subsidized by multiple tax breaks. All those tax breaks bid up the price of housing, creating a windfall for those who already own homes but a punishment for those trying to buy in.
Republicans, looking for some way to make up the massive revenue losses from their tax cuts, searched for loopholes to close. They ended up capping the deductibility of both state sales taxes and local property taxes, at a total of $10,000.
This hits mainly the upper middle class and mainly homeowners in high tax states.
About two-thirds of Americans take the standard deduction, which is to be increased in the tax bill. But if your family makes, say, $150,000 a year and pays property and sales taxes totaling $20,000, you will now be paying tax on $10,000 more income than last year because of the cap's limit on what you can deduct.
According to Zillow, it makes sense under current law for about 44 percent of homeowners to itemize their deductions. Under the new law, that will drop to 14 percent.
The result will be to damp down price pressures on housing in high-cost areas, since the shift makes investment in a house slightly less valuable. The double taxation in denying deductions for state and local taxes paid is a travesty, and it would have been even better policy to further cut the deduction for mortgage interest. It would have been still better policy to take the proceeds from capping the several tax breaks for expensive homes, and put them into creation of affordable housing. But that also requires Democrats.
The Republicans, as noted, backed into this cap. Imagine the Republican outcry if Democrats had proposed it. And of course there were no hearings, no expert testimony, no weighing of alternatives.
But capping the property tax deduction is good housing policy. As the old saying goes, even a stopped clock is right twice a day.