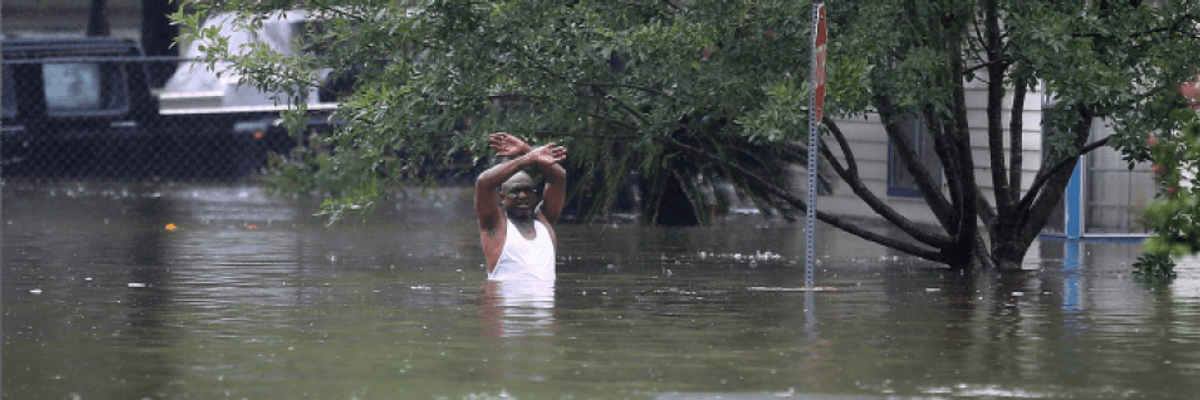
"Many of the same insurers who underwrite construction in the hurricane alleys of the Florida also underwrite oil and coal companies, as well as pharmaceutical giants and agribusiness corporations -- some of the world's biggest sources of greenhouse gases." (Photo by Joe Raedle/Getty Images)
Don't Expect the Insurance Industry To Protect You From Climate Change
Insurance companies understand how to make handsome profits from large-scale disasters.
Banks and insurance experts are reporting that, with 2 1/2 months to go, the 2017 Atlantic hurricane season is already one of the most expensive to date for the insurance industry.
Here's the weird part: Insurance companies are quietly happy about this. About the time that Hurricane Irma was making landfall in Florida, the chief executive of Lloyd's of London, Inga Beale, told the Times of London that the recent spate of storms would allow insurers to raise premiums. "Almost in a perverse way," Beale said, the hurricanes would "benefit the sector."
Perverse indeed. Insurance companies have figured out how to make a handsome profit from large-scale disasters. Raising premiums isn't the only way they do it. They also shed unprofitable neighborhoods and policyholders, leaving public treasuries to fill the void.
In the wake of Harvey and Irma, insurance providers, including the government-administered National Flood Insurance Program, are sure to spend vast sums to help restock coastlines with mansions, yacht-filled harbors and low-lying subdivisions, restaurants and casinos. Much of what gets rebuilt will get re-insured -- at higher rates -- so that it can be ransacked by extreme weather once again.
"As long as it's profitable, insurance companies will continue to build castles in the sand and suburbs in floodplains."
Insurers will also do the dirty work politicians aren't willing to do: They will help to push some people -- poor people who can't pay big insurance bills, namely -- out of areas deemed too dangerous to live in.
They do all this not because they are in the business of making people safe, but because they are in the business of managing risk and making a profit. This has long been the case, of course. But as climate change wreaks more acute havoc, the industry is looking for ways to profit from the increasing damage rather than protect policyholders from it.
In the decade I spent as a journalist in New Orleans, covering Hurricane Katrina, its fraught aftermath and the rebuilding effort, I watched the poorest urban neighborhoods and fishing towns get red-lined.
In the Lower 9th Ward, the grass grew long as snakes moved into lots where families once barbecued. In Louisiana's marshlands, rugged fishermen relayed stories of friends who had committed suicide after losing everything. I will never forget the day I happened across Grand Bayou, the last Native American fishing village in south Louisiana reachable only by boat. Thirty months after Katrina, nobody there had been able to rebuild their demolished homes.
By contrast, just over the horizon of golden marsh grass, a hamlet of sport fishermen and retirees had already bounced back. This community, named Happy Jack, was made up mostly of weekend warriors. It was jammed with insurable stuff: shaded docks, high-end boats, automatic boat lifts, jet skis. I counted how many of the waterfront homes were either rebuilt or nearly completed: 83 out of 94.
These communities are what the insurance industry wants. They are less risky to insure simply because the people there can pay ever-higher premiums. Happy Jacks keep insurers' balance sheets in the black.
Insurance providers have figured out how to profit off disasters even when they're not paying out claims. As investigative reporters at NPR and Frontline revealed, private insurers made hundreds of millions after Sandy simply by administering claims for the National Flood Insurance Program.
There is at least one area where the insurance industry has started taking climate change seriously -- risk modeling. It has no choice: Weather-related disasters have tripled since the 1980s, and annual average insurance losses have increased from $10 billion to about $50 billion over the last decade. Insurers are rightfully worried that, in the long term, climate change could devastate their industry.
As part of the grand enterprise of managing risk, the European insurance titans -- Lloyd's, Swiss Re, Munich Re -- are investing heavily in research so that they can more precisely predict what the toll of climate change will be. A growing number of American firms are also incorporating warming temperatures into their business models, according to industry surveys.
Some insurance firms are devising schemes to encourage individuals, cities and even countries to get their heads out of the sand, rewarding policyholders who build higher and safer structures, reduce carbon emissions or use solar panels with lower rates.
But for the most part, the industry's efforts to understand climate change are done in service of a limited goal: keeping shareholders happy. This is especially true in the U.S., where big insurance firms are also heavily involved in the fossil fuel industry. Many of the same insurers who underwrite construction in the hurricane alleys of the Florida also underwrite oil and coal companies, as well as pharmaceutical giants and agribusiness corporations -- some of the world's biggest sources of greenhouse gases.
So although insurance companies are quietly calculating the considerable risks posed by global warming, don't expect them to declare our way of life unsustainable. They aren't going to force paying policyholders to change their behavior in any meaningful way, nor will they urge Houston or New Orleans to take the drastic measures needed in order to prevent another flood.
As long as it's profitable, insurance companies will continue to build castles in the sand and suburbs in floodplains. It's up to Americans to face the facts about climate change, or we will lose much more than affordable insurance and predictable weather patterns.
An Urgent Message From Our Co-Founder
Dear Common Dreams reader, It’s been nearly 30 years since I co-founded Common Dreams with my late wife, Lina Newhouser. We had the radical notion that journalism should serve the public good, not corporate profits. It was clear to us from the outset what it would take to build such a project. No paid advertisements. No corporate sponsors. No millionaire publisher telling us what to think or do. Many people said we wouldn't last a year, but we proved those doubters wrong. Together with a tremendous team of journalists and dedicated staff, we built an independent media outlet free from the constraints of profits and corporate control. Our mission has always been simple: To inform. To inspire. To ignite change for the common good. Building Common Dreams was not easy. Our survival was never guaranteed. When you take on the most powerful forces—Wall Street greed, fossil fuel industry destruction, Big Tech lobbyists, and uber-rich oligarchs who have spent billions upon billions rigging the economy and democracy in their favor—the only bulwark you have is supporters who believe in your work. But here’s the urgent message from me today. It's never been this bad out there. And it's never been this hard to keep us going. At the very moment Common Dreams is most needed, the threats we face are intensifying. We need your support now more than ever. We don't accept corporate advertising and never will. We don't have a paywall because we don't think people should be blocked from critical news based on their ability to pay. Everything we do is funded by the donations of readers like you. When everyone does the little they can afford, we are strong. But if that support retreats or dries up, so do we. Will you donate now to make sure Common Dreams not only survives but thrives? —Craig Brown, Co-founder |
Banks and insurance experts are reporting that, with 2 1/2 months to go, the 2017 Atlantic hurricane season is already one of the most expensive to date for the insurance industry.
Here's the weird part: Insurance companies are quietly happy about this. About the time that Hurricane Irma was making landfall in Florida, the chief executive of Lloyd's of London, Inga Beale, told the Times of London that the recent spate of storms would allow insurers to raise premiums. "Almost in a perverse way," Beale said, the hurricanes would "benefit the sector."
Perverse indeed. Insurance companies have figured out how to make a handsome profit from large-scale disasters. Raising premiums isn't the only way they do it. They also shed unprofitable neighborhoods and policyholders, leaving public treasuries to fill the void.
In the wake of Harvey and Irma, insurance providers, including the government-administered National Flood Insurance Program, are sure to spend vast sums to help restock coastlines with mansions, yacht-filled harbors and low-lying subdivisions, restaurants and casinos. Much of what gets rebuilt will get re-insured -- at higher rates -- so that it can be ransacked by extreme weather once again.
"As long as it's profitable, insurance companies will continue to build castles in the sand and suburbs in floodplains."
Insurers will also do the dirty work politicians aren't willing to do: They will help to push some people -- poor people who can't pay big insurance bills, namely -- out of areas deemed too dangerous to live in.
They do all this not because they are in the business of making people safe, but because they are in the business of managing risk and making a profit. This has long been the case, of course. But as climate change wreaks more acute havoc, the industry is looking for ways to profit from the increasing damage rather than protect policyholders from it.
In the decade I spent as a journalist in New Orleans, covering Hurricane Katrina, its fraught aftermath and the rebuilding effort, I watched the poorest urban neighborhoods and fishing towns get red-lined.
In the Lower 9th Ward, the grass grew long as snakes moved into lots where families once barbecued. In Louisiana's marshlands, rugged fishermen relayed stories of friends who had committed suicide after losing everything. I will never forget the day I happened across Grand Bayou, the last Native American fishing village in south Louisiana reachable only by boat. Thirty months after Katrina, nobody there had been able to rebuild their demolished homes.
By contrast, just over the horizon of golden marsh grass, a hamlet of sport fishermen and retirees had already bounced back. This community, named Happy Jack, was made up mostly of weekend warriors. It was jammed with insurable stuff: shaded docks, high-end boats, automatic boat lifts, jet skis. I counted how many of the waterfront homes were either rebuilt or nearly completed: 83 out of 94.
These communities are what the insurance industry wants. They are less risky to insure simply because the people there can pay ever-higher premiums. Happy Jacks keep insurers' balance sheets in the black.
Insurance providers have figured out how to profit off disasters even when they're not paying out claims. As investigative reporters at NPR and Frontline revealed, private insurers made hundreds of millions after Sandy simply by administering claims for the National Flood Insurance Program.
There is at least one area where the insurance industry has started taking climate change seriously -- risk modeling. It has no choice: Weather-related disasters have tripled since the 1980s, and annual average insurance losses have increased from $10 billion to about $50 billion over the last decade. Insurers are rightfully worried that, in the long term, climate change could devastate their industry.
As part of the grand enterprise of managing risk, the European insurance titans -- Lloyd's, Swiss Re, Munich Re -- are investing heavily in research so that they can more precisely predict what the toll of climate change will be. A growing number of American firms are also incorporating warming temperatures into their business models, according to industry surveys.
Some insurance firms are devising schemes to encourage individuals, cities and even countries to get their heads out of the sand, rewarding policyholders who build higher and safer structures, reduce carbon emissions or use solar panels with lower rates.
But for the most part, the industry's efforts to understand climate change are done in service of a limited goal: keeping shareholders happy. This is especially true in the U.S., where big insurance firms are also heavily involved in the fossil fuel industry. Many of the same insurers who underwrite construction in the hurricane alleys of the Florida also underwrite oil and coal companies, as well as pharmaceutical giants and agribusiness corporations -- some of the world's biggest sources of greenhouse gases.
So although insurance companies are quietly calculating the considerable risks posed by global warming, don't expect them to declare our way of life unsustainable. They aren't going to force paying policyholders to change their behavior in any meaningful way, nor will they urge Houston or New Orleans to take the drastic measures needed in order to prevent another flood.
As long as it's profitable, insurance companies will continue to build castles in the sand and suburbs in floodplains. It's up to Americans to face the facts about climate change, or we will lose much more than affordable insurance and predictable weather patterns.
Banks and insurance experts are reporting that, with 2 1/2 months to go, the 2017 Atlantic hurricane season is already one of the most expensive to date for the insurance industry.
Here's the weird part: Insurance companies are quietly happy about this. About the time that Hurricane Irma was making landfall in Florida, the chief executive of Lloyd's of London, Inga Beale, told the Times of London that the recent spate of storms would allow insurers to raise premiums. "Almost in a perverse way," Beale said, the hurricanes would "benefit the sector."
Perverse indeed. Insurance companies have figured out how to make a handsome profit from large-scale disasters. Raising premiums isn't the only way they do it. They also shed unprofitable neighborhoods and policyholders, leaving public treasuries to fill the void.
In the wake of Harvey and Irma, insurance providers, including the government-administered National Flood Insurance Program, are sure to spend vast sums to help restock coastlines with mansions, yacht-filled harbors and low-lying subdivisions, restaurants and casinos. Much of what gets rebuilt will get re-insured -- at higher rates -- so that it can be ransacked by extreme weather once again.
"As long as it's profitable, insurance companies will continue to build castles in the sand and suburbs in floodplains."
Insurers will also do the dirty work politicians aren't willing to do: They will help to push some people -- poor people who can't pay big insurance bills, namely -- out of areas deemed too dangerous to live in.
They do all this not because they are in the business of making people safe, but because they are in the business of managing risk and making a profit. This has long been the case, of course. But as climate change wreaks more acute havoc, the industry is looking for ways to profit from the increasing damage rather than protect policyholders from it.
In the decade I spent as a journalist in New Orleans, covering Hurricane Katrina, its fraught aftermath and the rebuilding effort, I watched the poorest urban neighborhoods and fishing towns get red-lined.
In the Lower 9th Ward, the grass grew long as snakes moved into lots where families once barbecued. In Louisiana's marshlands, rugged fishermen relayed stories of friends who had committed suicide after losing everything. I will never forget the day I happened across Grand Bayou, the last Native American fishing village in south Louisiana reachable only by boat. Thirty months after Katrina, nobody there had been able to rebuild their demolished homes.
By contrast, just over the horizon of golden marsh grass, a hamlet of sport fishermen and retirees had already bounced back. This community, named Happy Jack, was made up mostly of weekend warriors. It was jammed with insurable stuff: shaded docks, high-end boats, automatic boat lifts, jet skis. I counted how many of the waterfront homes were either rebuilt or nearly completed: 83 out of 94.
These communities are what the insurance industry wants. They are less risky to insure simply because the people there can pay ever-higher premiums. Happy Jacks keep insurers' balance sheets in the black.
Insurance providers have figured out how to profit off disasters even when they're not paying out claims. As investigative reporters at NPR and Frontline revealed, private insurers made hundreds of millions after Sandy simply by administering claims for the National Flood Insurance Program.
There is at least one area where the insurance industry has started taking climate change seriously -- risk modeling. It has no choice: Weather-related disasters have tripled since the 1980s, and annual average insurance losses have increased from $10 billion to about $50 billion over the last decade. Insurers are rightfully worried that, in the long term, climate change could devastate their industry.
As part of the grand enterprise of managing risk, the European insurance titans -- Lloyd's, Swiss Re, Munich Re -- are investing heavily in research so that they can more precisely predict what the toll of climate change will be. A growing number of American firms are also incorporating warming temperatures into their business models, according to industry surveys.
Some insurance firms are devising schemes to encourage individuals, cities and even countries to get their heads out of the sand, rewarding policyholders who build higher and safer structures, reduce carbon emissions or use solar panels with lower rates.
But for the most part, the industry's efforts to understand climate change are done in service of a limited goal: keeping shareholders happy. This is especially true in the U.S., where big insurance firms are also heavily involved in the fossil fuel industry. Many of the same insurers who underwrite construction in the hurricane alleys of the Florida also underwrite oil and coal companies, as well as pharmaceutical giants and agribusiness corporations -- some of the world's biggest sources of greenhouse gases.
So although insurance companies are quietly calculating the considerable risks posed by global warming, don't expect them to declare our way of life unsustainable. They aren't going to force paying policyholders to change their behavior in any meaningful way, nor will they urge Houston or New Orleans to take the drastic measures needed in order to prevent another flood.
As long as it's profitable, insurance companies will continue to build castles in the sand and suburbs in floodplains. It's up to Americans to face the facts about climate change, or we will lose much more than affordable insurance and predictable weather patterns.