Sen. Elizabeth Warren, D-Mass., says that the problem of "too-big-to-fail" financial institutions has only gotten worse in the years since Congress passed financial reform legislation.
Sen. Elizabeth Warren, D-Mass., says that the problem of "too-big-to-fail" financial institutions has only gotten worse in the years since Congress passed financial reform legislation. That's why she is calling on activists to step up the pressure on Congress to pass legislation that would erect a wall between retail banking activities and the kind of high-risk financial bets that contributed to the 2008 financial crisis.
"Today the four biggest banks are 30 percent larger than they were five years ago. And the five largest banks now hold more than half of the total banking assets in the country. Who would have thought five years ago, after we witnessed first-hand the dangers of an overly concentrated financial system, that the 'too big to fail' problem would only have gotten worse?" Warren said Tuesday afternoon during a conference sponsored by Americans for Financial Reform and the Roosevelt Institution. "It's been three years since Dodd-Frank has passed, and the biggest banks are bigger than ever, the risk to the system has grown, and the market disruption has continued."
Warren has thrown her support behind the "21st Century Glass-Steagall Act," legislation co-sponsored by Sens. Maria Cantwell, D-Wash., and John McCain, R-Ariz.
"[The 21st Century Glass-Steagall Act] would force some of the biggest financial institutions to break apart, and eliminate their ability to rely on federal insured deposits as a backstop for their high risk activities," Warren said.
"A new Glass-Steagall act would attack both "too big" and 'to fail,' It would reduce 'too big' by dismantling the behemoths, so that big banks would still be big--but not too big to fail or, for that matter, too big to manage, too big to regulate, too big for trial, or too big for jail."
The conference at which Warren spoke featured the release of a joint Americans for Financial Reform-Roosevelt Institution report, "An Unfinished Mission: Making Wall Street Work for Us." The report looks at the regulations instituted by the Dodd-Frank Wall Street Reform and Consumer Protection Act, its successes, failures, and what must happen in order for the law to be a success in preventing another economic collapse. Each chapter is written by a leading expert on financial reform and the provisions of Dodd-Frank, and details new problems that have either arisen since the bill's passage or have come into clearer view that can be addressed either through amendments to current law or new regulations.
"A recent report from the Federal Reserve of Dallas estimated that the financial crisis cost us upwards of $14 trillion," said Warren, "that's trillion with a T. $120,000 for every American household, more than two years worth of income for the average family.
"Billions of dollars in retirement savings disappeared, and millions of people lost their job and sense of financial security, entire communities were devastated. A new Census Bureau study has shows that homeownership rates for families with young children has declined by 15 percent."
The Glass-Steagall Act was a Depression-era law that prevented banks covered by federal deposit insurance from using their assets on high-risk speculative trading. Wall Street lobbyists worked to put cracks in the Glass-Steagall wall, and finally tore it down completely in 1999, unleashing the wave of casino-style financial activity that just nine years later led the biggest banks to need a federal taxpayer bailout.
"Sure, lobbyists will say that the sky will fall if they can't use deposits and checking accounts to fund their high risk activities, but they said that in the 1930s as well, and they were wrong then, and they are wrong now," Warren said. "The Glass-Steagall Act will restore the stability of the system that began to disappear at the end of the 1980s and 1990s."
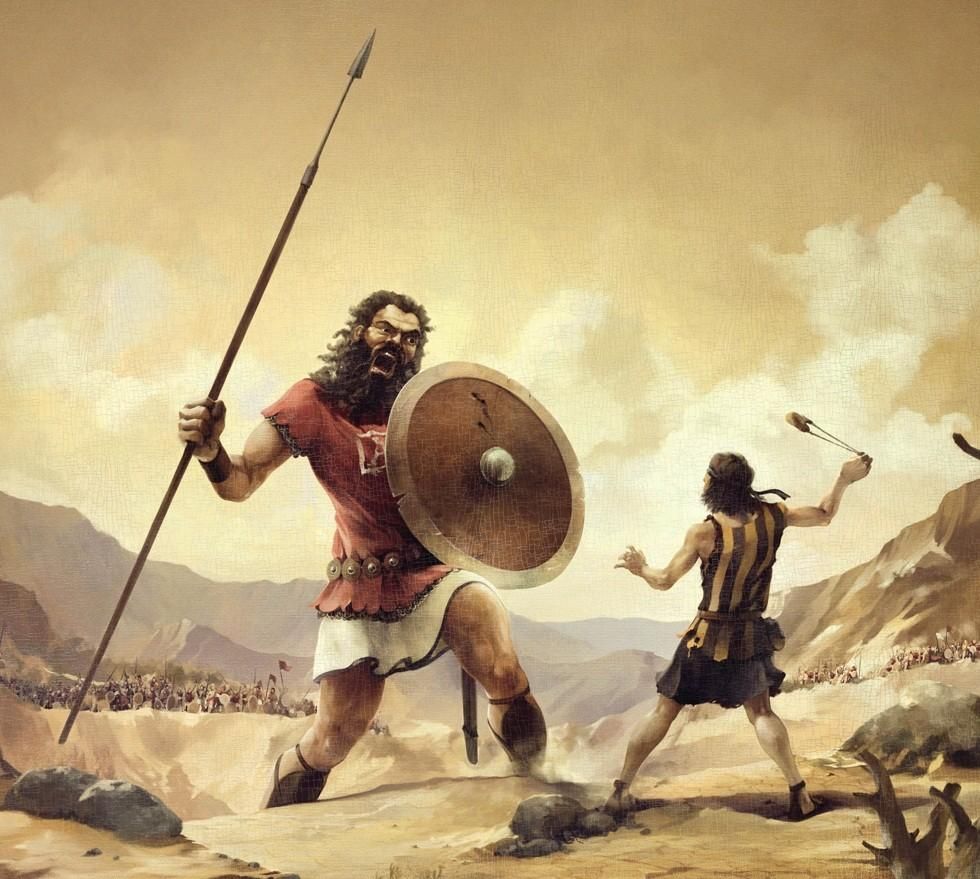
Warren acknowledged the potential difficulties of reinstating Glass-Steagall; the vote that demolished the remaining remnants of the law passed Congress by overwhelming bipartisan margins and was signed by President Clinton. But she recalled other financial reform battles over proposals that were declared "dead on arrival" when they first reached Congress. "David beat Goliath with the establishment of the CFPB (Consumer Financial Protection Bureau), and just a few months ago with the confirmation of Richard Cordray (as CFPB director). David beat Goliath with the passage of Dodd-Frank. We did that together. I am confident that David can beat Goliath again on too big to fail. We just have to pick up the slingshot."
Sen. Elizabeth Warren, D-Mass., says that the problem of "too-big-to-fail" financial institutions has only gotten worse in the years since Congress passed financial reform legislation. That's why she is calling on activists to step up the pressure on Congress to pass legislation that would erect a wall between retail banking activities and the kind of high-risk financial bets that contributed to the 2008 financial crisis.
"Today the four biggest banks are 30 percent larger than they were five years ago. And the five largest banks now hold more than half of the total banking assets in the country. Who would have thought five years ago, after we witnessed first-hand the dangers of an overly concentrated financial system, that the 'too big to fail' problem would only have gotten worse?" Warren said Tuesday afternoon during a conference sponsored by Americans for Financial Reform and the Roosevelt Institution. "It's been three years since Dodd-Frank has passed, and the biggest banks are bigger than ever, the risk to the system has grown, and the market disruption has continued."
Warren has thrown her support behind the "21st Century Glass-Steagall Act," legislation co-sponsored by Sens. Maria Cantwell, D-Wash., and John McCain, R-Ariz.
"[The 21st Century Glass-Steagall Act] would force some of the biggest financial institutions to break apart, and eliminate their ability to rely on federal insured deposits as a backstop for their high risk activities," Warren said.
"A new Glass-Steagall act would attack both "too big" and 'to fail,' It would reduce 'too big' by dismantling the behemoths, so that big banks would still be big--but not too big to fail or, for that matter, too big to manage, too big to regulate, too big for trial, or too big for jail."
The conference at which Warren spoke featured the release of a joint Americans for Financial Reform-Roosevelt Institution report, "An Unfinished Mission: Making Wall Street Work for Us." The report looks at the regulations instituted by the Dodd-Frank Wall Street Reform and Consumer Protection Act, its successes, failures, and what must happen in order for the law to be a success in preventing another economic collapse. Each chapter is written by a leading expert on financial reform and the provisions of Dodd-Frank, and details new problems that have either arisen since the bill's passage or have come into clearer view that can be addressed either through amendments to current law or new regulations.
"A recent report from the Federal Reserve of Dallas estimated that the financial crisis cost us upwards of $14 trillion," said Warren, "that's trillion with a T. $120,000 for every American household, more than two years worth of income for the average family.
"Billions of dollars in retirement savings disappeared, and millions of people lost their job and sense of financial security, entire communities were devastated. A new Census Bureau study has shows that homeownership rates for families with young children has declined by 15 percent."
The Glass-Steagall Act was a Depression-era law that prevented banks covered by federal deposit insurance from using their assets on high-risk speculative trading. Wall Street lobbyists worked to put cracks in the Glass-Steagall wall, and finally tore it down completely in 1999, unleashing the wave of casino-style financial activity that just nine years later led the biggest banks to need a federal taxpayer bailout.
"Sure, lobbyists will say that the sky will fall if they can't use deposits and checking accounts to fund their high risk activities, but they said that in the 1930s as well, and they were wrong then, and they are wrong now," Warren said. "The Glass-Steagall Act will restore the stability of the system that began to disappear at the end of the 1980s and 1990s."
Warren acknowledged the potential difficulties of reinstating Glass-Steagall; the vote that demolished the remaining remnants of the law passed Congress by overwhelming bipartisan margins and was signed by President Clinton. But she recalled other financial reform battles over proposals that were declared "dead on arrival" when they first reached Congress. "David beat Goliath with the establishment of the CFPB (Consumer Financial Protection Bureau), and just a few months ago with the confirmation of Richard Cordray (as CFPB director). David beat Goliath with the passage of Dodd-Frank. We did that together. I am confident that David can beat Goliath again on too big to fail. We just have to pick up the slingshot."
Sen. Elizabeth Warren, D-Mass., says that the problem of "too-big-to-fail" financial institutions has only gotten worse in the years since Congress passed financial reform legislation. That's why she is calling on activists to step up the pressure on Congress to pass legislation that would erect a wall between retail banking activities and the kind of high-risk financial bets that contributed to the 2008 financial crisis.
"Today the four biggest banks are 30 percent larger than they were five years ago. And the five largest banks now hold more than half of the total banking assets in the country. Who would have thought five years ago, after we witnessed first-hand the dangers of an overly concentrated financial system, that the 'too big to fail' problem would only have gotten worse?" Warren said Tuesday afternoon during a conference sponsored by Americans for Financial Reform and the Roosevelt Institution. "It's been three years since Dodd-Frank has passed, and the biggest banks are bigger than ever, the risk to the system has grown, and the market disruption has continued."
Warren has thrown her support behind the "21st Century Glass-Steagall Act," legislation co-sponsored by Sens. Maria Cantwell, D-Wash., and John McCain, R-Ariz.
"[The 21st Century Glass-Steagall Act] would force some of the biggest financial institutions to break apart, and eliminate their ability to rely on federal insured deposits as a backstop for their high risk activities," Warren said.
"A new Glass-Steagall act would attack both "too big" and 'to fail,' It would reduce 'too big' by dismantling the behemoths, so that big banks would still be big--but not too big to fail or, for that matter, too big to manage, too big to regulate, too big for trial, or too big for jail."
The conference at which Warren spoke featured the release of a joint Americans for Financial Reform-Roosevelt Institution report, "An Unfinished Mission: Making Wall Street Work for Us." The report looks at the regulations instituted by the Dodd-Frank Wall Street Reform and Consumer Protection Act, its successes, failures, and what must happen in order for the law to be a success in preventing another economic collapse. Each chapter is written by a leading expert on financial reform and the provisions of Dodd-Frank, and details new problems that have either arisen since the bill's passage or have come into clearer view that can be addressed either through amendments to current law or new regulations.
"A recent report from the Federal Reserve of Dallas estimated that the financial crisis cost us upwards of $14 trillion," said Warren, "that's trillion with a T. $120,000 for every American household, more than two years worth of income for the average family.
"Billions of dollars in retirement savings disappeared, and millions of people lost their job and sense of financial security, entire communities were devastated. A new Census Bureau study has shows that homeownership rates for families with young children has declined by 15 percent."
The Glass-Steagall Act was a Depression-era law that prevented banks covered by federal deposit insurance from using their assets on high-risk speculative trading. Wall Street lobbyists worked to put cracks in the Glass-Steagall wall, and finally tore it down completely in 1999, unleashing the wave of casino-style financial activity that just nine years later led the biggest banks to need a federal taxpayer bailout.
"Sure, lobbyists will say that the sky will fall if they can't use deposits and checking accounts to fund their high risk activities, but they said that in the 1930s as well, and they were wrong then, and they are wrong now," Warren said. "The Glass-Steagall Act will restore the stability of the system that began to disappear at the end of the 1980s and 1990s."
Warren acknowledged the potential difficulties of reinstating Glass-Steagall; the vote that demolished the remaining remnants of the law passed Congress by overwhelming bipartisan margins and was signed by President Clinton. But she recalled other financial reform battles over proposals that were declared "dead on arrival" when they first reached Congress. "David beat Goliath with the establishment of the CFPB (Consumer Financial Protection Bureau), and just a few months ago with the confirmation of Richard Cordray (as CFPB director). David beat Goliath with the passage of Dodd-Frank. We did that together. I am confident that David can beat Goliath again on too big to fail. We just have to pick up the slingshot."