In the realm of prevarication, there are deceivers, fibbers, liars, politicians ... and Bank of America.
For weeks, this financial behemoth has been running a nationwide PR blitz, portraying itself as a loveable bunch of public-spirited bankers -- hoping that you and I have no memory of its two taxpayer bailouts, constant fee-gouging, illegal foreclosures on homeowners, firing of 36,000 employees, etc. Before you believe a word that these "truth adjusters" say, note that they've even been caught lying outright to BOA's shareholders, the owners of their very own bank!
Following the 2007-2008 Wall Street collapse, not only did the bank get a $15 billion bailout, its executives and federal regulators colluded to make the too-big-to-fail giant even bigger by flinging the foundering investment powerhouse Merrill Lynch into its maw. To win shareholder approval of this merger, the bank's top executives issued a rosy assessment of the takeover, promising that it would produce golden profits within only a year or so.
Recently, however, internal documents filed in a shareholder lawsuit revealed that the honchos, including the CEO, knew at the time of the December 2008 shareholder vote on the takeover that their predictions of early profits were "materially false" and that, indeed, swallowing Merrill would choke the owners with billions of dollars in losses.
Moreover, the merger deal struck by the geniuses at the top was so bad that they knew BOA would have to get a second federal bailout (this one turned out to be $20 billion) to stave off total collapse. Shareholders, who were told none of this, unwittingly voted to OK the merger.
Even the bank's top lawyer was kept in the dark about the false assessment presented to shareholders. When he learned of the big lie two days after the shareholder vote, he tried to talk to the chief financial officer about the need to admit the ruse. Instead, the next day, the lawyer was summarily fired and escorted from the bank without even being allowed to collect his personal belongings.
But, of course, such straightforward simplicity begged the obvious question: How can we expect Wall Street bankers to grab a chunk of this student education money if it's not routed directly through them?
There's a loveable bunch for you.
Forget the PR perfume that BOA's now spritzing around, Bank of America stinks to its core.
But it's hardly alone in reflexively doing things that most of us would recognize as wrong from our kindergarten days. Perhaps there's some sort of greed gene that prompts compulsive outbreaks of financial graspiness by giant bankers. How else to explain the chronic gouges, excesses and scandals that we're getting from this one, small subgroup of human beings?
Their latest reach is into the pockets of low- and modest-income college students who need federal student aid to help cope with today's ever-escalating education costs. For decades, this financial assistance has come in the form of simple checks written to the students by the aid program or administered directly by the schools. But, of course, such straightforward simplicity begged the obvious question: How can we expect Wall Street bankers to grab a chunk of this student education money if it's not routed directly through them?
Thus, from deep inside a particularly inventive banker somewhere, the greed gene shouted: "debit cards!" Rather than disbursing the aid by checks, banks get universities to issue debit cards for students to use to withdraw their aid funds electronically.
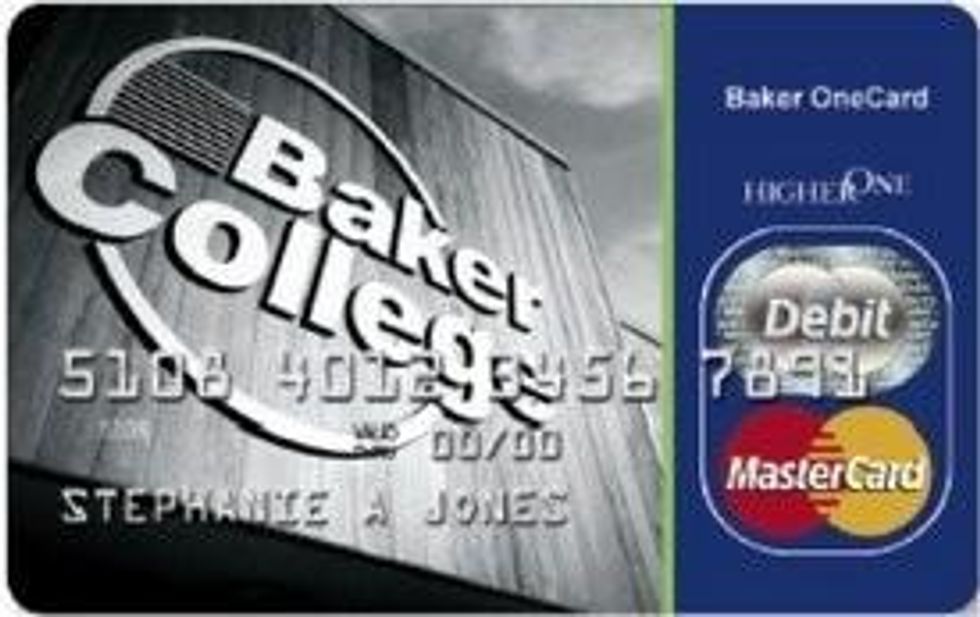
This third-party play was pitched to Congress as a nice, convenient service to help hard-pressed students. But wait -- these are bankers. They don't do nice -- at least, not for free. Sure enough, the campus debit cards, cheerily emblazoned with each school's logo, have hooked more than 9 million needy students into an insidious fee system, ranging from 50 cents per swipe of their cards to a $10 "inactivity fee" -- yes, a fee for not using their card frequently enough.
Some 900 campuses have signed card deals with such outfits as Wells Fargo and Higher One. These high-flying financiers grin from ear to ear as they line their pockets with tens of millions of dollars a year that they siphon from the public fund that was meant to extend America's educational opportunities to working-class and poor families. Banks get the goldmine, students get shaft.
For information about this rip-off -- and for action tips on preventing it -- get a copy of "The Campus Debit Card Trap" by the U.S. PIRG Education Fund.
In the realm of prevarication, there are deceivers, fibbers, liars, politicians ... and Bank of America.
For weeks, this financial behemoth has been running a nationwide PR blitz, portraying itself as a loveable bunch of public-spirited bankers -- hoping that you and I have no memory of its two taxpayer bailouts, constant fee-gouging, illegal foreclosures on homeowners, firing of 36,000 employees, etc. Before you believe a word that these "truth adjusters" say, note that they've even been caught lying outright to BOA's shareholders, the owners of their very own bank!
Following the 2007-2008 Wall Street collapse, not only did the bank get a $15 billion bailout, its executives and federal regulators colluded to make the too-big-to-fail giant even bigger by flinging the foundering investment powerhouse Merrill Lynch into its maw. To win shareholder approval of this merger, the bank's top executives issued a rosy assessment of the takeover, promising that it would produce golden profits within only a year or so.
Recently, however, internal documents filed in a shareholder lawsuit revealed that the honchos, including the CEO, knew at the time of the December 2008 shareholder vote on the takeover that their predictions of early profits were "materially false" and that, indeed, swallowing Merrill would choke the owners with billions of dollars in losses.
Moreover, the merger deal struck by the geniuses at the top was so bad that they knew BOA would have to get a second federal bailout (this one turned out to be $20 billion) to stave off total collapse. Shareholders, who were told none of this, unwittingly voted to OK the merger.
Even the bank's top lawyer was kept in the dark about the false assessment presented to shareholders. When he learned of the big lie two days after the shareholder vote, he tried to talk to the chief financial officer about the need to admit the ruse. Instead, the next day, the lawyer was summarily fired and escorted from the bank without even being allowed to collect his personal belongings.
But, of course, such straightforward simplicity begged the obvious question: How can we expect Wall Street bankers to grab a chunk of this student education money if it's not routed directly through them?
There's a loveable bunch for you.
Forget the PR perfume that BOA's now spritzing around, Bank of America stinks to its core.
But it's hardly alone in reflexively doing things that most of us would recognize as wrong from our kindergarten days. Perhaps there's some sort of greed gene that prompts compulsive outbreaks of financial graspiness by giant bankers. How else to explain the chronic gouges, excesses and scandals that we're getting from this one, small subgroup of human beings?
Their latest reach is into the pockets of low- and modest-income college students who need federal student aid to help cope with today's ever-escalating education costs. For decades, this financial assistance has come in the form of simple checks written to the students by the aid program or administered directly by the schools. But, of course, such straightforward simplicity begged the obvious question: How can we expect Wall Street bankers to grab a chunk of this student education money if it's not routed directly through them?
Thus, from deep inside a particularly inventive banker somewhere, the greed gene shouted: "debit cards!" Rather than disbursing the aid by checks, banks get universities to issue debit cards for students to use to withdraw their aid funds electronically.
This third-party play was pitched to Congress as a nice, convenient service to help hard-pressed students. But wait -- these are bankers. They don't do nice -- at least, not for free. Sure enough, the campus debit cards, cheerily emblazoned with each school's logo, have hooked more than 9 million needy students into an insidious fee system, ranging from 50 cents per swipe of their cards to a $10 "inactivity fee" -- yes, a fee for not using their card frequently enough.
Some 900 campuses have signed card deals with such outfits as Wells Fargo and Higher One. These high-flying financiers grin from ear to ear as they line their pockets with tens of millions of dollars a year that they siphon from the public fund that was meant to extend America's educational opportunities to working-class and poor families. Banks get the goldmine, students get shaft.
For information about this rip-off -- and for action tips on preventing it -- get a copy of "The Campus Debit Card Trap" by the U.S. PIRG Education Fund.