SUBSCRIBE TO OUR FREE NEWSLETTER
Daily news & progressive opinion—funded by the people, not the corporations—delivered straight to your inbox.
5
#000000
#FFFFFF
To donate by check, phone, or other method, see our More Ways to Give page.
So far, President Obama's election strategy can best be summed up as: "We're on the right track, my economic policies are working, we still have a long way to go, but stick with me and you'll be fine."
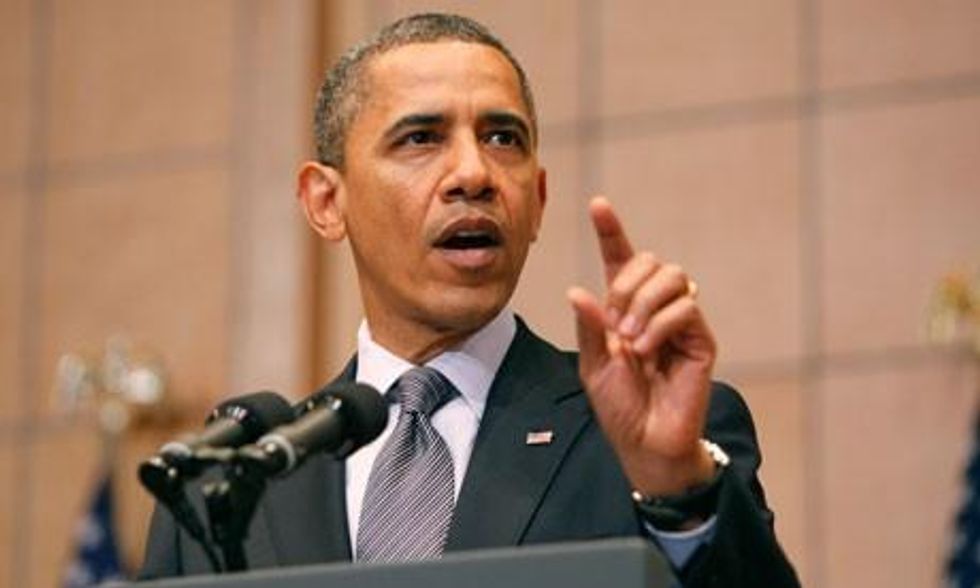
This won't be enough to win him the election. The US recovery is too anaemic, and the chance of an economic stall between now and election day far too high.
Even now, Mitt Romney's empty "I'll do it better" refrain is attracting as many voters as Obama's "we're on the right track." Each is gathering 46% of voter support, according to the latest New York Times/CBS News poll.
Only 33% of the American public thinks the economy is improving, while 39% say they're still falling behind financially - an 11-point increase from 2008. Nearly two thirds are concerned about paying for housing, and 23% of Americans with mortgages say they're underwater.
If the economy stalls, Romney's empty promise will look even better. And I'd put the odds of a stall at 50:50.
Europe's forced austerity is pushing the continent into recession. Spain is already in one, and much of the rest of Europe is on the way. Luckily, the United States hasn't yet fallen into the austerity trap - America's fiscal policy is still wisely expansionary - but it's not sufficient to overcome a pull-back by American consumers.
Because most Americans' real pay continues to drop, they're going deeper into debt and tapping into their savings. Inevitably, they'll have to cut their spending. Without sufficient government spending to make up the difference, total demand will shrink, causing employers to pare hiring. March's disappointing jobs report could mark the beginning.
All this puts the odds of a Romney presidency far too high for comfort. So, what is Obama to do?
He'll have to go beyond "we're on the right track" and offer the nation a clear, bold strategy for boosting the economy. Such a strategy would help inoculate him if the US economy slows. It would also provide him with an economic mandate in his second term.
Obama should focus on four items.
First, he should demand that America's big banks modify the mortgages of homeowners still struggling in the wake of Wall Street's housing bubble. He should threaten that if the banks fail to provide meaningful relief to homeowners, in his second term he'll fight to resurrect the Glass-Steagall Act that used to separate investment from commercial banking. He'll also seek to break up Wall Street's biggest banks - as the Dallas branch of the Federal Reserve Bank recently recommended.
Second, he should stop oil speculators from raising gas prices. Numerous studies are showing that speculation by US index-fund traders is pushing up gas prices by almost $1 a gallon. Wall Street and Big Oil are making lots of money, but average Americans are paying the price. Oil-industry lawyers have gone to court to prevent the Commodity Futures Trading Commission from setting limits on such speculation. Obama should push the CFTC to set those limits, and instruct the Justice Department to investigate and prosecute oil-price manipulation.
Third, the president should make it clear he won't allow government spending cuts to take precedence over job creation. He won't follow Europe into an austerity trap of slower growth and higher unemployment. While he understands the need to reduce the nation's long-term budget deficit, he should commit to vetoing any spending cuts until the unemployment rate in the US is down to 5%. Instead, he should commit to further job-creating investments in the nation's crumbling infrastructure - pot-holed roads, unsafe bridges, inadequate pipelines, woefully-strained public transportation, and outmoded ports.
Finally, Obama should make sure Americans understand the link between America's fragile recovery and widening inequality. As long as so much of the nation's disposable income and wealth goes to the top, the vast middle class lacks the purchasing power to fire up the economy. That's why the so-called "Buffett rule" he has proposed - setting a minimum tax rate for millionaires - needs to be seen as just a first step toward ensuring that the gains from growth are more widely shared. He should vow to do more in his second term.
Such an economic strategy - forcing banks to help distressed homeowners, stopping oil speculation, boosting spending until unemployment drops to 5%, and fighting to ensure economic gains are widely shared - is critical to jobs and growth. It's the mirror image of Europe's failed austerity policies.
But to put any of this into effect, Obama will need a Congress that's committed to better jobs and wages for all Americans. He should remind voters that congressional Republicans prevented him from doing all that was needed in the first term, and they must not be allowed to do so again.
So far, President Obama's election strategy can best be summed up as: "We're on the right track, my economic policies are working, we still have a long way to go, but stick with me and you'll be fine."
This won't be enough to win him the election. The US recovery is too anaemic, and the chance of an economic stall between now and election day far too high.
Even now, Mitt Romney's empty "I'll do it better" refrain is attracting as many voters as Obama's "we're on the right track." Each is gathering 46% of voter support, according to the latest New York Times/CBS News poll.
Only 33% of the American public thinks the economy is improving, while 39% say they're still falling behind financially - an 11-point increase from 2008. Nearly two thirds are concerned about paying for housing, and 23% of Americans with mortgages say they're underwater.
If the economy stalls, Romney's empty promise will look even better. And I'd put the odds of a stall at 50:50.
Europe's forced austerity is pushing the continent into recession. Spain is already in one, and much of the rest of Europe is on the way. Luckily, the United States hasn't yet fallen into the austerity trap - America's fiscal policy is still wisely expansionary - but it's not sufficient to overcome a pull-back by American consumers.
Because most Americans' real pay continues to drop, they're going deeper into debt and tapping into their savings. Inevitably, they'll have to cut their spending. Without sufficient government spending to make up the difference, total demand will shrink, causing employers to pare hiring. March's disappointing jobs report could mark the beginning.
All this puts the odds of a Romney presidency far too high for comfort. So, what is Obama to do?
He'll have to go beyond "we're on the right track" and offer the nation a clear, bold strategy for boosting the economy. Such a strategy would help inoculate him if the US economy slows. It would also provide him with an economic mandate in his second term.
Obama should focus on four items.
First, he should demand that America's big banks modify the mortgages of homeowners still struggling in the wake of Wall Street's housing bubble. He should threaten that if the banks fail to provide meaningful relief to homeowners, in his second term he'll fight to resurrect the Glass-Steagall Act that used to separate investment from commercial banking. He'll also seek to break up Wall Street's biggest banks - as the Dallas branch of the Federal Reserve Bank recently recommended.
Second, he should stop oil speculators from raising gas prices. Numerous studies are showing that speculation by US index-fund traders is pushing up gas prices by almost $1 a gallon. Wall Street and Big Oil are making lots of money, but average Americans are paying the price. Oil-industry lawyers have gone to court to prevent the Commodity Futures Trading Commission from setting limits on such speculation. Obama should push the CFTC to set those limits, and instruct the Justice Department to investigate and prosecute oil-price manipulation.
Third, the president should make it clear he won't allow government spending cuts to take precedence over job creation. He won't follow Europe into an austerity trap of slower growth and higher unemployment. While he understands the need to reduce the nation's long-term budget deficit, he should commit to vetoing any spending cuts until the unemployment rate in the US is down to 5%. Instead, he should commit to further job-creating investments in the nation's crumbling infrastructure - pot-holed roads, unsafe bridges, inadequate pipelines, woefully-strained public transportation, and outmoded ports.
Finally, Obama should make sure Americans understand the link between America's fragile recovery and widening inequality. As long as so much of the nation's disposable income and wealth goes to the top, the vast middle class lacks the purchasing power to fire up the economy. That's why the so-called "Buffett rule" he has proposed - setting a minimum tax rate for millionaires - needs to be seen as just a first step toward ensuring that the gains from growth are more widely shared. He should vow to do more in his second term.
Such an economic strategy - forcing banks to help distressed homeowners, stopping oil speculation, boosting spending until unemployment drops to 5%, and fighting to ensure economic gains are widely shared - is critical to jobs and growth. It's the mirror image of Europe's failed austerity policies.
But to put any of this into effect, Obama will need a Congress that's committed to better jobs and wages for all Americans. He should remind voters that congressional Republicans prevented him from doing all that was needed in the first term, and they must not be allowed to do so again.