
SUBSCRIBE TO OUR FREE NEWSLETTER
Daily news & progressive opinion—funded by the people, not the corporations—delivered straight to your inbox.
5
#000000
#FFFFFF
To donate by check, phone, or other method, see our More Ways to Give page.
Daily news & progressive opinion—funded by the people, not the corporations—delivered straight to your inbox.

From October 12-18, 2026, the World Bank and IMF will hold their Annual Meetings in Thailand. Assembly of the Poor will mobilize to demonstrate that their policy prescriptions have inflicted severe harm on our people from the past to the present, and threaten our future.
Following World War II, the United States played a pivotal role in establishing the World Bank and the International Monetary Fundm or IMF. Originally tasked with post-war reconstruction, their focus soon shifted toward development aid for developing countries, including Thailand. In 1961, these two institutions guided the drafting of Thailand’s First National Economic Development Plan. They recommended large-scale infrastructure investments—ports, highways, and mega-dams—alongside import-substitution industrialization, agricultural reform through technology, chemical inputs, and genetic improvement of crops and livestock, as well as logging concessions aimed at generating national revenue. Land allocation programs were also introduced. Together, these policies triggered transformations that severely disrupted the livelihoods of smallholder farmers and peasants.
The recommendations of both institutions led directly to widespread deforestation and the destruction of natural resources through logging concessions and hydroelectric dam projects. Agricultural reforms degraded local ecosystems and drove up production costs while crop prices plummeted, pushing farmers into staggering debt and bankruptcy. Land allocation programs largely failed the rural poor; title deeds fell predominantly into the hands of bureaucrats, state officials, and wealthy investors. Smallholder farmers and peasants who did receive plots were left to clear and cultivate the land without government support, ultimately forcing many to abandon their holdings. A considerable number of people migrated to urban centers as cheap labor, crowding into slums area, facing homelessness, and becoming landless.
Development under the guidance of the World Bank and the IMF continued under subsequent National Economic and Social Development Plans—now in their 13th plan—yet consistently disregarded the poor. The two institutions hold joint Annual Meetings worldwide, having convened in Thailand for the first time in 1991. That same year, the World Bank approved a loan for the Pak Mun Dam in Ubon Ratchathani Province despite fierce opposition from many local villagers and civil society groups. The fallout from the dam was devastating: destroyed fisheries, extinction of fish species, community conflict and division, and electricity generation that fell far short of projections. It remains an indelible stain left by the World Bank in Thailand—one notably absent from its official history.
We reaffirm that genuine development must respect community rights over land, soil, water, and forests, uphold food sovereignty, and guarantee universal welfare as a fundamental human right.
The consequences of these development frameworks stirred widespread hardship among small-scale farmers, igniting protests, petitions, and grassroots resistance against top-down development in every nook and cranny. Escalating tensions between rural communities and the state led to arrests, prosecutions, violent crackdowns, and in some instances, the assassination of grassroots leaders. In December 1995, villagers impacted by dam constructions, communities evicted from forest areas, residents affected by the construction of an industrial plant, small-scale fishers affected by commercial fishing, marginalized workers, and slum dwellers gathered at Thammasat University and they announced the establishment of the “Assembly of the Poor” on December 10, 1995. The Assembly of the Poor moved their assembly to Khong Chiam District in Ubon Ratchathani Province, along the banks of the Mun River, where they drafted the "Pak Mun Declaration." The declaration proclaimed that local communities had been systematically impoverished by developmental policies that ignored their existence—leaving them poor not only economically, but impoverished in rights, opportunities, and political power. They declared that they had been made poor and would rise up to fight and demand that the state resolve their poverty.
Just two years later, during the 1997 Asian Financial Crisis (the "Tom Yum Kung Crisis"), the IMF stepped in with a bailout package for Thailand. To ensure rapid debt repayment, the IMF imposed stringent conditions: passing laws to regulate water usage, privatizing state enterprises to reduce public spending and boost revenue, and enacting legislation to remove universities and hospitals from the civil service system. These policies directly burdened the poor and sparked widespread popular resistance.
On September 3 this year, the World Bank released its report titled Building Thailand’s Future Today, declaring that poverty in Thailand had been virtually eradicated and touting a vision to elevate Thailand to a "high-income country" by 2037 through investment in five future industries. For the Assembly of the Poor, this represents a new wave of resource grabbing: data Center projects consuming massive amounts of water and electric power at the expense of local communities; green economy agendas and carbon credits threatening community rights; luxury tourism displacing Indigenous settlements; free trade agreements undermining local seed sovereignty; and transit-oriented developments displacing the urban poor. The report also urged immediate policy recommendations to establish legal and institutional frameworks for economic corridors beyond the Eastern Economic Corridor (EEC), paving the way for continuous, long-term structural development.
Compounding this, the IMF instructed the Thai government to abandon universal social welfare in favor of "targeted welfare" to maintain fiscal discipline—forcing vulnerable citizens to undergo demeaning "poverty testing" to access basic welfare benefits. The Thai government swiftly embraced these recommendations and accelerated projects aligned with both institutions, once again shifting the burden onto the poor and small-scale farmers. This is not building the nation's future; it is mortgaging it to international capital under a development paradigm that has dominated Thailand since its First National Economic and Social Development Plans, keeping citizens impoverished in rights, opportunities, and political power for over seven decades.
From October 12-18, 2026, the World Bank and IMF will hold their Annual Meetings in Thailand once again. Assembly of the Poor will mobilize to demonstrate that their policy prescriptions have inflicted severe harm on our people from the past to the present, and threaten our future. We reaffirm that genuine development must respect community rights over land, soil, water, and forests, uphold food sovereignty, and guarantee universal welfare as a fundamental human right. What is happening in Thailand is not an isolated story; it is part of a global neoliberal model through which international financial institutions strip developing nations, the poor, and peasants of their policy sovereignty. Our mobilization during the 2026 World Bank-IMF Annual Meetings in Bangkok is an international struggle to expose these policies, demand accountability, and reclaim policy sovereignty for the people.
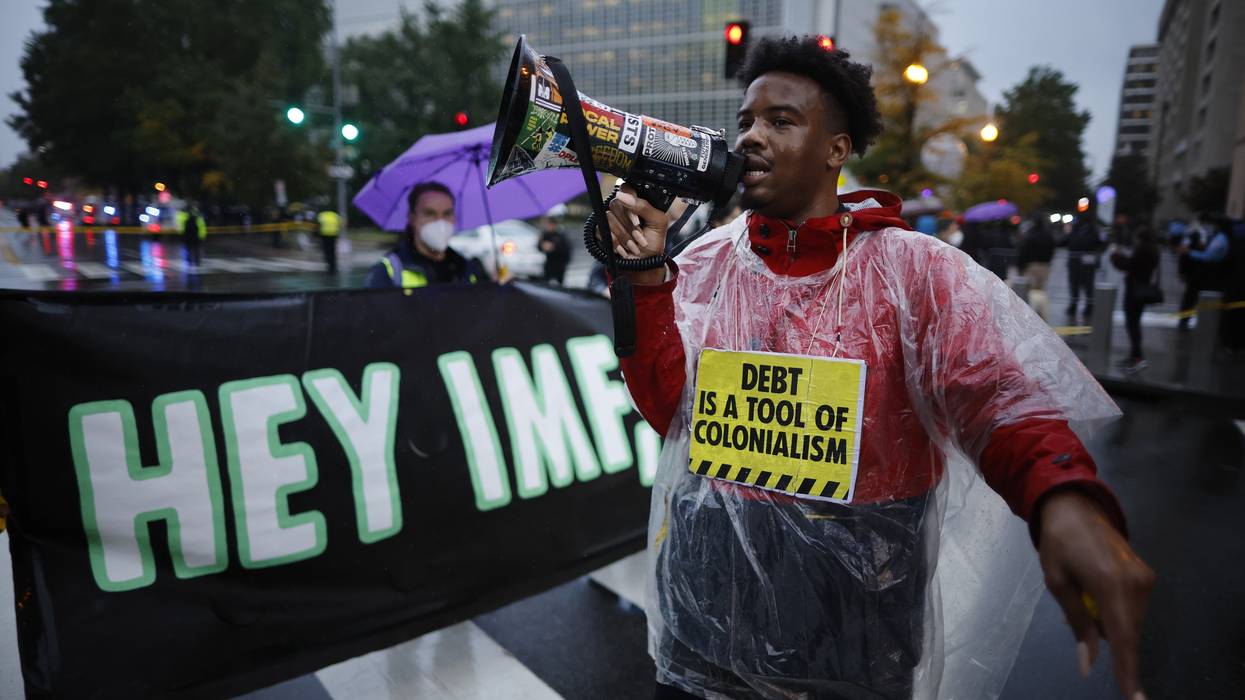
One ActionAid campaigner said rich nations should "cancel unjust and unsustainable debt, stop making countries borrow to survive climate impacts, and deliver climate finance as grants rather than loans."
The world's most climate-vulnerable nations are spending nearly 25 times more on servicing their debts than on addressing the climate emergency, an ActionAid International report released Wednesday revealed, underscoring what the advocacy group called a "vicious cycle" of debt, disasters, and underinvestment.
The report, "Debt Fuels the Climate Crisis: How the Finance Flows," examines government revenues, debt payments, national budgets, and climate plans in the 65 countries considered most vulnerable to climate change. The authors found that debt servicing consumes 65% of these nations' combined government revenue, while 93.5% of the countries are either in debt distress or facing a significant risk of it.
"Climate-vulnerable countries are being forced to spend nearly 25 times as much on repaying debt as on climate action," the report states. "Indeed, in 2026 total debt servicing on external and domestic debt in these countries is nearly four times that of spending on education, nearly seven times that of health, and nearly six times that of social protection."
🚨 New ActionAid analysis: countries facing the worst climate disasters are spending nearly 25 times more on debt than on climate action. That is not an accident. It is how the global debt system is built right now. Full findings 👉 https://bit.ly/4Acxh0c#ClimateJustice #FundOurFuture #DebtJustice
[image or embed]
— ActionAid USA (@aausa.bsky.social) September 16, 2026 at 6:31 AM
The disparity is even greater when comparing debt payments with climate grants. ActionAid estimated that countries in the Global South will make approximately $8.8 trillion in debt repayments in 2026, compared with just $39 billion in grant-based climate finance received in 2024—a ratio of roughly 225 to 1.
"For too long, the debt and climate crises have been treated separately," ActionAid International secretary-general Arthur Larok said in a statement. "This research exposes how tightly they are connected and quantifies the devastating cost involved. Yet this is a crisis we can fix."
The report—whose release coincides with the Global Week of Climate Action—highlights how climate disasters frequently force already indebted nations to borrow even more money for recovery and reconstruction. Subsequent debt payments and austerity measures forced upon them by global financial institutions like the International Monetary Fund (IMF) and World Bank then restrict their spending on climate resilience, public services, and clean energy transitions.
As the report notes:
Even though the IMF recognizes that there is a "development crisis," the IMF refuses to even talk about a systemic debt crisis—because for them and their shareholders, there is no systemic crisis so long as there is no significant default and creditors are being paid. Moreover, the IMF thrives on countries needing to come to them for bailout loans, as this expands their own power and influence. The IMF is both a creditor and a debt collector, serving its own interests and those of its main shareholders in the Global North—making it both judge and jury when it comes to debt renegotiation processes.
The report also details how Global South governments under pressure to generate foreign currency can expand fossil fuel extraction and industrial agriculture, potentially worsening the climate pressures that contributed to their debt in the first place.
“Debt is a triple whammy for the climate: It drives fossil fuel and industrial agriculture expansion, blocks vital climate action, and leaves communities dangerously exposed when disasters strike," ActionAid International global climate justice lead Teresa Anderson said Wednesday.
"This is a toxic relationship," she added. "Countries borrow to rebuild, austerity weakens their resilience, and repayment pressures push more extraction, fueling the next disaster. We need a breakup: Cancel unjust and unsustainable debt, stop making countries borrow to survive climate impacts, and deliver climate finance as grants rather than loans. This vicious cycle can and must be broken.”
“Debt is a triple whammy for the climate."
In Senegal, the imbalance is particularly stark. ActionAid said the government is spending $605 on debt servicing for every $1 budgeted for climate action, while debt payments consume more than 96% of government revenue.
"Behind these figures are impossible choices between servicing debt and investing in agroecology, public services, and climate resilience," ActionAid Senegal director Khaita Sylla said Wednesday. "Women and girls who bear the brunt of climate impacts are then disproportionately affected by cuts in public services even as they lead solutions for a more resilient future.”
ActionAid is calling on governments and international institutions to take steps including:
“Rich countries like the US have outsized global financial power," ActionAid USA executive director Niranjali Amerasinghe said on Wednesday. "Their lack of willingness to provide climate finance at scale and relieve the debt burden of climate-vulnerable countries is unconscionable."
"There are trillions for defense budgets," Amerasinghe added, "but peanuts for the biggest existential crisis of a generation.”
"For light at the end of the tunnel, you’d have to look to the 2030s," says the World Bank's chief economist.
The World Bank on Thursday lowered its global growth forecast for the remainder of 2026 as the illegal US-Israeli war of choice on Iran drives up energy prices, inflation, and the cost of debt.
"The global economy is facing another major shock," the World Bank's latest biannual Global Economic Prospects report states. "The conflict in the Middle East has triggered sharp increases in energy prices, renewed inflationary pressures, and fueled expectations of tighter monetary policy."
"Global growth is projected to slow to 2.5% in 2026, from 2.9% in 2025—the lowest rate since the Covid-19 pandemic—amid weaker prospects for economies dependent on energy imports and those directly affected by hostilities," the report continues. "Activity is expected to firm in 2027-28 as energy supplies recover, monetary easing resumes, and trade strengthens."
The Iran War has resulted in the closure of the Strait of Hormuz, through which around 30% of the world’s fertilizer and 20% of its oil previously passed. In addition to increasing the risk of a global food crisis, the strait’s closure has sent fuel and fertilizer prices soaring, with US farm diesel costing nearly 50% more than it did on the war’s eve in February and various fertilizer products spiking by between one-quarter and one-half.
The war has affected the economies of countries far removed from Iran, as the World Bank reports forecasts that "growth in emerging market and developing economies (EMDEs) is expected to slow to 3.6% this year."
"The level of per capita income across EMDEs excluding China and India, relative to advanced economies, is not expected to return to the pre-pandemic level until after 2028, implying nearly a decade of lost income convergence," the international financial institution predicted.
World Bank Group president Ajay Banga said in a statement Thursday that "developing countries have faced a series of challenges over the last decade."
“The impact differs by country, but the basic test is the same: Protect people and preserve stability today, without giving up on growth and jobs tomorrow," Banga added. "In response to the current shock, we are providing liquidity where it is needed now—and we are ready with additional financing, guarantees, and private-sector solutions if pressures deepen. Our job is to help countries steady the ship, keep reforms moving, and emerge stronger on the other side.”
The bank said in April that up to $100 billion would be made available over the next 15 months for nations suffering the most acute economic shocks caused by the war.
As US President Donald Trump and Israeli Prime Minister Benjamin Netanyahu allegedly undermine efforts to end the war, the World Bank cautions that the global economic outlook "remains skewed to the downside."
“A renewed escalation of hostilities or more prolonged disruptions to commodity flows could further raise commodity prices, intensify inflationary pressures and food insecurity, trigger financial stress, and lower growth,” the bank's report warns.
In his foreword to the new Global Economic Prospects report, World Bank Group chief economist Indermit Gill warned that "barring a miracle, the 2020s will prove to be what their ominous opening foreshadowed: a lost decade—not just for a couple of outliers, but for dozens of developing economies.'"
"Amid one of the densest clusters of global shocks since the 1970s, nearly 1 out of every 2 developing economies has failed since 2019 to advance on the most rudimentary promise of development: narrowing the income gap with the world’s most prosperous economies," Gill added. "For light at the end of the tunnel, you’d have to look to the 2030s."
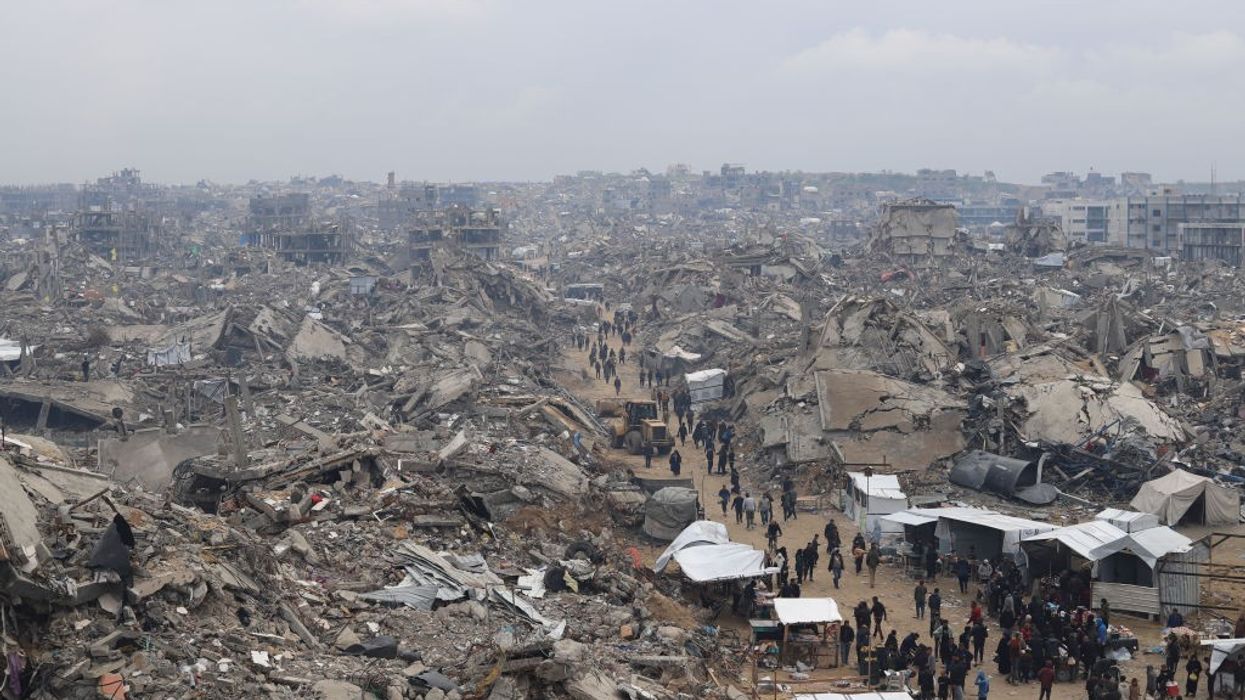
Only a tiny fraction of the already inadequate $17 billion pledged for Gaza reconstruction via US President Donald Trump's so-called "Board of Peace" has reportedly been received.
A joint assessment published Monday by the European Union, United Nations, and World Bank found that an estimated $71.4 billion is needed over the next decade for recovery and reconstruction in the Gaza Strip, where 30 months of Israeli genocide has set human development back by an entire lifetime.
The Gaza Strip Rapid Damage and Needs Assessment (RDNA) states that the $71.4 billion figure includes an estimated $26.3 billion required over the next 18 months "to restore essential service, rebuild critical infrastructure, and support economic recovery."
"Physical infrastructure damages are estimated at $35.2 billion, with economic and social losses amounting to $22.7 billion," the report continues. "The hardest-hit sectors include housing, health, education, commerce, and agriculture. Over 371,888 housing units have been destroyed or damaged, more than 50% of hospitals are nonfunctional, nearly all schools destroyed or damaged, and the economy has contracted by 84% in Gaza."
"Catastrophic impact on human development across Gaza... is estimated to have been set back by 77 years," the RDNA states. "Around 1.9 million people have been displaced, often multiple times, and more than 60% of the population has lost their homes."
"Women, children, persons with disabilities, and those with preexisting vulnerabilities bear the greatest burden," the publication adds.
The new analysis follows a November 2025 UN Conference on Trade and Development report that found Israel's assault on Gaza has caused “the most severe economic crisis ever recorded."
The Israeli war has left more than 250,000 Palestinians dead, maimed, or missing; the strip in ruins; and most of its approximately 2 million people forcibly displaced, starved, or sickened.
“Over two years of conflict has resulted in more than 71,000 Palestinian fatalities and over 171,000 injured, and many are missing under the rubble," the report notes.
With the vast majority of Gaza's buildings damaged or destroyed, separate UN analyses have estimated that it could take as many as 80 years to rebuild the obliterated coastal exclave.
So far, roughly $17 billion in pledged funding has been announced through the so-called "Board of Peace" launched by US President Donald Trump, whose ideas for rebuilding Gaza have included kicking Palestinians out and turning the strip into what he called the "Riviera of the Middle East."
Only a "tiny fraction" of that already inadequate $17 billion has been received, Reuters reported earlier this month.
The troubling question isn't whether IFC has environmental policies. It does; the question is whether these policies mean anything when clients consistently fail to comply and the public can't verify whether promised improvements ever materialize.
When the International Finance Corporation, or IFC—the World Bank's private-sector lending arm—invests in developing countries, it promises to uphold rigorous environmental safeguards. But our new analysis of $2 billion in livestock investments reveals an alarming gap between policy and practice that should concern anyone who cares about climate change, biodiversity loss, and environmental accountability.
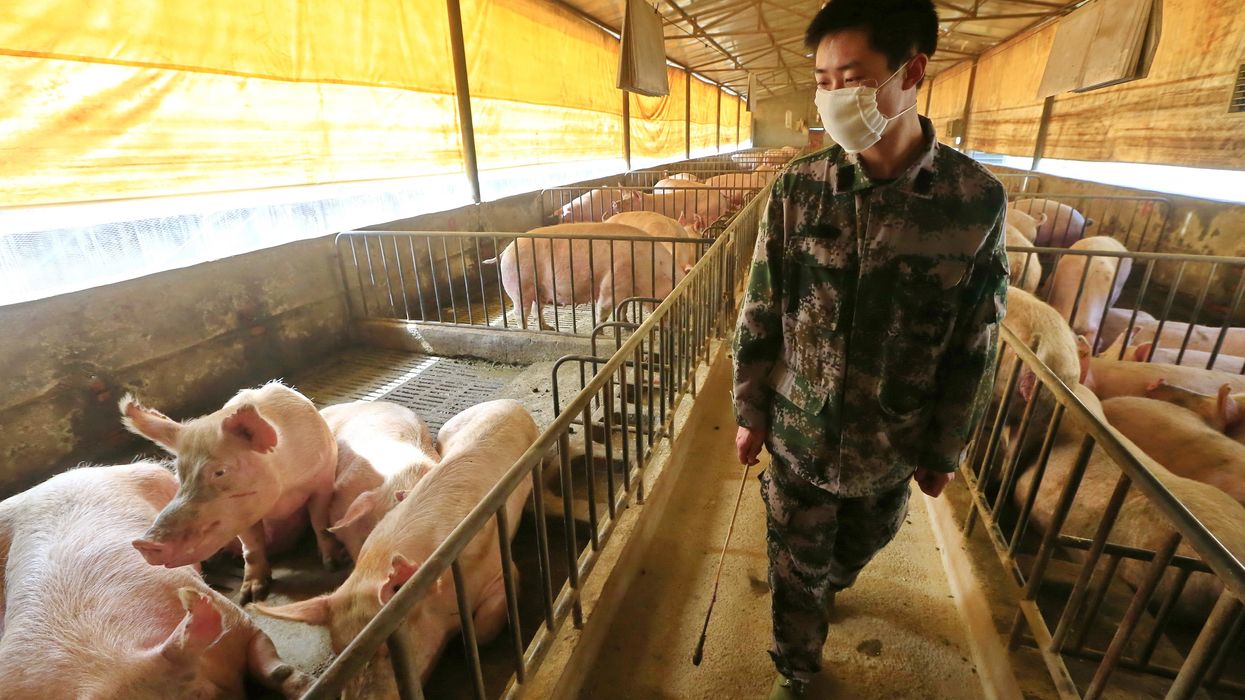
Between 2020 and 2025, the IFC pumped nearly $2 billion into 38 industrial meat, dairy, and feed projects across developing countries. These investments expanded factory farming operations at a time when scientific consensus highlights the urgency of transitioning away from industrial livestock production to protect both people and planet.
The troubling question isn't whether IFC has environmental policies. It does—robust ones, in fact, that 56 other development banks and 130 financial institutions use as benchmarks. The question is whether these policies mean anything when clients consistently fail to comply and the public can't verify whether promised improvements ever materialize.
Our latest report, Unsustainable Investment Part 2, analyzed publicly disclosed environmental risk assessment summaries for all 38 projects, evaluating whether IFC clients adhered to the bank's own requirements for managing biodiversity loss, pollution, and resource use. The findings are sobering.
On biodiversity, most projects offered superficial habitat assessments without the detailed analysis needed to identify critical or natural habitats. Not a single project demonstrated deliberate avoidance of high-value ecosystems—the most important step in preventing irreversible damage. Out of 10 projects facing supply-chain risks from habitat conversion, only 2 reported plans to establish traceability and transition away from destructive suppliers. This matters because industrial livestock threatens over 21,000 species and is the primary driver of deforestation globally.
Without transparent, ongoing disclosure, environmental safeguards become little more than paperwork exercises.
For pollution, the gaps were equally stark. Only one project assessed both ambient conditions and cumulative impacts as required. A few projects also reported exceeding national and international standards for air emissions and wastewater discharge at the time of approval. While many promised future improvements, there's no public evidence these promises were kept. Meanwhile, 29 projects provided no reporting whatsoever on solid waste management compliance—a glaring gap in transparency.
On resource use, the patterns continued. Only one project applied the full water use reduction hierarchy, with most reporting no evidence of even attempting to avoid unnecessary water consumption. This inefficiency is staggering: Industrial livestock uses 33-40% of agriculture's water to produce just 18% of the world's calories.
These findings build on our first Unsustainable Investment report examining client adherence to climate change related requirements. The gaps in adherence to disclosure and mitigation requirements were significant—despite IFC's commitment to align 100% of new investments with the Paris Agreement starting June 2026. For disclosure, while 68% of clients disclosed emissions, the reporting was highly inconsistent. Some reported only Scope 1 or Scope 2; others aggregated both scopes when they should have been separated. For mitigation, over 60% of projects failed to reduce emissions intensity below national averages. And zero projects—out of all 38—managed physical climate risks in their supply chains, despite industrial livestock's extreme vulnerability to climate change.
Perhaps the most concerning discovery is what we couldn't find: evidence of what happens after approval.
IFC's Environmental and Social Action Plans outline corrective measures that clients legally commit to implement over time. Many projects included plans to install pollution controls, improve resource efficiency, or enhance biodiversity management. But IFC doesn't systematically report whether these measures were actually implemented or whether they proved effective.
This absence of verification creates a dangerous accountability vacuum. Without transparent, ongoing disclosure, environmental safeguards become little more than paperwork exercises—compliance theater that manages reputational risk rather than environmental impact.
This matters far beyond IFC's portfolio. As the world's largest development finance institution focused on emerging economies, IFC functions as a standard setter. When IFC finances industrial livestock expansion despite weak compliance with environmental requirements, it sends a signal to global markets that such investments are "sustainable"—even when evidence suggests otherwise.
Consider the context: Industrial livestock contributes up to 20% of global greenhouse gas emissions, occupies 70% of agricultural land, and drives the planetary boundary transgressions that scientists warn threaten Earth's capacity to support human civilization. The World Bank's own 2024 report, Recipe for a Livable Planet, acknowledges that "to protect our planet, we need to transform the way we produce and consume food."
Yet IFC continues to invest billions in expanding the very systems the World Bank identifies as unsustainable. Civil society organizations have repeatedly documented environmental and social harms from IFC-financed factory farms in Ecuador, Brazil, China, and Mongolia—harm that occurs despite IFC's safeguards being applied.
This isn't an argument against development finance. It's a call for development finance that actually delivers sustainable development.
IFC must fundamentally reassess whether industrial livestock expansion is compatible with its mission. The institution should redirect financing toward food production systems that are demonstrably sustainable—agroecological approaches, diversified farming systems, and plant-based proteins that can deliver food security without exacerbating environmental crises.
Equally urgent: IFC must mandate full, transparent disclosure of environmental compliance throughout project lifecycles—not just at approval. Independent verification and meaningful consequences for non-compliance must replace the current honor system. Without enforcement, the world's most influential environmental safeguards are effectively optional.
Billions in public development finance continue flowing to industrial operations that drive climate change, biodiversity collapse, pollution, and resource depletion.
The stakes extend beyond any single institution. With IFC's president announcing plans to double annual agribusiness investments to $9 billion by 2030, and the Paris Agreement alignment deadline now extended to June 2026, the window for course correction is rapidly closing.
As 130 financial institutions benchmark their own environmental standards against IFC's Performance Standards, the compliance failures we've documented likely exist throughout the development finance sector. Systemic problems require systemic solutions.
The evidence is clear: IFC's environmental safeguards are robust on paper but weakened by inconsistent client adherence, limited transparency, and absent enforcement. The current approach manages compliance risk rather than environmental impact—a fundamental misalignment with both IFC's stated mission and the urgent imperatives of our environmental moment.
Seven of nine planetary boundaries have already been breached. The Earth system is under unprecedented stress. Yet billions in public development finance continue flowing to industrial operations that drive climate change, biodiversity collapse, pollution, and resource depletion.
The question isn't whether IFC can afford to change course. It's whether we can afford for it not to.
By supporting agroecology, multilateral development banks can stop fueling harm and start financing a just and sustainable food systems transition.
Agriculture is essential to human life. How we feed ourselves matters for nutrition, health, climate, biodiversity, and livelihoods. Nearly 928 million people are employed in farming globally, and food systems are responsible for one-third of global greenhouse gas emissions and most new deforestation.
Multilateral development banks (MDBs), like the World Bank Group (WBG), play a critical role. The WBG has committed to double its agricultural financing to $9 billion a year by 2030. In October it launched AgriConnect, an initiative seeking to transform small-scale farming into an engine of sustainable growth, jobs, and food security.
However, while some MDB investments support equitable and sustainable transformation, too many still fuel environmental destruction and inequity. The World Bank’s private sector arm, IFC, recently invested $47 million in a multi-story pig factory farm in China, for example.
A new report from the University of Vermont Institute for Agroecology analyses MDB agricultural investments and sets out a road map for how banks can support, rather than hinder, sustainable farming. The research finds that the World Bank and other public-sector lenders can drive systemic change by supporting governments with policy reforms, rural extension services, and enabling environments. For example, a $70 million Inter-American Development Bank project in Paraíba, Brazil is promoting inclusive, low-carbon agriculture, and strengthening family farmers and traditional communities through technical assistance and climate-resilient infrastructure.
MDBs’ private sector operations must reform their lending criteria and stop financing destructive projects.
MDBs are better placed than other financial institutions to take long-term, lower-return investments aligned with climate and food security goals. Agroecological farming, a holistic, community-based approach to food systems that applies ecological and social food sovereignty concepts, along with long-term productivity, provides a channel for public sector arms of MDBs to support needed agricultural transformation. MDBs and other public banks therefore, should seek to become the enablers of agroecology. The International Fund for Agricultural Development (IFAD) and the Agence Française de Développement (AFD) are already leading efforts in this direction.
In contrast to the IFAD and AFD models, the University of Vermont's Institute for Agroecology’s report found that the majority of private-focused MDBs prioritize “bankable” projects—typically large-scale, industrial, profit-driven agribusiness. This model steers money toward factory farms that use human-edible food as feed, pollute nearby communities, raise the risks of zoonotic disease and antimicrobial resistance, and engage in animal cruelty. In 2023, a report by Stop Financing Factory Farming found that public finance institutions invested US$2.27 billion in factory farming, 68% of the total investment in animal agriculture projects that year.
As evidenced by multiple complaints from impacted communities, these investments undermine poverty reduction, Sustainable Development Goals (SDGs), and Paris Agreement climate goals. MDBs’ private sector operations must reform their lending criteria and stop financing destructive projects.
Rich country governments currently subsidize agriculture, mostly industrial, at a level of $842 billion per year. According to the IMF, only a quarter is dedicated to support for public goods in the sector. Shifting this support to incentivize investments in agroecology is crucial to sustain the agricultural transformation that public banks themselves have called for.
Public banks have the opportunity to join a growing number of organisations already advancing an ecological approach to meet the SDGs and wider social, cultural, and economic, and environmental objectives. To do so, they must shift from treating agroecology as merely a niche solution and instead invest in it as a priority means for achieving food systems transformation.
Agroecology puts an end to costly and harmful practices, replacing animal cruelty with humane, safe, and fair standards.
By taking this approach, public banks can better support just transitions in food systems, something that is already beginning to take shape. Earlier this year, for example, the World Bank backed an $800 million loan to the Colombian government to advance a greener and more resilient economic transformation.
The private-sector arms of MDBs, such as IFC and IDB Invest, also have a role to play in aligning with the transition. Most importantly, they can support governments with policy advice and financing criteria that break from entrenched models and exclude industrial animal agriculture from eligibility for finance.
While MDBs have taken steps to make agricultural production and rural incomes less vulnerable to climate change, they have yet to commit to agroecological farming as the most effective pathway. In contrast, IFAD is already demonstrating what this can look like, driving agroecological transitions through private-sector incentives in Ethiopia, Peru, and Vietnam. Similarly, AFD is applying agroecology to support family farming in Ethiopia, Haiti, Madagascar, Malawi, and Sierra Leone.
If MDBs are looking to advance the SDGs and solve the polycrisis (climate, biodiversity, pandemic risk, and food security), one of the most effective ways in which this can be done is for the public sector to mobilize policy support and significant capital investment into agroecology. Meanwhile, MDB private sector arms can enable this transition by providing policy advice and finance for interventions that break from entrenched models.
Agroecology puts an end to costly and harmful practices, replacing animal cruelty with humane, safe, and fair standards. But it's not just about farming practices. It also helps transform food systems, building resilient, reparative, low-emission economies and improves livelihoods in line with the 2030 SDGs.
By supporting agroecology, MDBs can stop fueling harm and start financing a just and sustainable food systems transition. If they are serious about the SDGs, food security, and climate goals, the road map is clear—MDBs’ public sector operations must enable, their private sector operations must reform, and both must support a transition away from industrial agriculture toward a more just and sustainable food system.
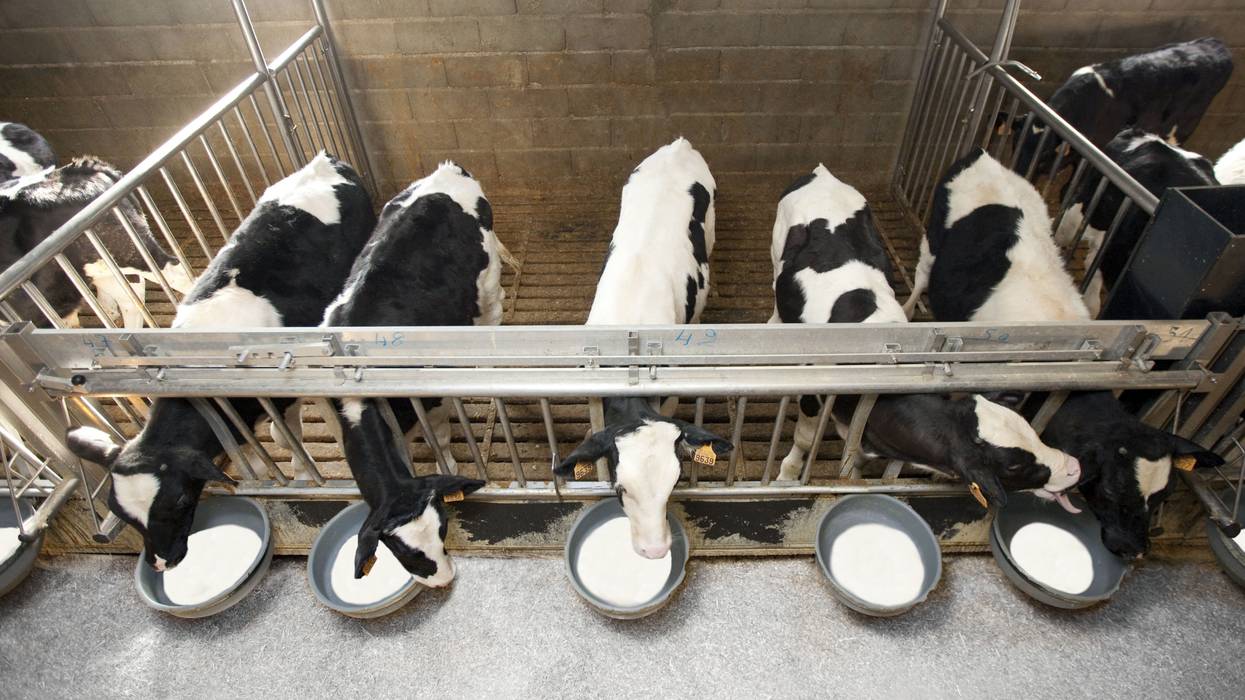
Despite clear evidence of the harms of industrial livestock, new research showed that in 2024, 11 leading international finance institutions invested $1.23 billion in factory farming and wider industrial animal agriculture supply chains.
The World Bank’s mission is to “create a world free of poverty on a livable planet.” However, the institution, along with its peer development partners, pumps billions of dollars into factory farming, appearing to turn a blind eye to the significant harm it causes.
We cannot meet the 1.5°C Paris agreement goal without reducing emissions from livestock. Animal agriculture is a leading cause of climate breakdown; already responsible for around 16% of global greenhouse gas emissions and set to rise.
Factory farming is also tearing apart our thriving ecosystems. In Latin America, high demand for industrial grazing pasture and land for growing animal feed has fueled devastating deforestation: 84% of all Latin America’s forest loss in the last 50 years can be attributed to land claimed for livestock farming. Factory farming also pollutes soils and freshwater sources that wild animals and rural communities rely on.
Development banks tasked with tackling poverty and climate change owe it to current and future generations to use their investments to help spur the transition toward more sustainable diets and forms of food production.
Yet despite clear evidence of the harms of industrial livestock, new research I conducted for the Stop Financing Factory Farming Coalition (S3F), based on data from the Early Warning System, showed that in 2024, 11 leading international finance institutions (IFI) invested $1.23 billion in factory farming and wider industrial animal agriculture supply chains. This is five times more than what they spend on more sustainable non-industrial animal agriculture projects. The World Bank and its private sector arm, the International Finance Corporation (IFC), were together responsible for over half the funding for industrial animal agriculture.
One of the investments IFC made last year was a $40 million loan to build a soybean crushing plant in Bangladesh, used to mass-produce animal feed. The soybeans will require an estimated 354,000 hectares of land annually to be grown, and will be sourced from Brazil and Argentina where soy production is associated with destruction of sensitive ecosystems. Communities living near the plant have documented the existing and potential impacts such as the contamination of coastal waters and freshwater sources, which would consequently lead to a reduction in the local fish stocks that local communities rely on to guarantee their livelihoods, and brought their concerns in front of representatives of the U.S. government.
Over the last 20 years, IFC has also made a number of investments in Pronaca, the largest food producer in Ecuador, to expand its factory farm operations. The company has built pig and poultry farms in Santo Domingo de los Tsáchilas, a region home to natural forest and Indigenous Peoples. Local Indigenous communities documented how the farms have polluted water resources that are traditionally used to sustain their livelihoods, forcing community members to migrate to preserve their traditional cultures.
Other IFIs have also made harmful investments. The European Bank for Reconstruction and Development (EBRD) boldly claims all its investments have been Paris-aligned since January 2023; however, recent spending to expand multinational fast food chains in Eastern Europe seem to show a different scenario. During the first half of 2025, the EBRD has provided $10 million for the expansion of KFC and Taco Bell restaurants in the Western Balkans, and proposed an equity investment of $46 million for the expansion of Burger King and Louisiana Popeyes in Poland, Romania, and Czech Republic.
The latter investment would have led to the opening of 600 restaurants in the region, with large adverse impacts in terms of public health and emissions of greenhouse gases. Restaurant Brands International, which owns Burger King and Popeyes, reported approximately 29 million metric tons of carbon dioxide-equivalent emissions along its value chain in 2024, more than the entire emissions of Northern Ireland. Thankfully, following civil society pressure, the investment was not approved by the EBRD’s Board of Directors.
While the overall picture is bleak, there is real room for hope. Between 2023 and 2024, IFI investments in factory farming nearly halved, and investments in more sustainable approaches tripled, from $77 million to US$244 million. Examples of promising investments include the Multilateral Investment Guarantee Agency and the Inter-American Development Bank providing support to smallholder farmers using climate-friendly techniques.
This is clearly good news; however, it remains too early to tell if these figures are a one-off blip, or part of a longer-term trend. My hope is that the next round of investment data will show that harmful investments have dropped further—if not stopped completely—and more sustainable ones additionally increased.
Development banks tasked with tackling poverty and climate change owe it to current and future generations to use their investments to help spur the transition toward more sustainable diets and forms of food production, rather than replicating and expanding the broken systems that are wrecking our planet. By only investing in animal agriculture projects that are sustainable—following agroecological principles such as promoting species diversity and using nature’s resources efficiently—banks can help move us closer toward “a world free of poverty on a livable planet.”

This milestone is not only a leap forward for International Finance Corporation but also a hopeful sign for communities harmed by development projects around the world.
In a historic moment, the International Finance Corporation became the first development finance institution, or DFI, to adopt an explicit policy on remedy. On April 15, IFC published its Remedial Action Framework, formalizing a commitment to address environmental and social harms caused by IFC-supported investment projects.
This milestone is not only a leap forward for IFC but also a hopeful sign for communities harmed by development projects around the world. The Remedial Action Framework (RAF) is a cornerstone in a broader shift at a moment when the World Bank Group is planning to undertake a major overhaul of the environmental and social accountability systems on the public and private sides of the institution. The RAF sets the stage for a profound institution-wide commitment to avoid and remedy harm at the entire World Bank. Whether the grievance mechanisms and accountability systems of the institution change, or amendments to the environmental and social policies occur as part of this overhaul, the principles and drive for this cultural shift at the institution must now be rooted in the notion that remedy is possible at the World Bank.
As project-affected communities have illustrated through the years, harm is harm—no matter what type of investment may have led to it.
The IFC/Multilateral Investment Guarantee Agency (MIGA) framework is the result of years of advocacy, discussion, and perseverance by numerous stakeholders both outside and inside the institution, as recognized in the RAF itself. The strenuous efforts from civil society organizations (CSOs) and project-affected people from around the globe stemmed from firsthand experience of harm as well as technical recommendations and proposals to ensure that the remedy is centered on the rights and the needs of those who have been harmed.
The RAF is a fundamental part of an approach that will focus on remedy but will also make considerations about when and why to exit a project responsibly, as established in its Responsible Exit Approach issued in October 2024.
It is particularly meaningful that the RAF acknowledges that, like all development institutions, IFC and MIGA must play a role in the “remedial action ecosystem.” This recognition signals a full understanding of the core tenet of international law, namely that institutions should avoid infringing on the human rights of others and should address adverse human rights impacts when they have contributed to harm.
The RAF aims to provide a structured approach to address harm arising from the environmental and social (E&S) impacts of projects supported by IFC/MIGA. While the emphasis on the differentiated roles that IFC/MIGA and their clients play in providing remedy for harm remains, the support by IFC and MIGA for these remedial actions is a central part of the equation, focusing on:
The RAF will apply to all IFC-supported investment projects and all investment projects covered by MIGA political risk insurance guarantees. It makes distinctions for IFC/MIGA’s support for remedial actions, asserting they will vary depending on each case, stemming from factors such as the type of investment, proximity to harm, and other factors. Reaching an understanding of how these factors will be considered will require more detail than what is included presently in the RAF.
IFC/MIGA’s contribution to remedy will entail the use of influence and leverage to encourage clients to take remedial action, as well as providing support for enabling activities, such as fact-finding, technical assistance, and community development activities. Ultimately, the extent and effectiveness of these contributions will depend on the levels of engagement and participation from those seeking remedy.
While the RAF does contain references to institutional risks associated with providing direct funding for remedial actions by IFC/MIGA, it also acknowledges that the primary focus on enabling activities is meant to minimize these risks.
Notably, the RAF was approved on an interim basis, pointing to the importance of its three-year piloting phase to implement the approach. Practical application and enforcement of the RAF will certainly be the biggest challenge, but the inclusion of regular interactions with stakeholders, updates, and a final assessment to be conducted with the Compliance Advisor Ombudsman (CAO) to incorporate lessons learned to perfect the final policy is positive.
The RAF emphasizes sustainability frameworks and the value of strengthening prevention and preparedness and facilitating remedy through grievance mechanisms, echoing a long-standing demand from civil society that avoiding harm must be prioritized over managing its aftermath. It is admirable to finally have IFC recognize the crucial need to identify and manage E&S risks and potential impacts to avoid harm in the first place, but this too will require a change in operations and culture at IFC so that every aspect of IFC’s operations is seen through an environmental and social lens—a shift that aligns with a human rights-based approach.
Assessing a client’s preparedness and capacity to properly identify and mitigate environmental and social risks and to provide access to remedial actions in the event of harm is one of IFC/MIGA’s primary roles. If IFC/MIGA are committed to the complementary roles required for remedial action implementation, then this primary role becomes ever more salient and fixed to its new mandate.
The RAF should be praised. It has also created an opportunity to institute an approach to remedy within the entire World Bank Group at the perfect moment.
And as IFC begins the process of updating its Sustainability Framework, it is the perfect time to capture the principles and thrust of the Remedial Action Framework and Responsible Exit Approach in a manner that enhances broad adoption and integration of the approach to remedy at the entire institution.
Although the RAF does not mention the Responsible Exit Approach—including a reference to IFC/MIGA’s leverage over a “former client”—it nods to its relevance by recognizing the challenges faced when clients are not willing to address situations of harm. Planning with clients to ensure a responsible exit from all projects—and leveraging the role of IFC/MIGA in contributing to remedy through enabling activities—remains fundamental.
Based on the background provided in the RAF, one would assume that the framework is the result of the 2018 external review of the E&S accountability of IFC and MIGA, including the role and effectiveness of the CAO. Yet, civil society organizations that have been advocating for accountability and remedy for decades would quickly point to problematic projects such as Alto Maipo, Titan Cement, and Tata Tea, recalling the numerous communities who filed complaints proving the inadequacy of the system. For many of them, the ultimate catalyst for the turnaround would be the Tata Mundra case. This case—and the landmark Jam v. IFC litigation by Indian fisherfolk—highlighted the gaps in accountability when IFC dismissed the CAO’s findings and recommendations to bring the project into compliance and to provide remedy for communities.
Considering this history with the CAO, it is all the more notable that IFC/MIGA has embraced access to remedy as part of the holistic approach to remedial action within the RAF. They recognize the vital necessity of putting in place effective, reliable, and independent grievance mechanisms to address complaints raised by project-affected people when things go wrong.
IFC/MIGA emphasizes the client’s creation of an effective project-level grievance mechanism while maintaining the existence of IFC’s internal grievance mechanism—the Stakeholder Engagement and Response office—and the CAO. Together, these mechanisms make up the diverse cadre of options with varied levels of outcomes and results. By acknowledging the opportunity to capture lessons from the RAF’s initial implementation to inform updates to IFC/MIGA Sustainability Frameworks and the upcoming CAO Policy review, IFC/MIGA notably endorses raising the level of engagement and usefulness of these mechanisms.
For some time, CSOs and project-affected communities have been advocating for improvements to the CAO and grievance mechanisms at DFIs worldwide. Years of experience and long-standing collaboration led to the creation of the Good Policy Paper Guiding Practice from the Policies of Independent Accountability Mechanisms. These recommendations have been useful for numerous institutions seeking to improve their accountability frameworks with the ultimate goal of facilitating access to effective remedy.
As stated in the RAF, “IFC/MIGA as development institutions have a role to play in the context of the broader remedial action ecosystem and may contribute to remedial action in the following ways:
Even though the role of the client vis-à-vis IFC/MIGA is permanently interlinked, IFC/MIGA has approved an approach to remedy that still puts the client at the forefront of managing E&S risks and impacts, as well as funding and implementing remedial actions.
The initial perception of what was possible for a World Bank institution has evolved, noting IFC/MIGA’s commitment to contribute to Remedial Action as set forth in the RAF. While restating their role in using financial and contractual leverage to encourage clients to take remedial actions to address harm, IFC/MIGA will also provide support for enabling activities that will allow clients to provide solutions to project-affected people.
The scope of enabling activities may potentially allow for a broad range of actions by IFC/MIGA. While this will require practical experiences from the piloting phase to test and perfect the framework, initial considerations of enabling activities as presented in the RAF are promising as a minimum starting point:
Additionally, while IFC/MIGA expect that enabling activities will be the preferred mode of engagement in most cases where project-level remedial action is warranted, the RAF states that this does not prevent them from proposing other modalities for approval by the Board.
A major question and point of contention over these last years has been the cost of providing remedy. Here, the matter of differentiated roles has a direct bearing on the question of cost when IFC’s client is responsible for managing E&S risks and impacts. Something worth noting is the fact that private sector clients who joined IFC/MIGA consultations on the approach to remedial action were never opposed to remedy, but mainly concerned with how this could be done. They acknowledged the role of a project developer in remedying harms resulting from project construction, operations, etc. Their main question was always how to implement such a policy and how the costs would be allocated.
The RAF is clear about the costs for remedy, stating that under IFC’s Sustainability Framework, clients are responsible for managing E&S risks and impacts as well as funding and implementing remedial actions. While this would seem straightforward, the purpose of DFIs and the implementation of their mandates are at the core of an often nebulous division of roles. Considering this, the detailed description of IFC’s Sustainability Frameworks within the RAF comes into focus, as it is precisely the issue of a client’s ability to comply with IFC’s E&S policies and standards that makes IFC’s adjacent role more obvious and essential.
As we face environmental and climate crises globally, and financial institutions join in multiplying funds available to address the growing need for solutions, we can now point to the first remedial action framework and concrete driver for ways of addressing harm and providing remedy.
For instance, if IFC’s E&S due diligence at project appraisal is done properly, and if supervision and regular monitoring during project implementation are carried out entirely, then IFC can be sure that its client has managed E&S risks and impacts. As a result, the client adhered to IFC’s Performance Standards, applying the mitigation hierarchy correctly by taking all measures necessary to prepare for and avoid or minimize adverse impacts to the environment and preventing harm to people. However, when IFC fails to supervise and monitor its client properly, or when initial due diligence is lacking, or it neglects to notice a low-capacity client, then the risks are likely to materialize, causing harm.
If IFC realizes these errors, it may request corrective actions and changes to E&S Action Plans, so its client brings the project into compliance, yet this is not guaranteed. These are precisely the types of errors that have led affected communities to file complaints at the CAO, and the issues IFC has been grappling with for many years, ultimately leading to internal shifts and restructuring in E&S governance at the institution after assessing the entire accountability system.
Funding for contributions to remedial action by IFC will be obtained through the project’s funding structure, donor trust funds, IFC’s administrative budget, or operational risk capital. At the same time, MIGA’s contribution to remedial action activities is limited to available trust funds or existing budgetary resources.
Ultimately, the fact that IFC/MIGA has incorporated the possibility of using its own financial resources to contribute to remedial actions in the RAF, while still mentioning their concern for the risk of doing so, points to a change in perceptions that will ideally continue to shift the mode of thinking at the entire institution. Simply said, remedy should be seen as the goal from now on and something that should color all decisions at development finance institutions.
The RAF was approved by the Board of Directors of both IFC and the MIGA on April 3 on an interim basis for three years. Implementation of the RAF during the pilot phase will require IFC/MIGA’s regular engagement with stakeholders to receive input and share updates.
As an essential part of the initial six months of implementation, IFC and MIGA, in consultation with the CAO, will have to define and track key performance indicators related to efficiency and effectiveness to ensure proper monitoring of the interim approach. IFC/MIGA will also monitor implementation, providing the boards with briefings and annual monitoring reports.
A final assessment in consultation with the CAO will be carried out at the end of the three-year period. The final policy will incorporate lessons learned and proposed revisions for review by the boards.
The RAF should be praised. It has also created an opportunity to institute an approach to remedy within the entire World Bank Group at the perfect moment. As project-affected communities have illustrated through the years, harm is harm—no matter what type of investment may have led to it. As we face environmental and climate crises globally, and financial institutions join in multiplying funds available to address the growing need for solutions, we can now point to the first remedial action framework and concrete driver for ways of addressing harm and providing remedy.
Other institutions are now following suit. The IDB Group has indicated for several years that internal discussions on Remedy and Responsible Exit were already underway. Most recently, IDB Invest has prepared a draft approach to Responsible Exit based on the IFC/MIGA model and has been engaging with civil society and project-affected communities to receive feedback, while also moving on internal discussions for a remedy framework.
In the days following the approval of the IFC/MIGA Remedial Action Framework, CSOs had the opportunity to meet with IFC. The conversations had an immediate change in tone. This was a different conversation with other approaches for new projects, new contracts, thinking through how to make this framework a reality, with a sense of pride.
This was not lost on anyone. It revealed the legitimacy of having a framework and accompanying Responsible Exit Approach set to paper, as approved by the boards of these institutions. It showed its significance, its weight as a standard to follow, as a directive to take, and as a way forward for an institution that has finally recognized that development can sometimes have negative impacts, and that those impacts can lead to harm for communities. But now there is a way to address these harms and provide remedy, the commitment to do so has been set, and many are ready to make this happen, as challenging as it will undoubtedly be.
The nearly $4.7 billion in International Finance Corporation trade finance commitments that may have supported fossil fuel-related projects in 2023 is a telltale example.
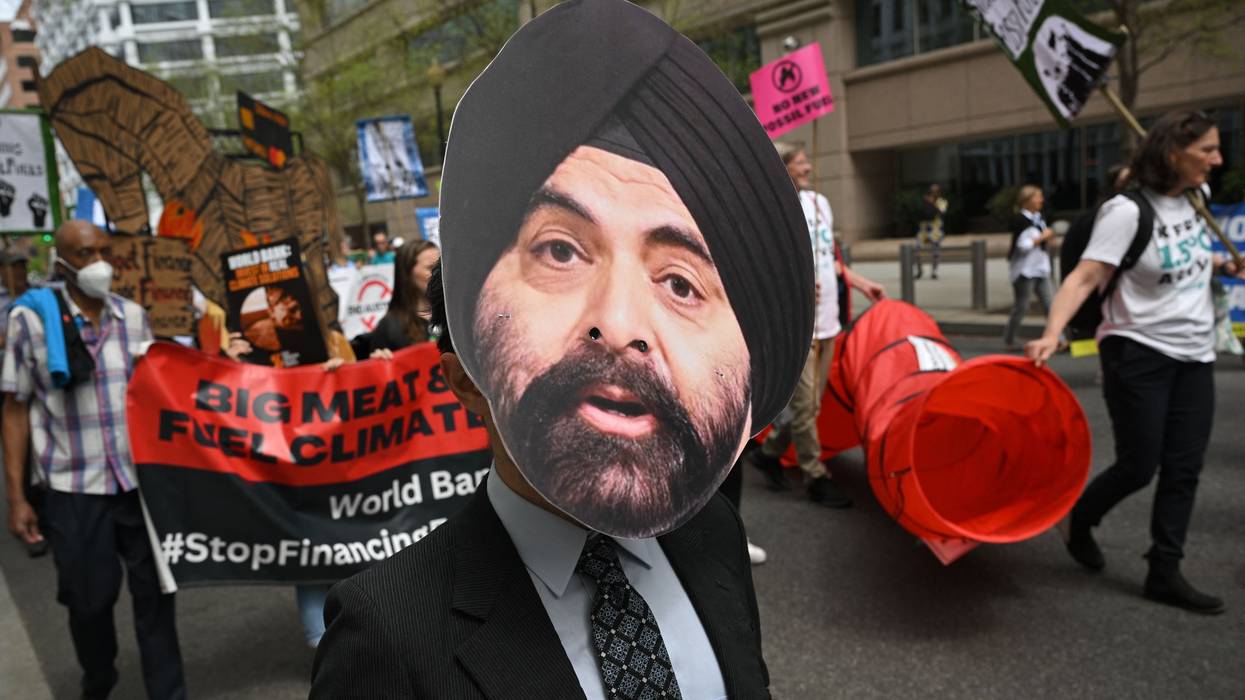
Since assuming office, World Bank President Ajay Banga has pursued a clear agenda: mobilize vast amounts of private capital in service of the bank’s goal to end poverty on a livable planet. There are many valid criticisms of this approach, but none speaks louder than a deeper look into the World Bank’s own private sector arm, the International Finance Corporation, or IFC, and its dealings.
Urgewald’s research on IFC trade finance in Financial Year (FY) 2022 and FY2023 shows just how slippery the private sector slope can be. Indeed, the IFC trade finance program’s alarming developments exemplify the World Bank’s overall trajectory: throwing good money after bad, neglecting environmental and social standards, and prioritizing private profit over public well-being.
From FY2017 to 2023, the IFC trade finance portfolio saw a hefty 86% increase. In FY2023, trade finance amounted to 58% of the IFC’s total portfolio. (Trade finance refers to a range of financial instruments and services designed to facilitate international trade. It provides liquidity and risk mitigation for exporters and importers, enabling transactions that might otherwise not be viable. Instruments such as letters of credit, guarantees, and working capital loans ensure that buyers and sellers can engage in global trade with reduced financial risks.)
The private sector’s profit orientation is incompatible with the World Bank Group’s public service mandate.
While the sums for trade finance are growing exponentially, the checks and norms for their disbursal are stagnating. The environmental and social standards that apply to trade finance have not been updated for at least a decade, and financial flows are shrouded in mystery.
The stated goal of ending poverty on a livable planet presupposes transparency, accountability and sustainability. And yet the meteoric rise of IFC trade finance transactions in recent years comes with opacity, outright unwillingness to disclose basic information about individual transactions, and the long shadow of fossil fuel favoritism.
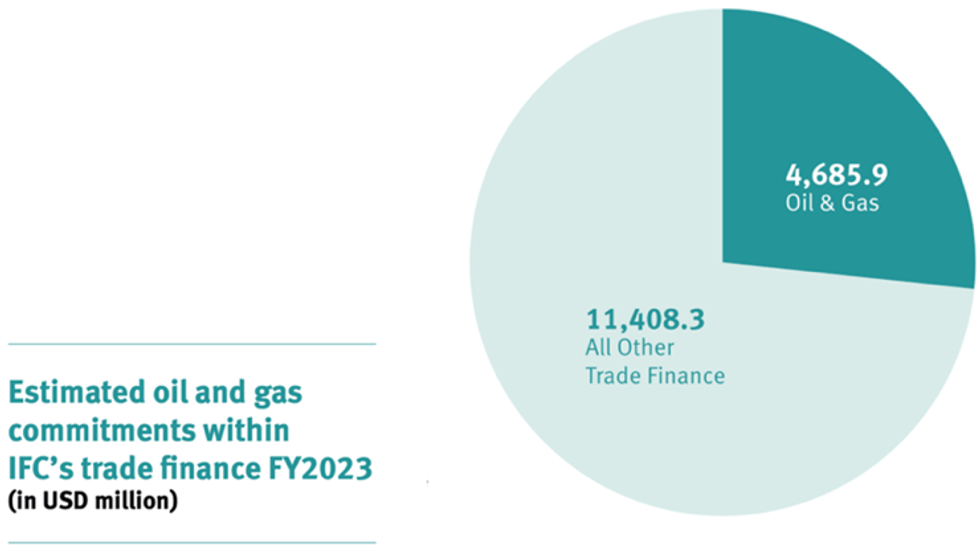
So, what’s the number? In FY2023, $4.7 billion, or nearly one-third of total IFC trade finance commitments, may have supported fossil fuel-related projects. This figure represents a 28% increase compared to FY2022.
The Global Trade Finance Program (GTFP) alone accounted for $3.7 billion of possible oil and gas-related financing, 41.7% of its total commitments. Transparency issues persist as the IFC fails to disclose detailed information about specific trade transactions and beneficiaries.
The World Bank Group’s own Independent Evaluation Group (IEG) indicates that in the past, significant shares of IFC trade finance investments went into fossil fuel financing, particularly in Africa (50%) and the Middle East (28%).
The dangerous trend of enabling fossil fuel transactions in fragile countries expands when we look at the IFC Private Sector Window (PSW). It was established in 2017 to encourage private sector investments in high-risk, low-income countries, particularly in IDA-designated regions. The PSW provides risk-sharing mechanisms and facilitates trade finance and other investments that might otherwise be deemed too risky. Between FY2020 and FY2024, $1.03 billion, or about a quarter of PSW approvals, were allocated to trade finance projects. These funds enabled $5.1 billion in trade finance, underscoring the PSW’s leveraged impact.
This fivefold impact, however, remains controversial. Despite its commitment to sustainable development, the PSW lacks exclusion criteria for fossil fuels. Thus, it allows for investments in oil and gas. Transparency remains a significant issue, and information about specific projects and the traded commodities is sparse. PSW-supported trade finance’s environmental and developmental impacts are questionable at best.
Many of these problems precede President Banga’s tenure. However, it is vital to highlight and address them now because his laser focus on mobilizing private capital is likely to exacerbate the issues highlighted above. The private sector’s profit orientation is incompatible with the World Bank Group’s public service mandate. The IFC’s growing trade finance portfolio highlights the organization’s critical role in shaping global trade. The significant share of fossil fuel commitments in that portfolio undermines the World Bank Group’s mission of fostering sustainable development.
To align with international climate objectives, the IFC must adopt urgent reforms to enhance transparency; exclude harmful investments; and prioritize clean, fair, decentralized renewable energy—especially in poor and high-risk regions of the world that need them most. To better align the PSW with its mission, the allocation of Private Sector Window funds should prioritize renewable energy and sustainable development projects. Additionally, stringent exclusion criteria and improved reporting standards should ensure greater accountability and alignment with climate and social goals.
These changes are clearly at odds with President Banga’s agenda, and yet only through them can the World Bank Group stay true to its noble goals.

These are two of the most questionable and controversial institutions directly or indirectly funded with U.S. taxpayers’ money.
I think that Elon Musk and his Department of Government Efficiency, or DOGE, have been misinformed. I don’t disagree with their shutting down USAID, but I think it’s rather small fry. There are much, much bigger fish to fry if you want to really save U.S. government money that is being wasted in programs that are mischievously justified as aid to the poor people of the world.
Elon, hear me out: if you walk northwest from your headquarters at the Eisenhower Executive Building along Pennsylvania Avenue, you’ll come after one long block upon two ugly buildings squatting beside each other. One is the World Bank. The other is the International Monetary Fund (IMF). You can actually just walk in and demand to look at their books since they are extensions of the U.S. government. And you would have a very good reason to do so, since these are two of the most questionable and controversial institutions directly or indirectly funded with U.S. taxpayers’ money.
The IMF and the World Bank are monuments to misguided economic thinking and policies that have brought much misery to the peoples of the Global South.
Let me start with the World Bank, which is located at 1818 H St NW. This institution has so-called development projects throughout the Global South, otherwise known as developing countries. This agency says that its mission is to end poverty in the developing world. To fulfill this goal, its lending has risen from nearly $55 billion in 2015 to $117.5 billion in 2024. Yet, despite this massive increase, the bank admits that global poverty reduction “has slowed to a near standstill, with 2020-2030 set to be a lost decade.” Some 3.5 billion people, or 44% of the globe, remain poor, after decades of massive World Bank lending. And a major part of the reason is that World Bank programs have created poverty instead of alleviating it.
To manage its operations, the Bank’s full-time staff rose from nearly 12,000 in 2015 to over 13,000 in 2023. These figures are just the tip of the iceberg. If one includes all employees—permanent, non-permanent, contractual, part-time—throughout the world, the bank employs close to 41,000 people. The vast majority, 26,000, or 63%, work out of the World Bank headquarters in Washington, D.C., and only 3,200 are located in Africa, where most people in extreme poverty live.
The Bank’s economists and top administrators are among the highest paid financial functionaries in the world, which explains the reason why the bank is a major cause of the brain drain from developing countries: a great number of highly trained economists from developing countries prefer to work at the bank instead of their home countries, with some going straight from Ivy League or British graduate schools to Washington, D.C. Many within the bank and the International Monetary Fund complain about the “South Asian Mafia” that they claim controls employment opportunities for economists and higher-level staff in the two organizations.
The World Bank has come under fire for the billions it has spent supporting fossil-fuel projects throughout the Third World that have contributed to global warming and to mega-dam projects that have displaced millions. The bank, along with the fund, has also gained notoriety for imposing “structural adjustment” programs guided by the radical principles of the “Washington Consensus” that are designed to promote globalization but have, instead, increased poverty and deepened inequality. The reason World Bank projects and programs don’t work or create exactly the opposite of their intended goals is because they are based on questionable propositions built on little or no empirical evidence. An assessment made a few years ago by an all-star team of renowned economists led by Princeton’s Angus Deaton, a recipient of the Nobel Prize for Economics, was damning:
[The] panel had substantial criticisms of the way that the research was used to proselytize on behalf of bank policy, often without taking a balanced view, and without expressing appropriate skepticism. Internal research that is favorable to bank positions was given great prominence, and unfavorable research ignored. In these cases, we believe that there was a serious failure of checks and balances that should have separated advocacy and research. The panel endorses the right of the bank to strongly defend and advocate its own policies. But when the bank leadership selectively appeals to relatively new and untested research as hard evidence that these preferred policies work, it lends unwarranted confidence to the bank’s prescriptions. Placing fragile selected new research results on a pedestal invites later recrimination that undermines the credibility and usefulness of all bank research.
The bank’s refusal to acknowledge real-world refutations of its pro-globalization advocacy and its unbalanced, one-sided research led to justifiable rejection of its advice by the people who were suffering from the policies it was implementing, confessed Paul Collier, head of the Research Development Department of the Bank from 1998 to 2003:
The profession has been unprofessional, fearful that any criticism would strengthen populism, so that little work has been done on the downsides of these different processes [of globalization]. Yet the downsides were apparent to ordinary citizens, and the effect of economists appearing to dismiss them has resulted in widespread refusal of people to listen to “experts.” For my profession to reestablish credibility we must provide a more balanced analysis, in which the downsides are acknowledged and properly evaluated with a view to designing policy responses that address them. The profession may be better served by mea culpa than by further indignant defenses of globalization.
Despite the high rate of failure of its lending programs acknowledged in internal World Bank assessments, the World Bank administrative budget that supports the high salaries of its economists and other high-level staff just keeps growing. The World Bank (IBRD/IDA) administrative budget was approved at $3.5 billion for FY25, a sizable rise from the $3.1 billion authorized for FY 2024, with no convincing reason at all.
The International Monetary Fund, whose address is 700 19th St NW, is the World Bank’s sister agency. It has a full-time staff of 3,100, supported by a budget of $1.5 billion. The IMF’s economists are paid even higher than those at the World Bank, and they evoke more fear, hatred, and contempt than the Bank.
The IMF has an equally controversial history. It has a record of coming in to supposedly assist developing economies in crisis, only to make things worse. Its greatest debacle and scandal was its performance during the Asian Financial Crisis of 1997-98, when the so-called “tiger economies “of the East and Southeast Asia were destabilized by the massive inflows and outflows of foreign portfolio investment.
The fund was heavily criticized on three counts. First, it had encouraged the governments of the region to eliminate capital controls, thus provoking uncontrolled capital flows. Second, it assembled multi-billion dollar “rescue packages” that went to rescue not the people suffering from the crisis but to compensate the foreign financial speculators that had lost millions in dubious speculative ventures, thus encouraging “moral hazard,” or irresponsible investing. Third, its measures to stabilize the damaged economies intensified the crisis, since instead of encouraging government spending to counteract the collapse of private sector, it told the governments to radically cut spending, leading to a “procyclical” negative synergy that ended in deep recession.
So long as the IMF is there, the big international banks will assume that they will be bailed out for making irresponsible loans.
In just a few weeks, 1 million people in Thailand and 22 million in Indonesia fell below the poverty line. The only country that contained the crisis was Malaysia, which refused to follow the fund’s dictates and imposed capital and currency controls
So disastrous were the IMF’s interventions that George Schultz, President Ronald Reagan’s secretary of the Treasury, called for its abolition for encouraging moral hazard, and prominent economists like Jagdish Bhagwati and Jeffrey Sachs accused it of provoking global macroeconomic instability. Indeed, a rare conservative-liberal alliance in the U.S. Congress came within a hair’s breath of denying the IMF a $14.5 billion replenishment.
Eventually, the fund was forced to admit that the “thrust of fiscal policy… turned out to be substantially different… because the original assumptions for economic growth, capital flows, and exchange rates… were proved drastically wrong.” But things were never the same again. The IMF was so reviled for its performance that Asian governments developed IMF-phobia, swearing never again to ask the IMF for rescue even in the most dire circumstances. For instance, after paying off what Thailand owed the IMF, Prime Minister Thaksin Shinawatra declared the country “liberated” from the fund in 2004.
Instead of learning from its debacle during the Asian Financial Crisis, the IMF stumbled into another fiasco more than a decade later, during the Global Financial Crisis. It allowed itself to be hijacked by Germany, the European Commission, and the European Central Bank to provide billions of public money to rescue German financial institutions and investors that had engaged in an orgy of irresponsible lending to Greece to the tune of 25 billion euros. To get the so-called rescue funds, the Greek government, like the Asian governments previously, was forced to adopt severe austerity measures that drove unemployment up to 28% and condemned the Greek economy to permanent stagnation, only to turn the money it was ostensibly receiving over to the German banks.
Not surprisingly, so long as the IMF is there, the big international banks will assume that they will be bailed out for making irresponsible loans.
There is a fiction that the IMF and World Bank are multilateral institutions that are owned by their many member governments. The reality is that the United States controls both institutions, with a 17.4% share of total quotas at the fund and 15.8% share of voting power at the bank. These shares give the U.S. government a veto power over any policy change. But the truth is that U.S. power is not limited to its being able to veto policy decisions it does not like. No country would dare oppose a move by the United States to radically cut the administrative budgets (by, say, 75% initially) and the number of personnel in the two organizations (to 600 personnel each, as in the case of USAID) if it wanted to do so. All it needs to do to get its way is to threaten to withhold its contributions to the two organizations. I can guarantee that immediately the interest rate at which the bank borrows in international capital markets would leap upward, paralyzing its lending operations.
The IMF and the World Bank are monuments to misguided economic thinking and policies that have brought much misery to the peoples of the Global South. They are institutions that no longer serve any purpose except to perpetuate and enlarge themselves. If Elon Musk and Donald Trump are really serious about radically downsizing bloated bureaucracies, they could not have better targets than the Bretton Woods twins.