

SUBSCRIBE TO OUR FREE NEWSLETTER
Daily news & progressive opinion—funded by the people, not the corporations—delivered straight to your inbox.
5
#000000
#FFFFFF
To donate by check, phone, or other method, see our More Ways to Give page.
Daily news & progressive opinion—funded by the people, not the corporations—delivered straight to your inbox.
While financiers often talk about the wonders of financial efficiency, they know that each merger, each leveraged buyout, and each stock buyback is likely to cause job loss.
I am writing to you from New Jersey, where approximately 250,000 people work in the financial sector. Many are employed by the most prosperous Wall Street banks’ hedge funds, and private equity and venture capital firms. Some of them are friends and neighbors in my home town, Montclair, and have over the years helped me understand how high finance actually works.
I fear they will not be happy with my new book, Wall Street’s War on Workers. It challenges the way Wall Street does business and critiques leveraged buyouts and stock buybacks. These practices have made a lot of money for my neighbors, but they have also led to millions of mass layoffs and enormous hardships for working people.
Not only financial pain. Studies show that following a layoff, a worker’s health suffers as well. The Department of Labor reports, “Being laid off from your job is one of the most traumatic events you can experience in life.”
It’s time for New Jersey financiers, and financiers everywhere, to curb mass layoffs and reconnect working people to a more stable economic future.
While financiers often talk about the wonders of financial efficiency, they know that each merger, each leveraged buyout, and each stock buyback is likely to cause job loss. As one friend put it, “After we do a merger, you really don’t need a bank on every corner.”
It’s well documented that Wall Street took down the Wayne, New Jersey-based Toys “R” Us. In 2006, KKR, Bain Capital, and Vornado purchased the company for $6.6 billion, financed by $5.3 billion of debt put onto the company’s books. This added approximately $400 million a year in debt-service costs to the company’s bottom line. These corporate raiders took management fees from the company, making the deal profitable for them but crippling Toys “R” Us. When the retailer filed for bankruptcy in 2017, 33,000 workers lost their jobs.
The slow demise of Bed, Bath, and Beyond, headquartered in Union, New Jersey, shows how a Wall Street-induced stock buyback binge cripples a company. Starting in 2004, Bed, Bath, and Beyond spent $11.8 billion on stock buybacks that, in the short term, boosted the company’s share price and enriched the Wall Street stock sellers who had pressured the company to buy back those shares. Even as the company struggled in 2022, it spent $230 million on stock buybacks while loading the company up with even more debt to finance them. Wall Street stock sellers were enriched, and so was upper management, which was compensated with stock options, but in the end the collapse of the company cost more than 32,000 workers their jobs.
This wasn’t isolated bad luck for these New Jersey firms. Researchers at California State Polytechnic University found that the bankruptcy rate for leveraged buyouts 10 years after was 20%, compared to just 2% for companies that weren’t leveraged buyout targets. Overall, a Harvard Business School study of thousands of leveraged buyouts between 1980 and 2013 shows that, on average, employment at bought-up firms shrank by 13%.
Is this the price of progress? Don’t mass layoffs help the economy move from low value-added jobs to high value-added jobs?
The data shows otherwise. For more than a generation working people and their children have been urged to develop the skills needed in the knowledge economy. Get into high tech, and the future is yours.
Until it isn’t.
Mass layoffs, often used to finance mammoth stock buybacks, are ripping through the booming high-tech sector. In 2022, more than 165,000 workers lost their jobs in high tech firms. In 2023, 263,000 were laid off. So far this year, another 74,000 workers have joined them, according to Layoffs.fyi. To repeat, these are boom years for the tech industry, but management wants to keep share prices high and the easiest way to do that is to cut jobs to pay for stock buybacks.
What can my friends and neighbors do about mass layoffs?
First, they could change Wall Street’s culture. Before firms were permitted to do leveraged buyouts and massive stock buybacks at will, shareholders, employees, and the community had roughly equal claims as corporate stakeholders. Executives of companies large and small were embarrassed to lay off their workers. It was considered a mark of failure. During recessions, layoffs might be needed temporarily, but not during good times. But those days of shared social values are long gone. Now, the first word associated with Wall Street by the average American is greed.
Next, they could support efforts to eliminate stock buybacks and greatly reduce the debt loads permitted in corporate acquisitions. Let companies make their money the old fashioned way, by making good products rather than manipulating their share price.
Finally, they should advocate for a simple rule change: Any corporation receiving government contracts or subsidies is prohibited from making compulsory layoffs. Taxpayers should not be funding corporations that lay off taxpayers. Instead, layoffs should be voluntary. Corporations taking government funds would have to encourage departures through negotiated payouts and benefits.
These steps are designed to discourage management from using layoffs as a financial tool, which since 1996 has affected at least 30 million workers and their families. These reforms also are designed to help our democratic society provide a modicum of job stability and therefore prevent the erosion of democracy.
It’s time for New Jersey financiers, and financiers everywhere, to curb mass layoffs and reconnect working people to a more stable economic future.
Falsely claiming that wage protections will drive up fares seems to be a tactic rideshare corporations use to pit drivers against passengers and obscure a massive transfer of wealth.
If you’ve taken an Uber ride recently, you’ve probably noticed it cost a lot more than a few years ago. Why is that? We conducted the largest-ever study of rideshare fares to find out, and discovered a story of gaslighting and corporate greed that squeezes rideshare drivers and riders alike, while funneling our money to banks and billionaires.
This month, Minneapolis passed an ordinance requiring rideshare corporations to pay drivers at least $1.40 per mile and 51 cents per minute. In a desperate attempt to block the pay floor, Uber and Lyft are threatening to leave the city, claiming that such a requirement would make rides too expensive for residents. This argument—that higher driver pay would force big fare hikes—is one of Uber and Lyft’s favorite scare tactics. As drivers across the country have protested poverty wages and organized for better pay, the rideshare giants have trotted out this line again and again—in Connecticut, Chicago, New York, and Seattle, to name just a few.
We decided to test that claim. Our team analyzed over a billion rideshare trips, comparing four years of data in Chicago and New York. These are two of the biggest rideshare markets in the U.S. and the only two American cities that make rideshare corporations report detailed trip data. In New York City, drivers overcame Uber’s fearmongering and won a minimum pay standard that took effect in February 2019. In Chicago, drivers are organizing but haven’t yet won pay protections.
Letting rideshare corporations bully and bamboozle to get their way harms all of us.
If Uber’s argument was true, fares should have gone up more in New York after the pay standard took effect. In fact, the opposite happened. Over the four years we studied, Uber and Lyft raised fares by 54% in Chicago, where drivers have no pay protections. In New York, they only increased fares by 36%. The reality just doesn’t match Uber’s scare tactics.
So if fares went up more in the city without a pay floor, what’s causing these big price hikes? We looked at many possible explanations, but only one fits the data: pressure from Wall Street.
For years, Uber used money from the likes of Goldman Sachs, BlackRock, and Jeff Bezos to subsidize cheap rides and decent pay. Now that Uber dominates the market, its investors are demanding their cut. As the corporation has faced increasing calls to turn a profit, it has jacked up fares and cut driver pay.
The strategy is working: just last month, Uber reported an annual profit for the first time ever—and promptly announced plans to give $7 billion to shareholders.
Letting rideshare corporations bully and bamboozle to get their way harms all of us. Riders are forced to pay more to get around, while drivers have to work long hours and still struggle to cover the bills. Falsely claiming that wage protections will drive up fares seems to be a tactic to pit drivers against passengers and obscure this massive transfer of wealth to Wall Street.
The good news is that communities are no longer falling for Uber’s scare tactics. In Minneapolis, the city council stood with the city’s mostly Black and immigrant drivers instead of giving in to Uber’s bullying. And in Chicago, drivers are organizing for an ordinance setting a living wage and protections against unfair deactivations—and have the support of a majority of the city council.
These fights are far from over (already Uber and Lyft are turning to the Minnesota state legislature, which could pass a law banning the Minneapolis ordinance from going into effect). But when drivers and communities stand together, these cities are showing we can say no to Uber’s bullying, ensure drivers are paid enough to provide for their families, and shape a transportation system that serves us instead of Wall Street.
Stock buybacks have become the main goal in life for corporate executives and activist stock sellers. And this sickness is spreading.
The institution casting a broad shadow over the UAW strike against the Big Three automakers is Wall Street. GM workers and those of us who have longed for the production of high-quality and affordable electric cars to combat global warming could not have invented a more damning story than the reality of how the financiers fleeced us.
The story starts back in 2008, when the auto industry was going bankrupt due to the financial crisis that Wall Street’s reckless gambling had caused. Six million workers lost their jobs in six months through no fault of their own. Motor vehicle sales fell by nearly 40 percent and as bankruptcies loomed, another three million more auto industry jobs were at risk.
The federal government intervened with a massive bailout, eventually loaning the companies more than $81 billion. To reorganize the industry, the government wanted more financial expertise. So where did it turn? To Wall Street! The financial foxes were hired to overhaul the hen house.
The UAW strike is illuminating a type of financial insanity that has gripped our economy.
To lead 1990s Presidential Task Force on the Auto Industry, the Obama administration recruited Steve Rattner, a Wall Street investment banker, whose net worth was $188 million. (A year later, we learned a bit how Rattner became so wealthy. He was charged by the Security and Exchange Commission in a pay-to-play scheme to obtain investments from New York’s largest pension fund and was forced to pay a $10 million fine.)
Rattner, dubbed the Car Czar by the media, recruited a 37-year-old Wall Street “turn around” expert, Harry J. Wilson, to guide GM to solvency. Wilson joined the federal task force, he claimed, out of a lofty sense of noblesse oblige. As he wrote to Rattner, “I have a very deep interest in public service, particularly given the good fortune I have enjoyed in my own life…” Wilson’s good fortune continued to follow him to GM. At taxpayer expense he would learn everything there was to learn about GM and then use it to fleece the company a few years later.
The bailout’s net cost to US taxpayers was $11. 2 billion, while autoworkers absorbed $11 billion in reduced labor costs. In exchange for the survival of their jobs, workers were saddled with a bitter decade-long wage freeze, the elimination of long-held cost-of-living adjustments, and reduced wages and benefits for new hires. This led to a 19.3 percent loss of real wages (after accounting for inflation) from 2008 to 2022). The UAW’s current request for a sizable wage increase is to make up for more than a decade of lost ground.
From a financial perspective, the bailout was a success. GM, after losing $38.5 billion in 2008-09, earned $16.7 billion in 2010. By 2014, GM had $29.5 billion in cash on hand, a tidy sum with which to enter the budding competitive race against new firms like Tesla to produce affordable electric vehicles.
But from Harry J. Wilson’s perspective, the GM hen house had far too many eggs. After returning to Wall Street from public service, he set his sights on GM’s cash.
First, Wilson purchased 30,000 GM shares worth about $1.1 million at the time. His goal was to press GM to conduct a stock buyback as soon as possible. (A stock buyback in effect moves cash from the corporation to stock-sellers. By reducing the number of outstanding shares, it drives up the price of each share so that Harry and other large financial entities can cash out quickly and with sizable profits.)
He then cut a deal with billionaire David Tepper, whose Appaloosa hedge fund owned $300 million in GM stock. Wilson also worked out arrangements with several other hedge funds, including Taconic Capital, which owned another $120 million worth of GM shares. In each arrangement, Wilson would receive a performance fee and a share of the profits should he succeed in forcing a GM stock buyback. The hedge fund group also agreed to cover up to $1 million of expenses incurred by Wilson over the next year.
Wilson then pushed GM to commit to an $8 billion stock buyback. When GM announced buybacks shortly thereafter Wilson and his Wall Street backers did even better than expected. GM went on to announce a $5 billion in buybacks in March 2015, another $4 billion later that year, and another $5 billion in 2017.
The business of American business is to create stock buybacks for top executives and for looting investors.
So, while Tesla was straining to sell 50,000 electric cars in 2015, GM was busily opening up a new ultra-luxury production line of stock buybacks that enriched Harry J Wilson and his Wall Street compatriots, and GM executives who were compensated with stock incentives. In the last 12 years, GM has spent $21 billion on stock buybacks rather than additional investments in greener vehicles. Not coincidently, in 2022 GM sold 39,096 electric cars, while Tesla produced 32 times more ( 1.31 million).
GM CEO Mary Barra has reaped an average of $41.8 million a year for the past four years in total compensation. “My compensation,” she said, “92 percent of it is based on the performance of the company,” She means that 92 percent of her income comes from stock incentives. The “performance of the company” is measured for compensation purposes by its stock price, which she is able to manipulate and raise through stock buybacks. The more GM engages in stock buybacks the higher the price of their shares, and therefore, the higher the pay of those executives who are paid with stock incentives tied to the price of the stock.
The strike is shining a bright light on a type of financial insanity that has gripped our economy. Stock buybacks have become the main goal in life for corporate executives and activist stock-sellers like Harry J. Wilson and his hedge fund raiders. Their looting adds nothing of value to their companies, yet this sickness is spreading. In 1982 only 2 percent of corporate profits were used for stock buybacks. Now, nearly 70 percent of all corporate profits go to stock buybacks instead of research and development, environmental controls, and worker health and safety. And certainly not to provide job security nor livable wages. Increasingly the business of American business is not to make things and provide services, but instead to create stock buybacks to benefit top executives and looting stock-sellers.
Hopefully, the UAW strike will move us one step closer to outlawing any and all stock buybacks.
Billions spent on buybacks means billions less not only for workers’ wages but also for developing high-quality, affordable electric vehicles to forge the transition to a green, sustainable economy.
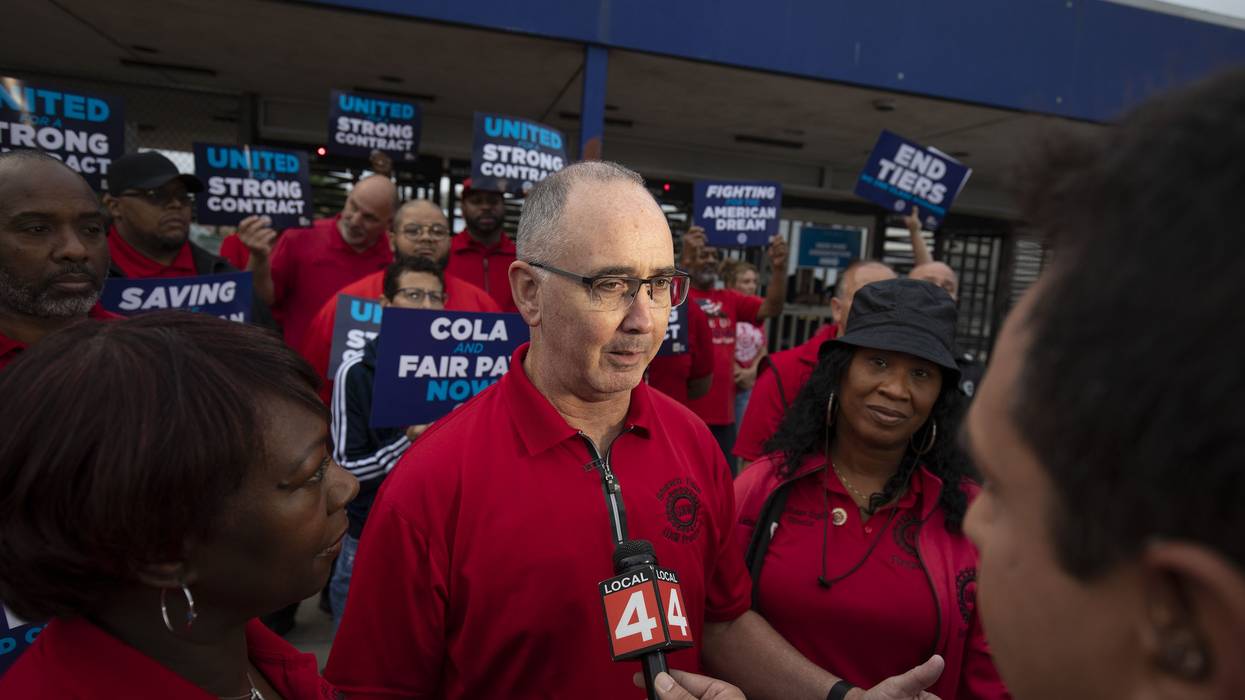
The United Auto Workers are striking against General Motors, Ford and Stellantis — the Big Three — to make up for lost ground. Since 2003 the average hourly wages of UAW production workers have declined by 30%, adjusting for inflation. A large portion of those losses came when the autoworkers were compelled to help bail out GM in 2008 as it went bankrupt.
The worker concessions included a decadelong wage freeze for those hired before 2007, lower pay and benefits for new hires including the elimination of defined pensions, and the shift of the healthcare benefit fund from the company to the union. The concessions also permitted the use of lower-paid temp workers who could earn $18 an hour working alongside a longtime employee earning $32 per hour while doing the same tasks.
The union wants to end these concessions while also gaining a 40% wage increase over the next four years to match the 40% compensation increases received by Big Three chief executives over the last four years. The UAW has said that if contract negotiations don’t advance by Friday, it will expand the strike beyond the three plants currently targeted.
The federal government’s $80-billion bailout and worker concessions saved GM. Many who supported the bailout expected the company, when it returned to profitability, to invest heavily in electric vehicle research, development and production: The taxpayers saved GM, so now GM should help ameliorate global warming that harms us all.
But Wall Street had other ideas. In 2015, it swooped in to capture these newly minted profits by pressuring GM management to conduct a stock buyback of $8 billion. Made possible by the Securities and Exchange Commission’s Rule 10b-18, put in place in 1982, buybacks are a method of profit extraction allowing companies to use their profits to buy back their own shares, thus increasing the value of all outstanding shares. Hedge funds and the like take large stock positions in companies, demand buybacks that quickly increase the price of their shares and then cash out with significant profits.
This pattern happened with GM in the years following the bailout: The giant hedge fund Appaloosa Management joined with other funds to buy up 2.1% of GM shares. These efforts succeeded and then some: GM announced $5 billion in buybacks in March 2015, another $4 billion later that year and another $5 billion in 2017. At the same time, the company planned to cut 14,000 jobs and idle five automotive plants.
In addition to rewarding Wall Street share-sellers, stock buybacks also increase the pay of top corporate executives. As of 2021, stock awards and options made up 82% of total CEO compensation. Approximately 75% of all non-financial corporate profits went to stock buybacks in the decade after the automaker bailout. In the 12 months ending in March 2022, buybacks transferred $1.5 trillion of corporate profits to share-sellers. Stellantis, which purchased Chrysler, Fiat, and Peugeot in 2021, even had the audacity to announce a $1.6-billion stock buyback in February ahead of negotiations with the UAW.
Today none of the Big Three are worried about bankruptcy: Collectively they are expected to earn $32 billion in profits in 2023. The automakers claim those profits are desperately needed to make the historic shift to electric vehicles and fend off their nonunion competitors such as Tesla. Meeting the UAW demands, they claim, would cut those investments while forcing the companies to move more production to lower-wage areas here and abroad.
What they neglect to say is that Wall Street’s shadow also hovers over these negotiations. As Stellantis made crystal-clear when it authorized stock buybacks this year, the industry is more than willing to divert badly needed investment funds into the pockets of top executives and powerful Wall Street firms.
A stock buyback, of course, does not strengthen the company. It does not create investment in new plants and equipment. It does not upgrade the skills of the workforce. And it does not improve health and safety or increase research and development to mitigate climate change. In fact, it decidedly detracts from all of these critical functions by eating up the money to fund them. Billions spent on buybacks means billions less not only for workers’ wages but also for developing high-quality, affordable electric vehicles to forge the transition to a green, sustainable economy.
For the first time in a generation the labor movement is held in high esteem by the American public. It is widely understood that working people need the protections only collective bargaining can provide. This puts unions like the UAW at the forefront of the struggle to protect jobs and the environment. Perhaps these difficult negotiations can help us all realize just how much stock buybacks threaten both economic fairness and the health of our climate.
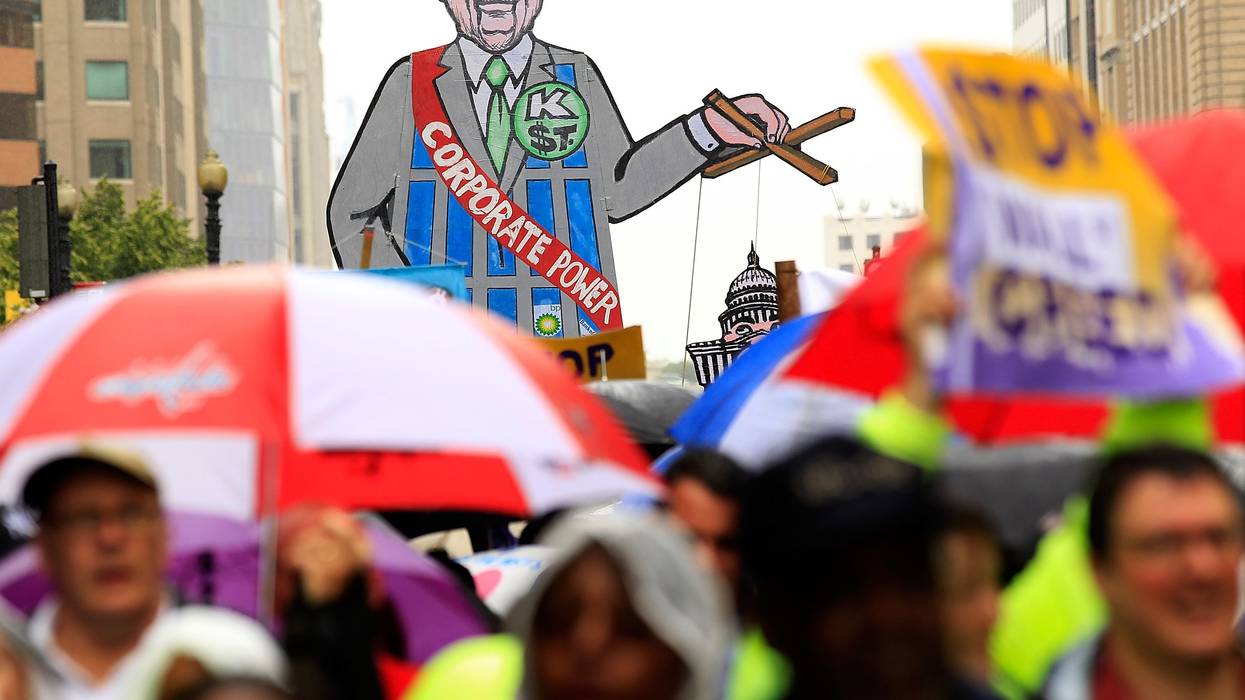
As philosophers from Socrates to Jesus to Adam Smith have told us over and over: unregulated greed always ends up enriching the few while devastating the rest of society.
The failure of the Silicon Valley Bank (SVB) shows us, once again, that unrestrained greed isn’t good. For even modest greed to have a positive effect in society, it must be regulated.
The CEO of SVB didn’t like the regulations imposed after the 2008 financial meltdown by Congress’ Dodd-Frank legislation, and spent over a half-million dollars bribing…er, influencing…legislators (legalized by 5 Republicans on the Supreme Court) to change the law and exempt his and other smaller, regional banks from what he argued was the heavy hand of government.
While SVB and other smaller banks were generally prosperous and profitable, many wanted to escape from the regulations Congress imposed to protect both depositors and the economy, so they spread some money around Washington DC. Donald Trump then enthusiastically signed the deregulation of smaller banks like SVB into law in 2018.
As Senator Bernie Sanders noted this weekend:
“Let's be clear. The failure of Silicon Valley Bank is a direct result of an absurd 2018 bank deregulation bill signed by Donald Trump that I strongly opposed. Five years ago, the Republican Director of the Congressional Budget Office released a report finding that this legislation would increase the likelihood that a large financial firm with assets of between $100 billion and $250 billion would fail.”
Five years later — predictably — the bank went into receivership and people who’d put their money in its trust were looking at substantial losses while, once again, confidence in the entire system is shaken.
At New York’s First Republic Bank, people were standing in line as the weekend began, suggesting there may be a full-blown run on that bank today. And New York’s Signature Bank was just closed by banking regulators.
The CEO of SVB had pulled millions out just two weeks before, money that Congressman Ro Khanna says should be clawed back and used to make depositors whole:
“There should be a clawback of any of that money,” Khanna told The Washington Post. “It should be going to the depositors.”
Politicians and op-ed writers tight with banksters spent the weekend, of course, demanding government action and bailouts, like in 1987 and 2008. And this morning, President Biden announced he’s going to do it by bending the rules at FDIC. Frankly, he had little choice.
The CEO’s greed didn’t work out well for average taxpayers — who ultimately must backstop the FDIC if this spreads — and bank customers.
These same banksters are the first types of people to tell student loan borrowers that if they can’t repay their debts they need “discipline,” to suck it up, reduce their standard of living, and to “learn the lesson of responsibility.”
But when their own stupid decisions — in this case, investing in largely illiquid long-term bonds — come back to haunt them, they stand before Congress with their hands out.
The era from the 1850s through the 1920s was punctuated by periodic greed-driven bank failures and a lack of federal response to them. One of the biggest of those crashes presaged — some scholars argue, triggered — the Civil War.
Before running for public office Abraham Lincoln was a lawyer in private practice working for the railroads. On August 12, 1857, he was paid $4800 in a check, which he deposited and then converted to cash on August 31. That was fortunate for Lincoln, because just over a month later, in the Great Panic of October 1857, both the bank and the railroad were “forced to suspend payment.”
Of the 66 banks in Illinois, The Central Illinois Gazette (Champagne) reported that by the following April, 27 of them had gone into liquidation. It was a depression so vast that the Chicago Democratic Press declared at its start, the week of Sept. 30, 1857, “The financial pressure now prevailing in the country has no parallel in our business history.”
Unregulated greed wasn’t good back then, either: over 600,000 people died in the Civil War that bank crash contributed to.
Fast forward sixty years.
During the 1920s, according to the Federal Deposit Insurance Corporation (FDIC), “On average, more than 600 banks failed each year between 1921 and 1929.” In the process, billions of dollars were lost to depositors, mostly farmers, working people, and small businesses who’d been locked out of the big banks and didn’t have the resources to lobby Congress.
To make matters worse, because the Republican administrations of Harding, Coolidge, and Hoover all believed bank regulation was a bad thing that interfered with the greed-driven “invisible hand of the marketplace,” each allowed the trend to continue until the entire system collapsed in the 1929-1933 era.
That was another era, almost 100 years before ours, that proved how unregulated greed could damage our nation and create widespread misery (except among the greedy).
In January and February of 1932, respectively, Congress created the Reconstruction Finance Corporation (RFC) and the Glass-Steagall Act, regulating banks to prevent their rich owners from continuing to steal depositors’ cash and then walk away from the banks they’d plundered.
President Franklin Roosevelt, who took office in March of 1933, imposed further stiff regulations on banks and Wall Street, creating the Securities and Exchange Commission (SEC) and putting Joe Kennedy in charge of it.
The late Gloria Swanson, who knew Kennedy well and intensely disliked him (he’d robbed and exploited her), told me over one of our many dinners in her New York apartment back in the 1980s that FDR told her he’d appointed Kennedy because, “It takes a crook to catch a crook.”
And FDR was going after the greedy crooks in a big way.
Between Glass-Steagal and the SEC, banking became a boring if reliably profitable business from the 1930s to the 1980s.
The nation prospered. The middle class grew. The banksters’ greed was hemmed in by FDR’s regulations, then kept there through the administrations of Truman, Eisenhower, Kennedy, Johnson, Ford, and Carter. Bank directors and executives did well, but few were buying their own private jets.
Then, President Reagan, as part of his neoliberal “greed is good” agenda, experimented with bank deregulation by lifting many rules governing the operation of Savings and Loan institutions.
They’d been created in 1932 with the Federal Home Loan Act, which heavily regulated the industry and made it functionally subordinate to commercial banks.
But in 1982, Reagan pushed through the Garn-St. Germain Depository Institutions Act, eliminating previous S&L loan-to-value ratios and interest rate caps while killing their main oversight, Regulation Q.
Soon S&Ls were gambling with junk bonds and risky commercial real estate, leading over 1000 of them (almost a third of all S&Ls in the nation) to crash and burn.
Their greedy CEOs and senior executives made off with billions, leaving depositors in the lurch and the Federal government to clean up the mess. Once again, deregulating greed ended up costing the nation hundreds of billions while making a small group of S&L hustlers richer than the pharaohs.
In 1999, Republicans and a few neoliberal Democrats took another run at deregulating banks themselves, spurred into action by a pile of campaign cash made legal by Republicans on the Supreme Court when Lewis Powell wrote the 1978 opinion in First National Bank v Bellotti, writing explicitly that corporations were “persons” entitled to use their “First Amendment-protected free speech” (money) to influence politicians.
Deregulation would both increase bank profits while keeping the banking sector safe, we were told that year, because no banker or stockbroker in his right mind would risk being “embarrassed” by taking such big chances that a misstep could wipe out large sectors of the nation’s economy.
Greed, they told us, was self-regulating. Predictably, it didn’t quite work out that way.
Republican Senator Phil Gramm made that “self-regulating” point on the floor of the Senate in 1999 when selling the end of the 1933 Glass-Steagall law that prevented checkbook banks from using their depositors’ money to gamble in the stock, bond, and real estate markets.
Bought-off legislators fattened their campaign coffers while banksters started gambling and became billionaires. And, of course, it led us straight to the Bush Crash of 2008 when the entire system seized up and you and I bailed out Wall Street with trillions of dollars, hundreds of billions of which the banksters simply pocketed for themselves and their big business buddies as loans and massive bonuses.
Greed paid off for them, although you and I are still paying for it with our taxes via the national debt.
As with so many things, a kernel of truth — in this case about greed and self-interest — has been twisted into a gamed and rigged system by the morbidly rich. They’re quick to quote from the first chapter of Adam Smith’s 1776 classic The Wealth of Nations:
“It is not from the benevolence of the butcher, the brewer, or the baker that we expect our dinner, but from their regard to their own interest. We address ourselves, not to their humanity, but to their self-love, and never talk to them of our own necessities, but of their advantages. Nobody but a beggar chooses to depend chiefly upon the benevolence of his fellow-citizens.”
While true, advocates of deregulation completely ignore its corollary, expressed in the second chapter of Smith’s Theory of Moral Sentiments, in which he argues:
“Man is considered as moral because he is regarded as an accountable being. But an accountable being, as the word expresses, is a being that must give an account of its actions to some other, and that consequently must regulate them according to the good liking of this other.”
When Senators Mike Crapo (R-Idaho) and Joe Manchin (D-WV) pushed their 2018 Economic Growth, Regulatory Relief, and Consumer Protection Act, dubbed by Elizabeth Warren and others as the Bank Lobbyist Act, many argued it would lead to more bank consolidations (it did) and let smaller banks like SVB take risks that could endanger depositors (they did).
Senator Warren noted on Twitter at the time:
“The #BankLobbyistAct takes 25 of the 40 biggest banks in the country off the watch list for more federal oversight. It weakens consumer protections on mortgages — and makes it harder to fight racial discrimination in housing,” adding that the legislation would “be paving the way for the next big crash.”
Unregulated greed, she predicted, would lead to disastrous outcomes.
And here we are. Whether the failure of the Silicon Valley Bank (SVB) will spark a wider contagion or just be a two-week story illustrating the stupidity of deregulating and trusting billionaire banksters to do the right thing is, as yet, unknown.
But the principle is known. When money, power, or political advantage are at stake, a small number of unscrupulous (sometimes called “sociopathic”) individuals will say or do any and everything they can to game the system for themselves to keep everybody else out.
It may be selling opioids that kill hundreds of thousands of Americans; or poisoning children’s metabolisms with processed, plastic-packaged, forever-chemical-laced “food” that leads to cancer, obesity, and diabetes; or pushing cigarettes or opposing wind and solar farms. There’s always somebody willing to sell their soul for the right price, and somebody else who can afford to pay that price.
We’ve all seen greed working in real time. My father was killed — knowingly — by the asbestos industry and my brother was killed with full knowledge and intention by the tobacco industry. If there’s not such a similar story in your life, you’re an outlier.
And what we all experience on a personal level is amplified a million times when a single greedy person seizes the power to help or destroy millions of lives, like the CEO of a giant employer that is fighting unionization, safety, or environmental regulation.
Often, these are the most high-functioning and well-educated/well-connected sociopaths among us…and the good ones (as in those “good” enough to make billions but only pay 3% income tax) are particularly successful at selling their own personalities: this is the compounding overlay of narcissism.
Donald Trump is its poster child.
Can we stop the sociopaths, the greed-heads, from continuing their destruction of our food supply, our housing stock, and our environment/climate?
It’s a fight, but the greed side literally can mobilize trillions, if necessary. Still, the human and intrinsic love of democracy and fairness mean the outcome is, at this moment, up in the air.
What we do know, however — as philosophers from Socrates to Jesus to Adam Smith have told us over and over — is that unregulated greed always ends up enriching the few while devastating the rest of society.
And, as we learned from the Iroquois and I write about in my next book, The Hidden History of American Democracy, working on behalf of and protecting society from greedy predators should be the first job of every government.

"When rail companies reduced their workforce by 30% under orders from Wall Street, bad things happen—like the dangerous derailments in Ohio and Michigan," said Sen. Bernie Sanders.
Sen. Bernie Sanders on Thursday connected the spate of recent train derailments in the United States to Wall Street-backed cost-cutting and other policy decisions that have decimated the rail industry's workforce and compromised safety for the sake of larger profits.
"When rail companies reduced their workforce by 30% under orders from Wall Street, bad things happen—like the dangerous derailments in Ohio and Michigan," Sanders (I-Vt.), the chair of the Senate Health, Education, Labor, and Pensions Committee, wrote on social media. "Rail companies not only must provide seven days of paid sick leave to workers, they must stop skimping on safety measures."
The toxic crash in East Palestine, Ohio has drawn greater scrutiny to a widely adopted model known as
Precision Scheduled Railroading (PSR), which rail workers have said is at least partially to blame for the derailment and broader crises across the industry. Under PSR, The New York Times explains, rail companies focus on "running rigid, consistent schedules, streamlining processes and routes, and cutting back on equipment and employees."
According to the
U.S. Surface Transportation Board, Class I railroads—including Norfolk Southern, the company at the center of the derailments in Ohio and Michigan—have collectively slashed their workforces by 29% over the past six years, terminating roughly 45,000 employees including safety personnel.
An
analysis conducted by USA Today earlier this month found that while "catastrophic events involving trains and chemicals may be uncommon, [hazardous material] cargo violations caught during inspections of rail shippers and operators appear to be climbing."
"Over the last five years, federal inspectors have flagged 36% more hazmat violations compared with the five years prior—and fines for those are up 16%.," the outlet noted.
One Norfolk Southern employee
told Motherboard this week that train derailments and other rail disasters are "going to keep happening if regulators continue to allow this business model to ravage our nation's freight rail system in the pursuit of profit."
"My fear is that these corporations have so much money and political influence that nothing is going to change," the worker added.
"Secretary Pete Buttigieg must heed rail workers' calls and implement common-sense regulations to ensure this never happens again."
In addition to fighting to deny their increasingly exhausted workers paid sick leave, Norfolk Southern and other hugely profitable Class I rail carriers have lobbied aggressively against regulatory changes aimed at enhancing industry safety practices.
The Norfolk Southern train cars that derailed in East Palestine were not being regulated as hazardous, despite carrying a known carcinogen that was later released into the air.
"After rail industry donors delivered more than $6 million to GOP campaigns, the Trump administration—backed by rail lobbyists and Senate Republicans—rescinded part of [a] rule aimed at making better braking systems widespread on the nation's rails," The Lever reported earlier this month. "Specifically, regulators killed provisions requiring rail cars carrying hazardous flammable materials to be equipped with electronic braking systems to stop trains more quickly than conventional air brakes."
In the wake of the East Palestine derailment, progressive lawmakers have ramped up pressure on U.S. Transportation Secretary Pete Buttigieg to take steps to more strictly regulate railroads as he suggests—incorrectly—that federal law is preventing him from doing so.
"The train derailment in East Palestine is an ecological and humanitarian disaster caused by a predatory rail industry that constantly puts profit over people," Rep. Cori Bush (D-Mo.) said Thursday. "Secretary Pete Buttigieg must heed rail workers' calls and implement common-sense regulations to ensure this never happens again."

A new analysis out Wednesday estimates that if the federal minimum wage had grown at the same rate as Wall Street bonuses over the past three and a half decades, it would currently be $61.75 an hour instead of $7.25.
"Millions of essential workers continue to earn poverty wages, while the reckless bonus culture is alive and well on Wall Street."
According to fresh data from the New York State Comptroller, the average bonus dished out to Wall Street employees jumped 20% to a record $257,500 in 2021 as big banks reported huge profits despite widespread havoc caused by the coronavirus pandemic. Last year's average Wall Street bonus was the highest since 2006, prior to the Great Recession.
The comptroller's office points out that while the securities industry comprises just 5% of private-sector employment in New York City, it makes up one-fifth of total private-sector wages.
Taking the new figures into account, Sarah Anderson of the Institute for Policy Studies notes in a report that the average Wall Street bonus has soared by 1,743% since 1985.
"By contrast, typical American workers lost earnings power in 2021," Anderson writes, noting that high inflation has eroded the modest wage gains seen by ordinary people. "Average weekly earnings for all U.S. private-sector employees rose by only 2% between January 2021 and January 2022, according to the Bureau of Labor Statistics."
"These jaw-dropping numbers are just the latest evidence of unequal sacrifice under the pandemic," Anderson adds. "While ordinary workers are struggling with rising costs for basic essentials, Wall Street bankers have seen their bonuses rise further into the stratosphere."
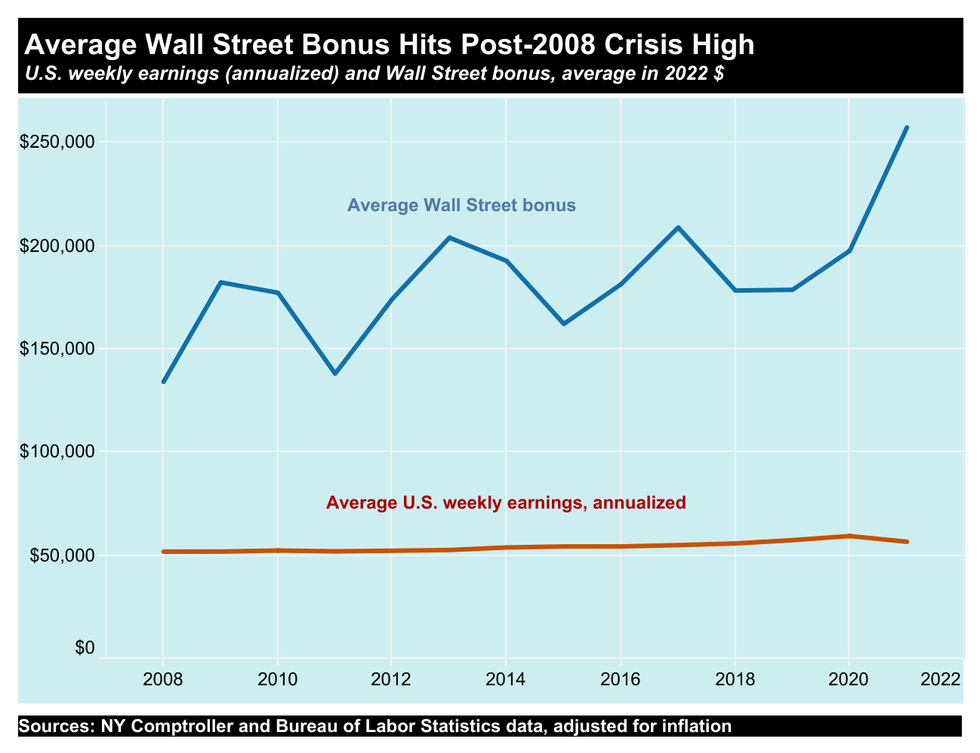
Anderson argues that Wall Street bonuses have been soaring in recent years partly because Section 956 of the Dodd-Frank Act--a financial reform measure enacted in the wake of the 2008 crash--has never been implemented.
"Powerful Wall Street lobbyists have succeeded in blocking Section 956... which prohibits large financial institutions from awarding pay packages that encourage 'inappropriate risks,'" Anderson writes. "Regulators were supposed to implement this new rule within nine months of the law's passage but have dragged their feet--despite widespread recognition that these bonuses encouraged the high-risk behaviors that led to the 2008 financial crisis, costing millions of Americans their homes and livelihoods."
"In contrast to the Wall Street lobbyists, advocates for the working poor have seen their efforts to raise the federal minimum wage and secure other important worker benefits stalled in Congress," she continues. "Due to Washington inaction, millions of essential workers continue to earn poverty wages, while the reckless bonus culture is alive and well on Wall Street."

While low-wage workers are still waiting for a raise in the minimum wage, Wall Street employees enjoyed a 10 percent bump in their bonuses in the first year of the pandemic, according to new data from the New York State Comptroller.
Wall Street pay v. the minimum wage

Wall Street bonuses and gender and racial inequality
The rapid increase in Wall Street bonuses over the past several decades has contributed to gender and racial inequality, since workers at the low end of the wage scale are disproportionately people of color and women, while the lucrative financial industry is overwhelmingly white and male, particularly at the upper echelons.


Washington Inaction on Wall Street Pay and Minimum Wage
Since 2010, the year the Dodd-Frank financial reform became law, regulators have failed to implement that law's Wall Street pay restrictions and Congress has failed to raise the minimum wage. These two failures speak volumes about who has influence in Washington--and who does not.
Powerful Wall Street lobbyists have succeeded in blocking Section 956 of the 2010 Dodd-Frank financial reform legislation, which prohibits financial industry pay packages that encourage "inappropriate risks." Regulators were supposed to implement this new rule within nine months of the law's passage but have dragged their feet--despite widespread recognition that these bonuses encouraged the high-risk behaviors that led to the 2008 financial crisis, costing millions of Americans their homes and livelihoods.
In 2011, regulators issued a proposed rule that did not go far enough to prevent the type of behavior that led to the 2008 crash. As spelled out in detail in Institute for Policy Studies comments to the SEC, the proposed rule fell short in several areas, including overly lenient bonus deferrals, weak stock-based pay restrictions, and enforcement proposals that leave too much discretion to bank managers. While regulators responded to criticism by agreeing to issue a new proposal, this work was not completed before the end of the Obama administration.
During the Trump administration, regulators put the issue on a back burner as Republicans maneuvered to get rid of the Wall Street pay restrictions altogether. In 2017, the U.S. House of Representatives passed the Financial CHOICE Act, which would've repealed most of the Dodd-Frank reform package, including the Wall Street pay provision. Due to Democratic opposition in the Senate, the Wall Street deregulation bill that was adopted was significantly scaled back and did not affect financial industry pay.
Congress Should Build on the Modest Executive Pay Reform in the American Rescue Plan
In the American Rescue Plan Act passed in March 2021, Congress made a step forward in executive pay reform by expanding corporate tax deductibility limits on such compensation. Under the law, corporations will not be able to deduct any compensation exceeding $1 million paid to the 10 highest compensated employees, up from the current number of five executives. This is an important step towards eliminating taxpayer subsidies for excessive compensation. However, particularly for Wall Street firms, limiting the deductibility cap to just 10 employees is insufficient.
If average compensation for the 182,100 securities industry employees in New York is more than $400,000, then many thousands of Wall Street employees likely make more than $1 million. This would include high-powered traders with significant power over the stability of our financial system. Senators Jack Reed and Richard Blumenthal and Rep. Lloyd Doggett have introduced a bill that would expand the $1 million deductibility cap to all employees of publicly held corporations.
Another recently introduced bill, the Tax Excessive CEO Pay Act, would go further to incentivize firms to rein in pay at the top and lift up wages at the bottom. This proposal would increase the tax rate on corporations with large gaps between CEO and median worker pay, with the highest rate increase of five percentage points hitting companies with pay ratios of 500 to 1 or more.
In the new political landscape, lawmakers have a chance to end the Washington gridlock that has kept the federal minimum wage a poverty wage, while allowing the reckless bonus culture to continue to flourish on Wall Street--even during a pandemic.
Inequality is shaping the 2016 U.S. presidential election, as voters disillusioned by the financial crisis and Wall Street greed increasingly turn to populist candidates like Bernie Sanders, who has made economic inequality a central platform of his campaign, Nobel Prize-winning economist Joseph Stiglitz said on Wednesday.
"There are a lot of people that are described as angry and they finally figured out that they're not doing very well," Bloomberg reports Stiglitz as saying during an event at the Resolution Foundation, a London-based research group. "They're not doing as well as their parents; some Americans aren't doing as well as their grandparents."
"Americans have seen lots of injustices--people were thrown out of their houses that didn't owe money, and none of the bankers were held accountable" for their roles in the financial crisis, Stiglitz said. "I think that really has motivated the anger across the spectrum."
Stiglitz, a professor at Columbia University, told Democracy Now! in a December interview that "we're a wealthy-enough economy that we should be able to provide the basic requisites of a middle-class lifestyle for all Americans."
"[T]he question is whether the United States is rich enough to be able to make sure that everyone has a basic right to healthcare, family leave, parental, you know, sick leave--we are exceptional--whether we are a society that can tolerate--that should tolerate the levels of inequality that we have," Stiglitz said at the time. "I think Bernie Sanders is right about that."
On Wednesday, Stiglitz pointed out that 91 percent of economic gains made since the 2008 recession went to the top one percent of earners, while the minimum wage has failed to keep up with the pace of inflation by more than 60 years.
"The American economy is a failed economy," he said. "We have to once again rewrite the rules of the economy for the 21st century."
Four people who have been at the center of some of the nation's biggest Wall Street scandals have come together to send a message to the 2016 presidential candidates: Pledge to stand against Wall Street fraud and corruption - not just with words, but with the kind of actions that Americans have long expected but have yet to see.
The four veterans of battles with banksters - Gary J. Aguirre, William K. Black, Richard M. Bowen III and Michael Winston - on Thursday called on the candidates to not take contributions from financial companies or officers that have been charged with fraud, particularly related to the 2008 financial meltdown. They have also outlined a set of actions that they say will "restore the rule of law" on Wall Street. They have formed a new organization, Bank Whistleblowers United, to move that agenda forward.
"We use the f-word a lot," said Black, who came into national prominence for his role in exposing the "Keating Five" savings-and-loan senatorial scandal in 1989, "the five-letter word, 'fraud,' that you are supposed to be able to say in polite company."
That word, he said, is central to the issue these whistleblowers are concerned about: the fact that regulators and prosecutors have too often in the wake of the financial crash given a pass to banks and other financial institutions that profited from deception and dissembling.
Black recalled that during the era of the savings-and-loan scandal, when the federal government brought an action involving a financial institution "we actually spelled out in the English language what had happened." The news media echoed that language, and in the glare of that disclosure "the politicians who took political contributions from those institutions rushed to return the contributions or to donate them to charity."
In today's era of no-blame settlements and obfuscatory language, "that never happens now," Black said.
Nonetheless, people running for office have no excuse. It is clear that the financial meltdown was a consequence of actions that done by individuals rather than Wall Street institutions would likely have landed those persons behind bars. The biographies of the founding members of the Bank Whistleblowers United make that clear.
Bowen, for example, was at Citigroup when in 2006 he saw first-hand how the bank was issuing large numbers of subprime mortgages and then selling bundles of those mortgages on the securities market. His warnings that the deals violated bank and regulatory standards not only went unheeded; he was fired for speaking out. His experience, however, was probed by the Financial Crisis Inquiry Commission, which was created by Congress to document the causes of the Wall Street meltdown and make recommendations. It was also featured in a powerful "60 Minutes" segment.
Winston had a similar experience as an executive in the mortgage unit at the now-defunct Countrywide Financial. He recalled being told by a fellow senior executive of the impetus from the very top of the company to approve mortgages by anyone, regardless of qualification. "If they can fog a mirror, we'll give them a loan," he was told. With the complicity of a bond-rating agency that allowed the mortgages to be bundled as high-quality securities, Countrywide made billions - until the House of Cards crashed, taking with it people who found their homes foreclosed and communities economically devastated. Winston, too, was fired after flagging fraudulent practices he saw and for refusing a direct order to disseminate false information on behalf of the company. For a brief time he found exoneration when a jury ruled in his favor in a California county superior court suit against Bank of America, which absorbed Countrywide during the depths of the financial crisis. The bank succeeded, however, in getting that verdict overturned in an appeals court because critics found highly irregular and suspect.
Aguirre experienced Wall Street corruption from the perspective of a regulatory agency, as a Securities and Exchange Commission attorney. While heading an insider trading investigation of Pequot Capital Management, formerly the world's largest hedge fund, Aguirre resisted his supervisor's demands to give preferential treatment to a Wall Street titan involved in the case. He was fired for "insubordination," but he would later prove to the satisfaction of two Senate committees, a federal court and three federal agencies that the SEC had acted unlawfully.
Then there is Black, who in addition to his Keating Five work is known for having essentially written the book on "control fraud," the methods banks have used to turn fraudulent activity into a business model that is highly profitable and hard to prosecute. The book that explains that topic has a title that says it all: "The Best Way to Rob a Bank Is to Own One."
Bank Whistleblowers United have devised a "60-day plan" that the next president - or even the current president - should execute. The plan has 19 actions, 18 of which can be done by the executive branch or regulatory agencies with laws and regulatory authority they already have, "so there are no excuses," Black said. Only one action - hiring more FBI agents, Justice Department attorneys and regulatory investigators - would require budgetary action in Congress.
At the top of that list is restoring "the mandatory criminal referral process and Criminal Referral Coordinators at every financial regulatory agency." That would lead to bank executives actually being charged with crimes and the possibility of being held accountable for their actions, rather than a process that allows financial institutions to buy a get-out-of-jail-free card through a settlement negotiation.
But a first step is to persuade presidential candidates, and for that matter congressional candidates, to make the simple pledge to, as Black put it, "no longer take money from financial felons."
The whistleblowers have not yet had a candidate sign on to their pledge. However, Democratic presidential candidate Bernie Sanders, having sworn off super PAC dollars and shunned Wall Street political donors, is closest in spirit and practice to the pledge. Meanwhile, Hillary Clinton is selling herself as the candidate who has the most comprehensive plan for curbing what she calls the "shenanigans" of a broad range of financial institutions - a word that Black said reflects Clinton's reticence to call a crime a crime and respond accordingly.
These insiders are offering a tough standard for candidates to measure their Wall Street reform agenda against. But that is because of what they have seen first-hand and the lives damaged by the banks' illicit behavior. It's good that there is a competition in the Democratic Party presidential primary to sound tough on Wall Street. The next step is for each candidate to address how much of the whistleblowers' plan for "breaking Wall Street's power over our economy and democracy" and returning the rule of law to the financial sector he or she is willing to embrace.
"I think the public has to make a decision, and that is why we are trying to tee this up for the candidates so that the public can see and speak to them," Aguirre said.
"It is ingrained in the fiber, in the DNA of our Congress and our government to defer to Wall Street," he added. "And until we change the DNA it's going to remain the same."