SUBSCRIBE TO OUR FREE NEWSLETTER
Daily news & progressive opinion—funded by the people, not the corporations—delivered straight to your inbox.
5
#000000
#FFFFFF
To donate by check, phone, or other method, see our More Ways to Give page.
Daily news & progressive opinion—funded by the people, not the corporations—delivered straight to your inbox.
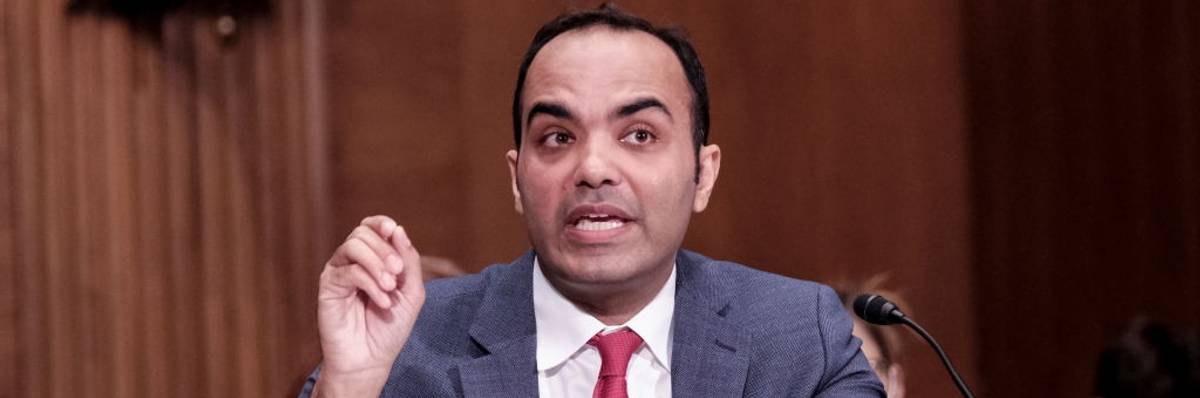
Rohit Chopra, director of the Consumer Financial Protection Bureau (CFPB), speaks during a Senate Banking, Housing, and Urban Affairs Committee hearing in Washington, D.C, U.S, on June 13, 2023.
The Consumer Financial Protection Bureau has been the most successful advocate for consumers against the industry abuse MAGA Republicans are eager to protect, including junk fees.
Last week’s Senate Commerce subcommittee
hearing was a reminder that MAGA Republicans are shamelessly on the side of their financial industry friends—even when it comes to predatory behavior as blatantly abusive as junk fees.
Although 75% of Americans are in favor of curbing the often hidden overdraft, ticketing, and service fees that cost American consumers over $15 billion every year, industry allies like Senator Marsha Blackburn (R-Tenn.) deny the fees’ impact as part of their desperate ploy to sweep their own corporate donors’ schemes under the rug.
“I'm not hearing from Tennesseans about junk fees [...] and I think for some, it's been kind of perplexing that we would focus on this issue,” said Blackburn, who has taken at least $284,000 from trade associations and companies that have lobbied against the Junk Fee Prevention Act.
Thanks to their “unmitigated success” in protecting consumers, the CFPB is scaring the industry straight—but now, predatory financial businesses are taking their fears about the agency’s power to court.
From Blackburn’s donor-fueled denial to her House colleague Rep. Blaine Luetkemeyer’s (R-Mo.) baseless belief that “junk fees don’t exist,” it’s obvious that many congressional Republicans won’t accept reality or their constituents’ wishes so long as industry cash remains in their pocket—making the need for an independent federal regulator to protect consumers more essential than ever.
Thankfully, we have a great one already. The Consumer Financial Protection Bureau (CFPB) has been the most successful advocate for consumers against the industry abuse MAGA Republicans are eager to protect, including junk fees.
After the bureau made fighting these fees a major part of its agenda, even the most exploitative banks got the memo. In August 2021, all but two of the top 20 banks charged nonsufficient-funds fees, but by August 2022, 13 of those 20 banks “eliminated nonsufficient-funds fees as part of broader overdraft reforms.”
As a result, consumers saved $4.25 billion in overdraft and nonsufficient-funds fees between 2019 and 2022—a 35% decrease in revenue for junk fee peddlers.
The agency’s efforts to save consumers cash are far from over. The CFPB recently proposed a rule to curb credit card late fees—an action expected to save American families $9 billion annually.
Thanks to their “unmitigated success” in protecting consumers, the CFPB is scaring the industry straight—but now, predatory financial businesses are taking their fears about the agency’s power to court.
In a lawsuit brought forward by the predatory payday loan industry, the conservative-leaning Fifth U.S. Circuit Court of Appeals ruled that the CFPB’s funding structure violates the Constitution’s Appropriations Clause, which requires Congress to approve all federal spending. The case—Consumer Financial Protection Bureau v. Community Financial Services Association of America—is set to be argued before the Supreme Court in its next term beginning this October, putting the agency's future and its advocacy for consumers at risk.
Abusive fees aren’t the only predatory behavior the financial industry hopes to defend from the CFPB’s regulations. Although the Fifth Circuit decision only expressly affects the CFPB’s Payday Lending Rule, its legal reasoning could call into question the legality of every CFPB action funded by the Bureau Fund—including rulemaking on junk fees, housing, and more.
It’s a possibility so egregious that even housing industry groups like the Mortgage Bankers Association and the National Association of REALTORS filed an amicus brief warning that a repeal of the CFPB’s rulemaking could spark “potentially catastrophic consequences” in the mortgage and real-estate markets.
Meanwhile, some of the financial industry’s most vulnerable targets could fall prey to their exploitative schemes without the bureau’s oversight. Many low-income Americans and communities of color would be far more susceptible to financial traps like high-cost loans without the tools and support the CFPB provides. And for military servicemembers, a weakening of the bureau could cost them the support of the only federal financial regulator with an office devoted to addressing the specific and unique threats servicemembers face.
House Republicans will have another opportunity to go to bat for their financial industry donors during the House Financial Service Committee’s Wednesday semi-annual hearing on the CFPB, where the bureau’s director, Rohit Chopra, will have the chance to defend his bureau’s critical work. It will also serve as a preview of the harm many Republicans seek to enact against American consumers by gutting the bureau’s protection.
In a world with a weaker CFPB, the Republicans who deny the truth about the financial industry’s worst behavior could have the last say regarding the fate of struggling consumers. We can’t trust industry allies to hold these bad actors accountable—the Supreme Court must rule to protect the success and advocacy of the CFPB.
This country and this world are at a monumental crossroads. US voters have an opportunity to beat back the forces of fascism and confront the billionaires who are rigging the economy, our media system, and our democracy, making it increasingly impossible for ordinary people to get by. We’re not just talking about the election. We’re talking about what must be done once these fascist elements are vanquished from power. We need a bolder set of solutions than what either major party has so far been willing to offer and a working-class movement ready to fight like hell for it. Trump didn't emerge from nowhere. The conditions that fueled MAGA authoritarianism were created by decades of radical neoliberal economic policies and a corrupt political system dominated by corporate interests. They slashed taxes on the super-rich, promising that the benefits would trickle down. They said giveaways to the corporate titans would make life more affordable for the rest of us. It was all bullshit. And when a bitter, betrayed populace searches for someone to blame, right-wing demagogues have little trouble finding scapegoats. People know when they're being lied to, but you won't hear any of this from the corporate media. Only independent journalism—powered and funded by people who believe in building a better world—can deliver truly trustworthy daily news. If you share our vision, please contribute whatever you can to sustain our work. |
Last week’s Senate Commerce subcommittee
hearing was a reminder that MAGA Republicans are shamelessly on the side of their financial industry friends—even when it comes to predatory behavior as blatantly abusive as junk fees.
Although 75% of Americans are in favor of curbing the often hidden overdraft, ticketing, and service fees that cost American consumers over $15 billion every year, industry allies like Senator Marsha Blackburn (R-Tenn.) deny the fees’ impact as part of their desperate ploy to sweep their own corporate donors’ schemes under the rug.
“I'm not hearing from Tennesseans about junk fees [...] and I think for some, it's been kind of perplexing that we would focus on this issue,” said Blackburn, who has taken at least $284,000 from trade associations and companies that have lobbied against the Junk Fee Prevention Act.
Thanks to their “unmitigated success” in protecting consumers, the CFPB is scaring the industry straight—but now, predatory financial businesses are taking their fears about the agency’s power to court.
From Blackburn’s donor-fueled denial to her House colleague Rep. Blaine Luetkemeyer’s (R-Mo.) baseless belief that “junk fees don’t exist,” it’s obvious that many congressional Republicans won’t accept reality or their constituents’ wishes so long as industry cash remains in their pocket—making the need for an independent federal regulator to protect consumers more essential than ever.
Thankfully, we have a great one already. The Consumer Financial Protection Bureau (CFPB) has been the most successful advocate for consumers against the industry abuse MAGA Republicans are eager to protect, including junk fees.
After the bureau made fighting these fees a major part of its agenda, even the most exploitative banks got the memo. In August 2021, all but two of the top 20 banks charged nonsufficient-funds fees, but by August 2022, 13 of those 20 banks “eliminated nonsufficient-funds fees as part of broader overdraft reforms.”
As a result, consumers saved $4.25 billion in overdraft and nonsufficient-funds fees between 2019 and 2022—a 35% decrease in revenue for junk fee peddlers.
The agency’s efforts to save consumers cash are far from over. The CFPB recently proposed a rule to curb credit card late fees—an action expected to save American families $9 billion annually.
Thanks to their “unmitigated success” in protecting consumers, the CFPB is scaring the industry straight—but now, predatory financial businesses are taking their fears about the agency’s power to court.
In a lawsuit brought forward by the predatory payday loan industry, the conservative-leaning Fifth U.S. Circuit Court of Appeals ruled that the CFPB’s funding structure violates the Constitution’s Appropriations Clause, which requires Congress to approve all federal spending. The case—Consumer Financial Protection Bureau v. Community Financial Services Association of America—is set to be argued before the Supreme Court in its next term beginning this October, putting the agency's future and its advocacy for consumers at risk.
Abusive fees aren’t the only predatory behavior the financial industry hopes to defend from the CFPB’s regulations. Although the Fifth Circuit decision only expressly affects the CFPB’s Payday Lending Rule, its legal reasoning could call into question the legality of every CFPB action funded by the Bureau Fund—including rulemaking on junk fees, housing, and more.
It’s a possibility so egregious that even housing industry groups like the Mortgage Bankers Association and the National Association of REALTORS filed an amicus brief warning that a repeal of the CFPB’s rulemaking could spark “potentially catastrophic consequences” in the mortgage and real-estate markets.
Meanwhile, some of the financial industry’s most vulnerable targets could fall prey to their exploitative schemes without the bureau’s oversight. Many low-income Americans and communities of color would be far more susceptible to financial traps like high-cost loans without the tools and support the CFPB provides. And for military servicemembers, a weakening of the bureau could cost them the support of the only federal financial regulator with an office devoted to addressing the specific and unique threats servicemembers face.
House Republicans will have another opportunity to go to bat for their financial industry donors during the House Financial Service Committee’s Wednesday semi-annual hearing on the CFPB, where the bureau’s director, Rohit Chopra, will have the chance to defend his bureau’s critical work. It will also serve as a preview of the harm many Republicans seek to enact against American consumers by gutting the bureau’s protection.
In a world with a weaker CFPB, the Republicans who deny the truth about the financial industry’s worst behavior could have the last say regarding the fate of struggling consumers. We can’t trust industry allies to hold these bad actors accountable—the Supreme Court must rule to protect the success and advocacy of the CFPB.
Last week’s Senate Commerce subcommittee
hearing was a reminder that MAGA Republicans are shamelessly on the side of their financial industry friends—even when it comes to predatory behavior as blatantly abusive as junk fees.
Although 75% of Americans are in favor of curbing the often hidden overdraft, ticketing, and service fees that cost American consumers over $15 billion every year, industry allies like Senator Marsha Blackburn (R-Tenn.) deny the fees’ impact as part of their desperate ploy to sweep their own corporate donors’ schemes under the rug.
“I'm not hearing from Tennesseans about junk fees [...] and I think for some, it's been kind of perplexing that we would focus on this issue,” said Blackburn, who has taken at least $284,000 from trade associations and companies that have lobbied against the Junk Fee Prevention Act.
Thanks to their “unmitigated success” in protecting consumers, the CFPB is scaring the industry straight—but now, predatory financial businesses are taking their fears about the agency’s power to court.
From Blackburn’s donor-fueled denial to her House colleague Rep. Blaine Luetkemeyer’s (R-Mo.) baseless belief that “junk fees don’t exist,” it’s obvious that many congressional Republicans won’t accept reality or their constituents’ wishes so long as industry cash remains in their pocket—making the need for an independent federal regulator to protect consumers more essential than ever.
Thankfully, we have a great one already. The Consumer Financial Protection Bureau (CFPB) has been the most successful advocate for consumers against the industry abuse MAGA Republicans are eager to protect, including junk fees.
After the bureau made fighting these fees a major part of its agenda, even the most exploitative banks got the memo. In August 2021, all but two of the top 20 banks charged nonsufficient-funds fees, but by August 2022, 13 of those 20 banks “eliminated nonsufficient-funds fees as part of broader overdraft reforms.”
As a result, consumers saved $4.25 billion in overdraft and nonsufficient-funds fees between 2019 and 2022—a 35% decrease in revenue for junk fee peddlers.
The agency’s efforts to save consumers cash are far from over. The CFPB recently proposed a rule to curb credit card late fees—an action expected to save American families $9 billion annually.
Thanks to their “unmitigated success” in protecting consumers, the CFPB is scaring the industry straight—but now, predatory financial businesses are taking their fears about the agency’s power to court.
In a lawsuit brought forward by the predatory payday loan industry, the conservative-leaning Fifth U.S. Circuit Court of Appeals ruled that the CFPB’s funding structure violates the Constitution’s Appropriations Clause, which requires Congress to approve all federal spending. The case—Consumer Financial Protection Bureau v. Community Financial Services Association of America—is set to be argued before the Supreme Court in its next term beginning this October, putting the agency's future and its advocacy for consumers at risk.
Abusive fees aren’t the only predatory behavior the financial industry hopes to defend from the CFPB’s regulations. Although the Fifth Circuit decision only expressly affects the CFPB’s Payday Lending Rule, its legal reasoning could call into question the legality of every CFPB action funded by the Bureau Fund—including rulemaking on junk fees, housing, and more.
It’s a possibility so egregious that even housing industry groups like the Mortgage Bankers Association and the National Association of REALTORS filed an amicus brief warning that a repeal of the CFPB’s rulemaking could spark “potentially catastrophic consequences” in the mortgage and real-estate markets.
Meanwhile, some of the financial industry’s most vulnerable targets could fall prey to their exploitative schemes without the bureau’s oversight. Many low-income Americans and communities of color would be far more susceptible to financial traps like high-cost loans without the tools and support the CFPB provides. And for military servicemembers, a weakening of the bureau could cost them the support of the only federal financial regulator with an office devoted to addressing the specific and unique threats servicemembers face.
House Republicans will have another opportunity to go to bat for their financial industry donors during the House Financial Service Committee’s Wednesday semi-annual hearing on the CFPB, where the bureau’s director, Rohit Chopra, will have the chance to defend his bureau’s critical work. It will also serve as a preview of the harm many Republicans seek to enact against American consumers by gutting the bureau’s protection.
In a world with a weaker CFPB, the Republicans who deny the truth about the financial industry’s worst behavior could have the last say regarding the fate of struggling consumers. We can’t trust industry allies to hold these bad actors accountable—the Supreme Court must rule to protect the success and advocacy of the CFPB.