SUBSCRIBE TO OUR FREE NEWSLETTER
Daily news & progressive opinion—funded by the people, not the corporations—delivered straight to your inbox.
5
#000000
#FFFFFF
To donate by check, phone, or other method, see our More Ways to Give page.
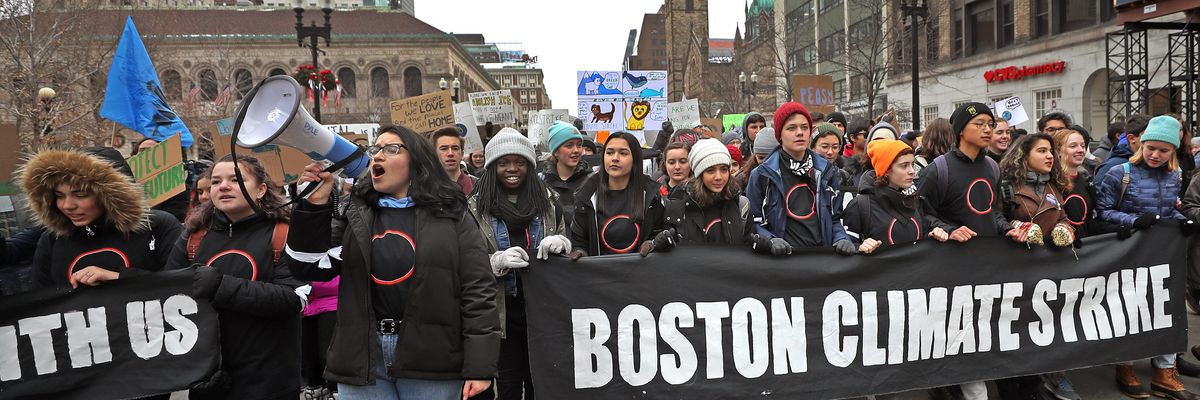
Progressives praised the Boston City Council after its members voted unanimously Wednesday to divest city funds from the fossil fuel industry, a major endorsement of clean energy investment that came as Massachusetts lawmakers prepare to debate how to allocate the state's financial resources.
"The climate crisis requires us to take immediate steps toward a cleaner future."
The ordinance "would prevent the city treasury office from investing any funds in the fossil fuel industry, including infrastructure," the Boston Globe reported. Although the legislation "would not place any restrictions on pension investments," which are governed by state law, the city's "overwhelming support sends a message as the state also weighs how to invest pension funds."
Recently elected Boston Mayor Michelle Wu, who co-sponsored the ordinance earlier this year and backed other fossil fuel divestment efforts during her eight-year stint on the city council, is expected to sign the newly passed measure into law.
Related Content

Boston City Councilor Lydia Edwards, a lead sponsor of the ordinance, said during Wednesday's hearing that "our budget is a statement of our values."
She urged her colleagues to support the measure, which requires Boston's collector-treasurer to divest city funds from "stocks, securities, or other obligations of any company which derives more than 15% of its revenue from the combustion, distribution, extraction, manufacture, or sale of fossil fuels, which shall include coal, oil, and gas, or fossil fuel products."
After the proposal was approved, Edwards thanked Wu and Boston City Councilor Matt O'Malley for partnering with her to introduce it and stressed that "the climate crisis requires us to take immediate steps toward a cleaner future."
"Divesting city funds from fossil fuels," added Edwards, a candidate for the Massachusetts Senate, "is an important step towards a cleaner, more sustainable future."
According to the Globe:
The city's treasury department oversees investments totaling about $2 billion, but a third of that portfolio is governed by state laws and restrictions, leaving Boston officials in control of just over $1.3 billion worth of investments, city officials said. Already, the city in recent years has moved to invest more in green energy. The proposed city ordinance would go further by essentially restricting any investments in the fossil fuel industry.
Edwards said the ordinance would remove about $65 million in city investments from fossil fuels, though the legislation would set a 2025 deadline for full divestment.
Author and environmentalist Bill McKibben celebrated the city council's move, which he said "will send a strong signal" to the Massachusetts Legislature as it considers Senate Bill 722 and House Bill 2640--proposals that would authorize pension funds to divest from fossil fuels.
As the Globe noted, "the state--which boasts a $95 billion investment portfolio--has resisted divesting [taxpayer funds from fossil fuels], despite 17 years of calls from residents for it to do so."
Fossil Fuel Divest Harvard, which in September won a yearslong campaign to force Harvard University's endowment--recently valued at $53.2 billion, making it the wealthiest in the world--to stop investing in fossil fuels, also saluted Boston officials and activists for their victory.
"Now," the group said, "it's time for the rest of the state--commonwealth pension funds, remaining institutional investors, etc.--to follow."
Progressives praised the Boston City Council after its members voted unanimously Wednesday to divest city funds from the fossil fuel industry, a major endorsement of clean energy investment that came as Massachusetts lawmakers prepare to debate how to allocate the state's financial resources.
"The climate crisis requires us to take immediate steps toward a cleaner future."
The ordinance "would prevent the city treasury office from investing any funds in the fossil fuel industry, including infrastructure," the Boston Globe reported. Although the legislation "would not place any restrictions on pension investments," which are governed by state law, the city's "overwhelming support sends a message as the state also weighs how to invest pension funds."
Recently elected Boston Mayor Michelle Wu, who co-sponsored the ordinance earlier this year and backed other fossil fuel divestment efforts during her eight-year stint on the city council, is expected to sign the newly passed measure into law.
Related Content
Boston City Councilor Lydia Edwards, a lead sponsor of the ordinance, said during Wednesday's hearing that "our budget is a statement of our values."
She urged her colleagues to support the measure, which requires Boston's collector-treasurer to divest city funds from "stocks, securities, or other obligations of any company which derives more than 15% of its revenue from the combustion, distribution, extraction, manufacture, or sale of fossil fuels, which shall include coal, oil, and gas, or fossil fuel products."
After the proposal was approved, Edwards thanked Wu and Boston City Councilor Matt O'Malley for partnering with her to introduce it and stressed that "the climate crisis requires us to take immediate steps toward a cleaner future."
"Divesting city funds from fossil fuels," added Edwards, a candidate for the Massachusetts Senate, "is an important step towards a cleaner, more sustainable future."
According to the Globe:
The city's treasury department oversees investments totaling about $2 billion, but a third of that portfolio is governed by state laws and restrictions, leaving Boston officials in control of just over $1.3 billion worth of investments, city officials said. Already, the city in recent years has moved to invest more in green energy. The proposed city ordinance would go further by essentially restricting any investments in the fossil fuel industry.
Edwards said the ordinance would remove about $65 million in city investments from fossil fuels, though the legislation would set a 2025 deadline for full divestment.
Author and environmentalist Bill McKibben celebrated the city council's move, which he said "will send a strong signal" to the Massachusetts Legislature as it considers Senate Bill 722 and House Bill 2640--proposals that would authorize pension funds to divest from fossil fuels.
As the Globe noted, "the state--which boasts a $95 billion investment portfolio--has resisted divesting [taxpayer funds from fossil fuels], despite 17 years of calls from residents for it to do so."
Fossil Fuel Divest Harvard, which in September won a yearslong campaign to force Harvard University's endowment--recently valued at $53.2 billion, making it the wealthiest in the world--to stop investing in fossil fuels, also saluted Boston officials and activists for their victory.
"Now," the group said, "it's time for the rest of the state--commonwealth pension funds, remaining institutional investors, etc.--to follow."
Progressives praised the Boston City Council after its members voted unanimously Wednesday to divest city funds from the fossil fuel industry, a major endorsement of clean energy investment that came as Massachusetts lawmakers prepare to debate how to allocate the state's financial resources.
"The climate crisis requires us to take immediate steps toward a cleaner future."
The ordinance "would prevent the city treasury office from investing any funds in the fossil fuel industry, including infrastructure," the Boston Globe reported. Although the legislation "would not place any restrictions on pension investments," which are governed by state law, the city's "overwhelming support sends a message as the state also weighs how to invest pension funds."
Recently elected Boston Mayor Michelle Wu, who co-sponsored the ordinance earlier this year and backed other fossil fuel divestment efforts during her eight-year stint on the city council, is expected to sign the newly passed measure into law.
Related Content
Boston City Councilor Lydia Edwards, a lead sponsor of the ordinance, said during Wednesday's hearing that "our budget is a statement of our values."
She urged her colleagues to support the measure, which requires Boston's collector-treasurer to divest city funds from "stocks, securities, or other obligations of any company which derives more than 15% of its revenue from the combustion, distribution, extraction, manufacture, or sale of fossil fuels, which shall include coal, oil, and gas, or fossil fuel products."
After the proposal was approved, Edwards thanked Wu and Boston City Councilor Matt O'Malley for partnering with her to introduce it and stressed that "the climate crisis requires us to take immediate steps toward a cleaner future."
"Divesting city funds from fossil fuels," added Edwards, a candidate for the Massachusetts Senate, "is an important step towards a cleaner, more sustainable future."
According to the Globe:
The city's treasury department oversees investments totaling about $2 billion, but a third of that portfolio is governed by state laws and restrictions, leaving Boston officials in control of just over $1.3 billion worth of investments, city officials said. Already, the city in recent years has moved to invest more in green energy. The proposed city ordinance would go further by essentially restricting any investments in the fossil fuel industry.
Edwards said the ordinance would remove about $65 million in city investments from fossil fuels, though the legislation would set a 2025 deadline for full divestment.
Author and environmentalist Bill McKibben celebrated the city council's move, which he said "will send a strong signal" to the Massachusetts Legislature as it considers Senate Bill 722 and House Bill 2640--proposals that would authorize pension funds to divest from fossil fuels.
As the Globe noted, "the state--which boasts a $95 billion investment portfolio--has resisted divesting [taxpayer funds from fossil fuels], despite 17 years of calls from residents for it to do so."
Fossil Fuel Divest Harvard, which in September won a yearslong campaign to force Harvard University's endowment--recently valued at $53.2 billion, making it the wealthiest in the world--to stop investing in fossil fuels, also saluted Boston officials and activists for their victory.
"Now," the group said, "it's time for the rest of the state--commonwealth pension funds, remaining institutional investors, etc.--to follow."