SUBSCRIBE TO OUR FREE NEWSLETTER
Daily news & progressive opinion—funded by the people, not the corporations—delivered straight to your inbox.
5
#000000
#FFFFFF
To donate by check, phone, or other method, see our More Ways to Give page.
Daily news & progressive opinion—funded by the people, not the corporations—delivered straight to your inbox.
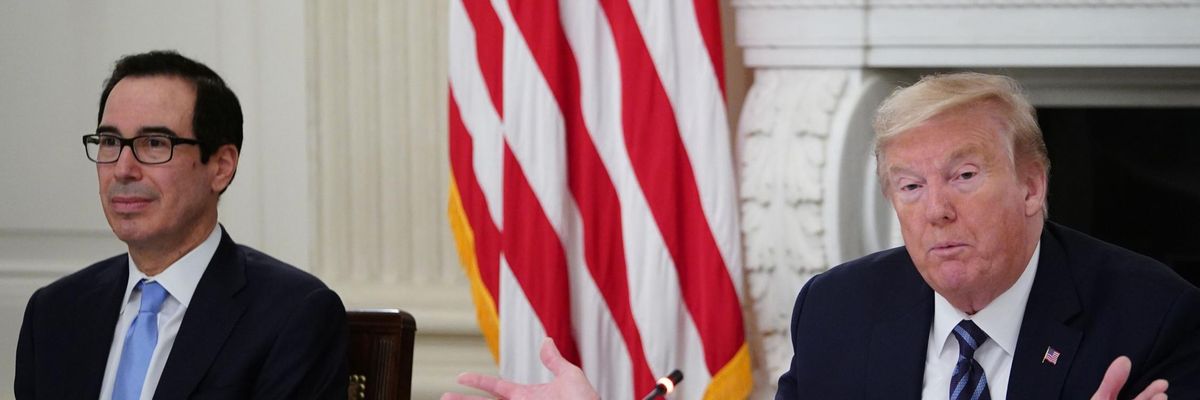
Former President Donald Trump meets with Republican members of Congress as Treasury Secretary Steve Mnuchin looks on in the State Dining Room of the White House in Washington, D.C. on May 8, 2020. (Photo: Mandel Ngan/AFP via Getty Images)
The U.S. Senate on Tuesday voted largely along party lines to repeal a Trump-era rule that has made it easier for predatory payday lenders to dodge state-level interest rate limits and trap vulnerable, low-income people in debt.
By a vote of 52-47--with Sens. Cynthia Lummis (R-Wyo.), Susan Collins (R-Maine), and Marco Rubio (R-Fla.) crossing the aisle in support--the Senate passed a Congressional Review Act (CRA) resolution that would undo the Trump administration's change, which financial industry watchdogs and consumer advocacy groups have taken to calling the "fake lender" rule.
"Now, the U.S. House of Representatives must act to protect consumers, especially small business owners, still reeling from the fallout from the Covid-19 pandemic."
--Rachel Gittleman, Consumer Federation of America
A companion CRA resolution has been introduced in the House of Representatives, which has until the end of the legislative session to pass it.
Stressing the urgency of House action, Lauren Saunders of the National Consumer Law Center said the Trump-era rule is "doing active harm right now, defending a predatory business model that destroys small businesses, homes, and lives."
As just one egregious example, advocates have pointed to the case of a New York City restaurant owner who took out $67,000 in small business loans from World Business Lenders and is now facing an annual interest rate of 268%--far above the 25% maximum permitted under New York's criminal usury statute.
The Payday Loan Debt Trap Tracker estimates that flimsy payday lender regulations have cost consumers over $11 billion in fees since 2019.
"Congress must act," said Saunders, "because it could easily be two years or more before the rule could be repealed through rulemaking, and small business and families devastated by Covid, especially in Black and Brown communities, cannot wait."
One of the final acts of Trump's Office of the Comptroller of the Currency (OCC), the rule enables financial entities like payday lenders to rent a bank's name and charter in order to evade state laws barring non-bank institutions from charging exorbitant interest rates--a scheme known as "rent-a-bank."
"The payday lenders bring in customers willing to borrow money at high rates, and then ink a deal with a bank that will dole out the loan money to those borrowers," Hannah Levintova of Mother Jones explained. "The loan paperwork lists the bank as the originator of the loan. Once that paperwork is complete, the bank sells most of the loan back to the high-cost lender (or an affiliate). The result, then, is that the payday lender has masqueraded as a bank for the purposes of charging borrowers more money."
Rachel Gittleman, financial services outreach manager with the Consumer Federation of America, said in a statement Tuesday that the Senate's vote "shows bipartisan disapproval of the harmful rent-a-bank model that is being used by predatory payday and installment lenders to make triple-digit interest rate loans that are illegal across the country."
"Now," added Gittleman, "the U.S. House of Representatives must act to protect consumers, especially small business owners, still reeling from the fallout from the Covid-19 pandemic."
This country and this world are at a monumental crossroads. US voters have an opportunity to beat back the forces of fascism and confront the billionaires who are rigging the economy, our media system, and our democracy, making it increasingly impossible for ordinary people to get by. We’re not just talking about the election. We’re talking about what must be done once these fascist elements are vanquished from power. We need a bolder set of solutions than what either major party has so far been willing to offer and a working-class movement ready to fight like hell for it. Trump didn't emerge from nowhere. The conditions that fueled MAGA authoritarianism were created by decades of radical neoliberal economic policies and a corrupt political system dominated by corporate interests. They slashed taxes on the super-rich, promising that the benefits would trickle down. They said giveaways to the corporate titans would make life more affordable for the rest of us. It was all bullshit. And when a bitter, betrayed populace searches for someone to blame, right-wing demagogues have little trouble finding scapegoats. People know when they're being lied to, but you won't hear any of this from the corporate media. Only independent journalism—powered and funded by people who believe in building a better world—can deliver truly trustworthy daily news. If you share our vision, please contribute whatever you can to sustain our work. |
The U.S. Senate on Tuesday voted largely along party lines to repeal a Trump-era rule that has made it easier for predatory payday lenders to dodge state-level interest rate limits and trap vulnerable, low-income people in debt.
By a vote of 52-47--with Sens. Cynthia Lummis (R-Wyo.), Susan Collins (R-Maine), and Marco Rubio (R-Fla.) crossing the aisle in support--the Senate passed a Congressional Review Act (CRA) resolution that would undo the Trump administration's change, which financial industry watchdogs and consumer advocacy groups have taken to calling the "fake lender" rule.
"Now, the U.S. House of Representatives must act to protect consumers, especially small business owners, still reeling from the fallout from the Covid-19 pandemic."
--Rachel Gittleman, Consumer Federation of America
A companion CRA resolution has been introduced in the House of Representatives, which has until the end of the legislative session to pass it.
Stressing the urgency of House action, Lauren Saunders of the National Consumer Law Center said the Trump-era rule is "doing active harm right now, defending a predatory business model that destroys small businesses, homes, and lives."
As just one egregious example, advocates have pointed to the case of a New York City restaurant owner who took out $67,000 in small business loans from World Business Lenders and is now facing an annual interest rate of 268%--far above the 25% maximum permitted under New York's criminal usury statute.
The Payday Loan Debt Trap Tracker estimates that flimsy payday lender regulations have cost consumers over $11 billion in fees since 2019.
"Congress must act," said Saunders, "because it could easily be two years or more before the rule could be repealed through rulemaking, and small business and families devastated by Covid, especially in Black and Brown communities, cannot wait."
One of the final acts of Trump's Office of the Comptroller of the Currency (OCC), the rule enables financial entities like payday lenders to rent a bank's name and charter in order to evade state laws barring non-bank institutions from charging exorbitant interest rates--a scheme known as "rent-a-bank."
"The payday lenders bring in customers willing to borrow money at high rates, and then ink a deal with a bank that will dole out the loan money to those borrowers," Hannah Levintova of Mother Jones explained. "The loan paperwork lists the bank as the originator of the loan. Once that paperwork is complete, the bank sells most of the loan back to the high-cost lender (or an affiliate). The result, then, is that the payday lender has masqueraded as a bank for the purposes of charging borrowers more money."
Rachel Gittleman, financial services outreach manager with the Consumer Federation of America, said in a statement Tuesday that the Senate's vote "shows bipartisan disapproval of the harmful rent-a-bank model that is being used by predatory payday and installment lenders to make triple-digit interest rate loans that are illegal across the country."
"Now," added Gittleman, "the U.S. House of Representatives must act to protect consumers, especially small business owners, still reeling from the fallout from the Covid-19 pandemic."
The U.S. Senate on Tuesday voted largely along party lines to repeal a Trump-era rule that has made it easier for predatory payday lenders to dodge state-level interest rate limits and trap vulnerable, low-income people in debt.
By a vote of 52-47--with Sens. Cynthia Lummis (R-Wyo.), Susan Collins (R-Maine), and Marco Rubio (R-Fla.) crossing the aisle in support--the Senate passed a Congressional Review Act (CRA) resolution that would undo the Trump administration's change, which financial industry watchdogs and consumer advocacy groups have taken to calling the "fake lender" rule.
"Now, the U.S. House of Representatives must act to protect consumers, especially small business owners, still reeling from the fallout from the Covid-19 pandemic."
--Rachel Gittleman, Consumer Federation of America
A companion CRA resolution has been introduced in the House of Representatives, which has until the end of the legislative session to pass it.
Stressing the urgency of House action, Lauren Saunders of the National Consumer Law Center said the Trump-era rule is "doing active harm right now, defending a predatory business model that destroys small businesses, homes, and lives."
As just one egregious example, advocates have pointed to the case of a New York City restaurant owner who took out $67,000 in small business loans from World Business Lenders and is now facing an annual interest rate of 268%--far above the 25% maximum permitted under New York's criminal usury statute.
The Payday Loan Debt Trap Tracker estimates that flimsy payday lender regulations have cost consumers over $11 billion in fees since 2019.
"Congress must act," said Saunders, "because it could easily be two years or more before the rule could be repealed through rulemaking, and small business and families devastated by Covid, especially in Black and Brown communities, cannot wait."
One of the final acts of Trump's Office of the Comptroller of the Currency (OCC), the rule enables financial entities like payday lenders to rent a bank's name and charter in order to evade state laws barring non-bank institutions from charging exorbitant interest rates--a scheme known as "rent-a-bank."
"The payday lenders bring in customers willing to borrow money at high rates, and then ink a deal with a bank that will dole out the loan money to those borrowers," Hannah Levintova of Mother Jones explained. "The loan paperwork lists the bank as the originator of the loan. Once that paperwork is complete, the bank sells most of the loan back to the high-cost lender (or an affiliate). The result, then, is that the payday lender has masqueraded as a bank for the purposes of charging borrowers more money."
Rachel Gittleman, financial services outreach manager with the Consumer Federation of America, said in a statement Tuesday that the Senate's vote "shows bipartisan disapproval of the harmful rent-a-bank model that is being used by predatory payday and installment lenders to make triple-digit interest rate loans that are illegal across the country."
"Now," added Gittleman, "the U.S. House of Representatives must act to protect consumers, especially small business owners, still reeling from the fallout from the Covid-19 pandemic."