SUBSCRIBE TO OUR FREE NEWSLETTER
Daily news & progressive opinion—funded by the people, not the corporations—delivered straight to your inbox.
5
#000000
#FFFFFF
To donate by check, phone, or other method, see our More Ways to Give page.
Daily news & progressive opinion—funded by the people, not the corporations—delivered straight to your inbox.
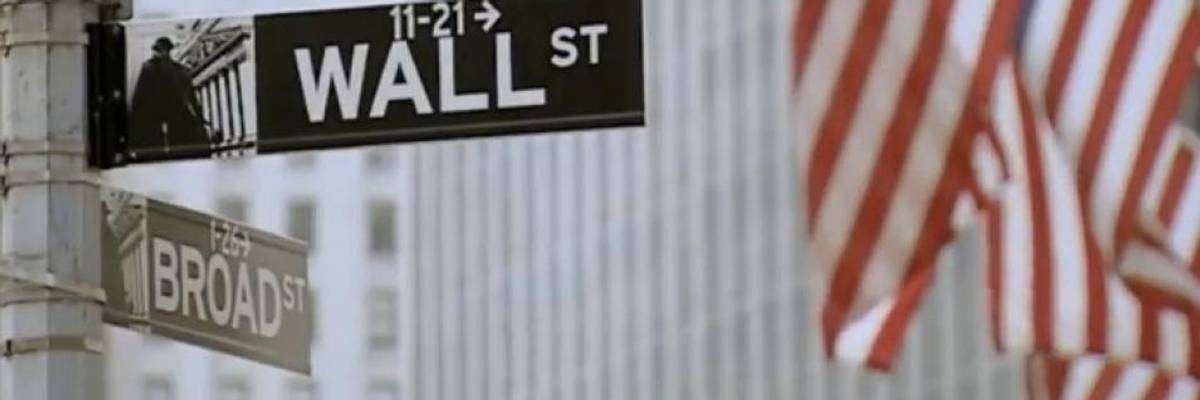
The Bank Policy Institute, a lobbying group for big banks, drew criticism for a policy memo suggesting financial deregulation as a response to the coronavirus outbreak. (Photo: Phillipp/Flickr/cc)
A lobbying group for big banks in the United States came under fire Tuesday from financial industry experts for pressuring federal officials to push through long-sought regulatory rollbacks in response to the worldwide economic concerns sparked by the global coronavirus outbreak.
On Sunday, Bank Policy Institute (BPI) chief executive Greg Baer, head of research Francisco Covas, and chief economist Bill Nelson published a post on the group's website entitled "Actions the Fed Could Take in Response to COVID-19." The BPI is a lobbying group whose members include Bank of America, Citigroup, JPMorgan Chase, and Wells Fargo.
While the trio of BPI leaders presented the suggestions as steps that the Federal Reserve could take "to allow banks to continue providing credit to businesses and households and liquidity to financial markets," financial industry experts "lambasted" the big bank group's requests as "opportunistic and unnecessary," according to the Washington Post.
As the Post reported Tuesday:
The recommendations are "transparently opportunistic," said Jeremy Kress, an assistant law professor at the University of Michigan School of Business. For years, the banking industry resisted calls for higher capital requirements that could have been used as a buffer, or a rainy-day fund, during economic turmoil, he said. Those buffers could have been turned off now to give the industry more flexibility to make loans during the current economic uncertainty, Kress said.
But without those buffers reducing existing capital requirements, which are currently set at minimum levels, the timing could be risky, he said.
"The whole idea of capital requirements and stress-testing banks is to make sure they have enough cushion to absorb losses" during an economic crisis, Kress said.
In a tweet sharing the report, Kress summed up the BPI move as follows: "Surely, the big banks aren't craven enough to use COVID-19 as an excuse to lobby for long-sought regulatory rollbacks, right? Wrong!"
BPI's recommendations for the Fed include cutting reserve requirements and relaxing "stress tests" that force banks to show they can survive an economic crisis.
Graham Steele, the director of the Corporations and Society Initiative at Stanford Graduate School of Business, tweeted that Kress was "100% correct" in characterizing the big banks' behavior as opportunistic.
"The banking industry's hammer is deregulation, and everything--from economic booms to recessions--looks like a nail," said Steele. "In fact, well capitalized banks are better able to lend throughout the business cycle."
Another financial expert suggested to the Post that the group's proposals were too extreme:
Deregulation has already gone too far, and the coronavirus could pose unique challenges to the financial system that are still unclear, said Larry White, a professor at New York University School of Business. As the virus spreads some people may not be able to work, shop and travel, he said, and "that is a problem for businesses because at the end of the day they won't be able to sell stuff."
"But I am not sure that is a good argument for, 'Oh, we need to do something about liquidity.' That is overreach by BPI," White said.
The Post report provoked criticism of BPI and alarm over the group's tactics.
Economist Betsey Stevenson, an associate professor at the University of Michigan Gerald R. Ford School of Public Policy who served on the Council of Economic Advisers during the Obama administration, called the Post's report "absolutely terrifying."
Bartlett Naylor, financial policy advocate at the watchdog group Public Citizen, offered a summary of BPI's recommendations on Twitter:
The Fed on Tuesday made an emergency cut of half a percentage point to the benchmark U.S. interest rate. "The fundamentals of the U.S. economy remain strong," Fed Chairman Jerome Powell told reporters, according to CNBC. However, he added, "the spread of the coronavirus has brought new challenges and risks."
While mainland China has been hit hardest by COVID-19, there are confirmed cases in at least 70 countries. Since the outbreak began late last year, the virus has infected more than 92,000 people and led to more than 3,100 deaths.
This country and this world are at a monumental crossroads. US voters have an opportunity to beat back the forces of fascism and confront the billionaires who are rigging the economy, our media system, and our democracy, making it increasingly impossible for ordinary people to get by. We’re not just talking about the election. We’re talking about what must be done once these fascist elements are vanquished from power. We need a bolder set of solutions than what either major party has so far been willing to offer and a working-class movement ready to fight like hell for it. Trump didn't emerge from nowhere. The conditions that fueled MAGA authoritarianism were created by decades of radical neoliberal economic policies and a corrupt political system dominated by corporate interests. They slashed taxes on the super-rich, promising that the benefits would trickle down. They said giveaways to the corporate titans would make life more affordable for the rest of us. It was all bullshit. And when a bitter, betrayed populace searches for someone to blame, right-wing demagogues have little trouble finding scapegoats. People know when they're being lied to, but you won't hear any of this from the corporate media. Only independent journalism—powered and funded by people who believe in building a better world—can deliver truly trustworthy daily news. If you share our vision, please contribute whatever you can to sustain our work. |
A lobbying group for big banks in the United States came under fire Tuesday from financial industry experts for pressuring federal officials to push through long-sought regulatory rollbacks in response to the worldwide economic concerns sparked by the global coronavirus outbreak.
On Sunday, Bank Policy Institute (BPI) chief executive Greg Baer, head of research Francisco Covas, and chief economist Bill Nelson published a post on the group's website entitled "Actions the Fed Could Take in Response to COVID-19." The BPI is a lobbying group whose members include Bank of America, Citigroup, JPMorgan Chase, and Wells Fargo.
While the trio of BPI leaders presented the suggestions as steps that the Federal Reserve could take "to allow banks to continue providing credit to businesses and households and liquidity to financial markets," financial industry experts "lambasted" the big bank group's requests as "opportunistic and unnecessary," according to the Washington Post.
As the Post reported Tuesday:
The recommendations are "transparently opportunistic," said Jeremy Kress, an assistant law professor at the University of Michigan School of Business. For years, the banking industry resisted calls for higher capital requirements that could have been used as a buffer, or a rainy-day fund, during economic turmoil, he said. Those buffers could have been turned off now to give the industry more flexibility to make loans during the current economic uncertainty, Kress said.
But without those buffers reducing existing capital requirements, which are currently set at minimum levels, the timing could be risky, he said.
"The whole idea of capital requirements and stress-testing banks is to make sure they have enough cushion to absorb losses" during an economic crisis, Kress said.
In a tweet sharing the report, Kress summed up the BPI move as follows: "Surely, the big banks aren't craven enough to use COVID-19 as an excuse to lobby for long-sought regulatory rollbacks, right? Wrong!"
BPI's recommendations for the Fed include cutting reserve requirements and relaxing "stress tests" that force banks to show they can survive an economic crisis.
Graham Steele, the director of the Corporations and Society Initiative at Stanford Graduate School of Business, tweeted that Kress was "100% correct" in characterizing the big banks' behavior as opportunistic.
"The banking industry's hammer is deregulation, and everything--from economic booms to recessions--looks like a nail," said Steele. "In fact, well capitalized banks are better able to lend throughout the business cycle."
Another financial expert suggested to the Post that the group's proposals were too extreme:
Deregulation has already gone too far, and the coronavirus could pose unique challenges to the financial system that are still unclear, said Larry White, a professor at New York University School of Business. As the virus spreads some people may not be able to work, shop and travel, he said, and "that is a problem for businesses because at the end of the day they won't be able to sell stuff."
"But I am not sure that is a good argument for, 'Oh, we need to do something about liquidity.' That is overreach by BPI," White said.
The Post report provoked criticism of BPI and alarm over the group's tactics.
Economist Betsey Stevenson, an associate professor at the University of Michigan Gerald R. Ford School of Public Policy who served on the Council of Economic Advisers during the Obama administration, called the Post's report "absolutely terrifying."
Bartlett Naylor, financial policy advocate at the watchdog group Public Citizen, offered a summary of BPI's recommendations on Twitter:
The Fed on Tuesday made an emergency cut of half a percentage point to the benchmark U.S. interest rate. "The fundamentals of the U.S. economy remain strong," Fed Chairman Jerome Powell told reporters, according to CNBC. However, he added, "the spread of the coronavirus has brought new challenges and risks."
While mainland China has been hit hardest by COVID-19, there are confirmed cases in at least 70 countries. Since the outbreak began late last year, the virus has infected more than 92,000 people and led to more than 3,100 deaths.
A lobbying group for big banks in the United States came under fire Tuesday from financial industry experts for pressuring federal officials to push through long-sought regulatory rollbacks in response to the worldwide economic concerns sparked by the global coronavirus outbreak.
On Sunday, Bank Policy Institute (BPI) chief executive Greg Baer, head of research Francisco Covas, and chief economist Bill Nelson published a post on the group's website entitled "Actions the Fed Could Take in Response to COVID-19." The BPI is a lobbying group whose members include Bank of America, Citigroup, JPMorgan Chase, and Wells Fargo.
While the trio of BPI leaders presented the suggestions as steps that the Federal Reserve could take "to allow banks to continue providing credit to businesses and households and liquidity to financial markets," financial industry experts "lambasted" the big bank group's requests as "opportunistic and unnecessary," according to the Washington Post.
As the Post reported Tuesday:
The recommendations are "transparently opportunistic," said Jeremy Kress, an assistant law professor at the University of Michigan School of Business. For years, the banking industry resisted calls for higher capital requirements that could have been used as a buffer, or a rainy-day fund, during economic turmoil, he said. Those buffers could have been turned off now to give the industry more flexibility to make loans during the current economic uncertainty, Kress said.
But without those buffers reducing existing capital requirements, which are currently set at minimum levels, the timing could be risky, he said.
"The whole idea of capital requirements and stress-testing banks is to make sure they have enough cushion to absorb losses" during an economic crisis, Kress said.
In a tweet sharing the report, Kress summed up the BPI move as follows: "Surely, the big banks aren't craven enough to use COVID-19 as an excuse to lobby for long-sought regulatory rollbacks, right? Wrong!"
BPI's recommendations for the Fed include cutting reserve requirements and relaxing "stress tests" that force banks to show they can survive an economic crisis.
Graham Steele, the director of the Corporations and Society Initiative at Stanford Graduate School of Business, tweeted that Kress was "100% correct" in characterizing the big banks' behavior as opportunistic.
"The banking industry's hammer is deregulation, and everything--from economic booms to recessions--looks like a nail," said Steele. "In fact, well capitalized banks are better able to lend throughout the business cycle."
Another financial expert suggested to the Post that the group's proposals were too extreme:
Deregulation has already gone too far, and the coronavirus could pose unique challenges to the financial system that are still unclear, said Larry White, a professor at New York University School of Business. As the virus spreads some people may not be able to work, shop and travel, he said, and "that is a problem for businesses because at the end of the day they won't be able to sell stuff."
"But I am not sure that is a good argument for, 'Oh, we need to do something about liquidity.' That is overreach by BPI," White said.
The Post report provoked criticism of BPI and alarm over the group's tactics.
Economist Betsey Stevenson, an associate professor at the University of Michigan Gerald R. Ford School of Public Policy who served on the Council of Economic Advisers during the Obama administration, called the Post's report "absolutely terrifying."
Bartlett Naylor, financial policy advocate at the watchdog group Public Citizen, offered a summary of BPI's recommendations on Twitter:
The Fed on Tuesday made an emergency cut of half a percentage point to the benchmark U.S. interest rate. "The fundamentals of the U.S. economy remain strong," Fed Chairman Jerome Powell told reporters, according to CNBC. However, he added, "the spread of the coronavirus has brought new challenges and risks."
While mainland China has been hit hardest by COVID-19, there are confirmed cases in at least 70 countries. Since the outbreak began late last year, the virus has infected more than 92,000 people and led to more than 3,100 deaths.