SUBSCRIBE TO OUR FREE NEWSLETTER
Daily news & progressive opinion—funded by the people, not the corporations—delivered straight to your inbox.
5
#000000
#FFFFFF
To donate by check, phone, or other method, see our More Ways to Give page.
Daily news & progressive opinion—funded by the people, not the corporations—delivered straight to your inbox.
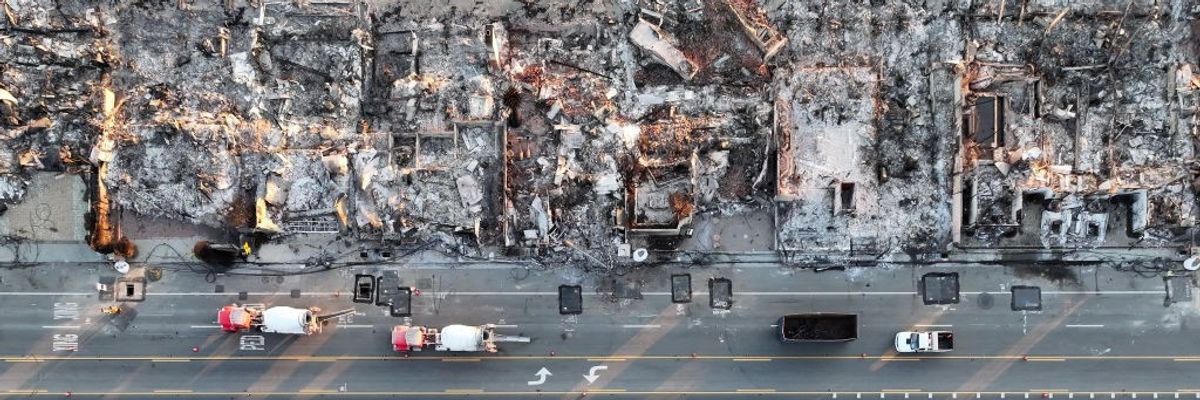
An aerial view of repair vehicles near beachside homes that burned in the Palisades Fire as wildfires cause damage and loss through the LA region on January 15, 2025 in Malibu, California.
From LA’s wildfires to Asheville’s floods, disasters are intensifying and demand resilience. Public banking offers a blueprint for recovery: leverage public dollars to cut long-term costs, create jobs, and rebuild smarter.
On the night of January 7th, as the Palisades Fire surged to 2,000 acres to the west and the Eaton Fire exploded to 1,000 to the east, I joined thousands fleeing hurricane-force winds that hurled embers for miles. But while I evacuated out of precaution, across Los Angeles, many Angelenos were not as fortunate. Like so many here, I spent those first sleepless nights glued to wall-to-wall news coverage, tracking the fires’ paths. But while flames dominated headlines, a slower crisis burns, one that Los Angeles has yet to confront.
Caught in a cycle of destruction and recovery that grows more urgent every year, fire season is no longer a season—it’s a year-round threat. Entire neighborhoods in Altadena have lost more than homes—they’ve watched their generational wealth turn to rubble. In Pacific Palisades, emergency teams scrambled to stabilize hillsides before landslides erased what remained. With wildfire losses now climbing past $250 billion, one question echoes through the city: Who pays to rebuild? And how can we do it faster, smarter, without sinking deeper into debt?
Los Angeles isn’t the first to face this reckoning. Back in 1997, Grand Forks, North Dakota, suffered a catastrophic flood. Their city was left in ruins, but they had something most cities don’t: the Bank of North Dakota (BND), America’s only state-owned public bank. Within two weeks, the BND funneled around $70 million in credit for emergency operations and rebuilding. While FEMA took months to distribute aid, the BND’s local presence and public mandate allowed it to act with precision. ND mortgage holders got six-month payment pauses. Show me one Wall Street bank that’s offered that kind of breathing room.
Caught in a cycle of destruction and recovery that grows more urgent every year, fire season is no longer a season—it’s a year-round threat.
This is the power of public banking: swift, people-focused, and designed for crisis response. Unlike profit-driven institutions, a public bank—owned by a city or state—would reinvest public deposits into local resilience rather than shareholder dividends. Imagine transforming tax dollars into a renewable resource: funding fire-resistant infrastructure, upgrading aging power grids, and keeping families housed during disasters.
Look around Los Angeles today. Insurers flee high-risk areas, leaving families stranded. Meanwhile, we’re sending more than $1.4 billion a year in debt service fees to Wall Street—this staggering sum, outlined in the City’s 2024/25 Adopted Budget (Page R-71), is money that could fortify hillsides or retrofit homes. Governor Newsom’s $2.5 billion wildfire package helps clear debris, but it doesn’t address the bigger question: How do we fund tomorrow’s disasters without predatory loans that bleed the city dry?
A public bank is the answer. Picture the Bank of North Dakota model scaled for a metropolis. Need emergency credit after the next natural disaster? Done. Low-interest loans for small businesses distributing supplies mid-crisis? No delays. By partnering with local lenders, a public bank could bridge the gap for families waiting months or years for insurance payouts.
This is the power of public banking: swift, people-focused, and designed for crisis response.
This isn’t fantasy. A national public banking movement is rising. In 2019, California passed the Public Banking Act, clearing the legal path for cities like Los Angeles to establish their own public banks. New York City plans a public bank to fund affordable housing and support minority communities. Florida eyes the model for local control of state resources. From San Francisco to New Jersey, cities and states recognize that megabanks can’t meet the scale of today’s economic and environmental challenges. Public institutions keep dollars local, funding fire-resilient housing, green energy projects, and businesses that anchor communities during crises.
During COVID-19, the Bank of North Dakota proved this again. While Wall Street prioritized corporations, the BND partnered with community banks to quickly deliver relief to small businesses and frontline workers. Los Angeles deserves that same agility. A public bank could centralize disaster funds, slash bureaucratic delays, and ensure every dollar stays local—rebuilding neighborhoods instead of enriching distant shareholders.
Housing offers another critical test. Today, financing affordable projects takes years as developers navigate a maze of private lenders. A public bank could create a housing fast-track fund, offering below-market loans for shovel-ready developments. Interest payments would recycle into future projects, not Wall Street bonuses. Streamlined funding means lower costs, faster construction, and more Angelenos housed before the next disaster strikes.
The fight isn’t about resources—it’s about control. A public bank keeps investments local, ensuring funds flow to priorities like firebreaks and microgrids rather than stock buybacks.
Critics argue public banks risk politicization. But the BND’s 105-year track record in a solidly red state disproves this: it's rated A+ by S&P with an 18.2% return on equity in 2023. It’s safer than most big banks and exceptionally stable as a public institution. By law, California’s public banks won’t compete with local community banks, instead, they will partner with them, expanding access to credit in underserved communities.
The money to capitalize a public bank exists. We’ve already raised billions for disaster recovery. The fight isn’t about resources—it’s about control. A public bank keeps investments local, ensuring funds flow to priorities like firebreaks and microgrids rather than stock buybacks.
From LA’s wildfires to Asheville’s floods, disasters are intensifying and demand resilience. Public banking offers a blueprint for recovery: leverage public dollars to cut long-term costs, create jobs, and rebuild smarter.
Los Angeles can lead this revolution. By creating the nation’s first major urban public bank, we’ll pioneer a model for cities nationwide. When the next disaster strikes, we won’t be at the mercy of for-profit banks, we’ll have the tools to rebuild ourselves—faster, fairer, and permanently stronger. The alternative is unthinkable: another decade of rubble, debt, and avoidable loss.
This country and this world are at a monumental crossroads. US voters have an opportunity to beat back the forces of fascism and confront the billionaires who are rigging the economy, our media system, and our democracy, making it increasingly impossible for ordinary people to get by. We’re not just talking about the election. We’re talking about what must be done once these fascist elements are vanquished from power. We need a bolder set of solutions than what either major party has so far been willing to offer and a working-class movement ready to fight like hell for it. Trump didn't emerge from nowhere. The conditions that fueled MAGA authoritarianism were created by decades of radical neoliberal economic policies and a corrupt political system dominated by corporate interests. They slashed taxes on the super-rich, promising that the benefits would trickle down. They said giveaways to the corporate titans would make life more affordable for the rest of us. It was all bullshit. And when a bitter, betrayed populace searches for someone to blame, right-wing demagogues have little trouble finding scapegoats. People know when they're being lied to, but you won't hear any of this from the corporate media. Only independent journalism—powered and funded by people who believe in building a better world—can deliver truly trustworthy daily news. If you share our vision, please contribute whatever you can to sustain our work. |
On the night of January 7th, as the Palisades Fire surged to 2,000 acres to the west and the Eaton Fire exploded to 1,000 to the east, I joined thousands fleeing hurricane-force winds that hurled embers for miles. But while I evacuated out of precaution, across Los Angeles, many Angelenos were not as fortunate. Like so many here, I spent those first sleepless nights glued to wall-to-wall news coverage, tracking the fires’ paths. But while flames dominated headlines, a slower crisis burns, one that Los Angeles has yet to confront.
Caught in a cycle of destruction and recovery that grows more urgent every year, fire season is no longer a season—it’s a year-round threat. Entire neighborhoods in Altadena have lost more than homes—they’ve watched their generational wealth turn to rubble. In Pacific Palisades, emergency teams scrambled to stabilize hillsides before landslides erased what remained. With wildfire losses now climbing past $250 billion, one question echoes through the city: Who pays to rebuild? And how can we do it faster, smarter, without sinking deeper into debt?
Los Angeles isn’t the first to face this reckoning. Back in 1997, Grand Forks, North Dakota, suffered a catastrophic flood. Their city was left in ruins, but they had something most cities don’t: the Bank of North Dakota (BND), America’s only state-owned public bank. Within two weeks, the BND funneled around $70 million in credit for emergency operations and rebuilding. While FEMA took months to distribute aid, the BND’s local presence and public mandate allowed it to act with precision. ND mortgage holders got six-month payment pauses. Show me one Wall Street bank that’s offered that kind of breathing room.
Caught in a cycle of destruction and recovery that grows more urgent every year, fire season is no longer a season—it’s a year-round threat.
This is the power of public banking: swift, people-focused, and designed for crisis response. Unlike profit-driven institutions, a public bank—owned by a city or state—would reinvest public deposits into local resilience rather than shareholder dividends. Imagine transforming tax dollars into a renewable resource: funding fire-resistant infrastructure, upgrading aging power grids, and keeping families housed during disasters.
Look around Los Angeles today. Insurers flee high-risk areas, leaving families stranded. Meanwhile, we’re sending more than $1.4 billion a year in debt service fees to Wall Street—this staggering sum, outlined in the City’s 2024/25 Adopted Budget (Page R-71), is money that could fortify hillsides or retrofit homes. Governor Newsom’s $2.5 billion wildfire package helps clear debris, but it doesn’t address the bigger question: How do we fund tomorrow’s disasters without predatory loans that bleed the city dry?
A public bank is the answer. Picture the Bank of North Dakota model scaled for a metropolis. Need emergency credit after the next natural disaster? Done. Low-interest loans for small businesses distributing supplies mid-crisis? No delays. By partnering with local lenders, a public bank could bridge the gap for families waiting months or years for insurance payouts.
This is the power of public banking: swift, people-focused, and designed for crisis response.
This isn’t fantasy. A national public banking movement is rising. In 2019, California passed the Public Banking Act, clearing the legal path for cities like Los Angeles to establish their own public banks. New York City plans a public bank to fund affordable housing and support minority communities. Florida eyes the model for local control of state resources. From San Francisco to New Jersey, cities and states recognize that megabanks can’t meet the scale of today’s economic and environmental challenges. Public institutions keep dollars local, funding fire-resilient housing, green energy projects, and businesses that anchor communities during crises.
During COVID-19, the Bank of North Dakota proved this again. While Wall Street prioritized corporations, the BND partnered with community banks to quickly deliver relief to small businesses and frontline workers. Los Angeles deserves that same agility. A public bank could centralize disaster funds, slash bureaucratic delays, and ensure every dollar stays local—rebuilding neighborhoods instead of enriching distant shareholders.
Housing offers another critical test. Today, financing affordable projects takes years as developers navigate a maze of private lenders. A public bank could create a housing fast-track fund, offering below-market loans for shovel-ready developments. Interest payments would recycle into future projects, not Wall Street bonuses. Streamlined funding means lower costs, faster construction, and more Angelenos housed before the next disaster strikes.
The fight isn’t about resources—it’s about control. A public bank keeps investments local, ensuring funds flow to priorities like firebreaks and microgrids rather than stock buybacks.
Critics argue public banks risk politicization. But the BND’s 105-year track record in a solidly red state disproves this: it's rated A+ by S&P with an 18.2% return on equity in 2023. It’s safer than most big banks and exceptionally stable as a public institution. By law, California’s public banks won’t compete with local community banks, instead, they will partner with them, expanding access to credit in underserved communities.
The money to capitalize a public bank exists. We’ve already raised billions for disaster recovery. The fight isn’t about resources—it’s about control. A public bank keeps investments local, ensuring funds flow to priorities like firebreaks and microgrids rather than stock buybacks.
From LA’s wildfires to Asheville’s floods, disasters are intensifying and demand resilience. Public banking offers a blueprint for recovery: leverage public dollars to cut long-term costs, create jobs, and rebuild smarter.
Los Angeles can lead this revolution. By creating the nation’s first major urban public bank, we’ll pioneer a model for cities nationwide. When the next disaster strikes, we won’t be at the mercy of for-profit banks, we’ll have the tools to rebuild ourselves—faster, fairer, and permanently stronger. The alternative is unthinkable: another decade of rubble, debt, and avoidable loss.
On the night of January 7th, as the Palisades Fire surged to 2,000 acres to the west and the Eaton Fire exploded to 1,000 to the east, I joined thousands fleeing hurricane-force winds that hurled embers for miles. But while I evacuated out of precaution, across Los Angeles, many Angelenos were not as fortunate. Like so many here, I spent those first sleepless nights glued to wall-to-wall news coverage, tracking the fires’ paths. But while flames dominated headlines, a slower crisis burns, one that Los Angeles has yet to confront.
Caught in a cycle of destruction and recovery that grows more urgent every year, fire season is no longer a season—it’s a year-round threat. Entire neighborhoods in Altadena have lost more than homes—they’ve watched their generational wealth turn to rubble. In Pacific Palisades, emergency teams scrambled to stabilize hillsides before landslides erased what remained. With wildfire losses now climbing past $250 billion, one question echoes through the city: Who pays to rebuild? And how can we do it faster, smarter, without sinking deeper into debt?
Los Angeles isn’t the first to face this reckoning. Back in 1997, Grand Forks, North Dakota, suffered a catastrophic flood. Their city was left in ruins, but they had something most cities don’t: the Bank of North Dakota (BND), America’s only state-owned public bank. Within two weeks, the BND funneled around $70 million in credit for emergency operations and rebuilding. While FEMA took months to distribute aid, the BND’s local presence and public mandate allowed it to act with precision. ND mortgage holders got six-month payment pauses. Show me one Wall Street bank that’s offered that kind of breathing room.
Caught in a cycle of destruction and recovery that grows more urgent every year, fire season is no longer a season—it’s a year-round threat.
This is the power of public banking: swift, people-focused, and designed for crisis response. Unlike profit-driven institutions, a public bank—owned by a city or state—would reinvest public deposits into local resilience rather than shareholder dividends. Imagine transforming tax dollars into a renewable resource: funding fire-resistant infrastructure, upgrading aging power grids, and keeping families housed during disasters.
Look around Los Angeles today. Insurers flee high-risk areas, leaving families stranded. Meanwhile, we’re sending more than $1.4 billion a year in debt service fees to Wall Street—this staggering sum, outlined in the City’s 2024/25 Adopted Budget (Page R-71), is money that could fortify hillsides or retrofit homes. Governor Newsom’s $2.5 billion wildfire package helps clear debris, but it doesn’t address the bigger question: How do we fund tomorrow’s disasters without predatory loans that bleed the city dry?
A public bank is the answer. Picture the Bank of North Dakota model scaled for a metropolis. Need emergency credit after the next natural disaster? Done. Low-interest loans for small businesses distributing supplies mid-crisis? No delays. By partnering with local lenders, a public bank could bridge the gap for families waiting months or years for insurance payouts.
This is the power of public banking: swift, people-focused, and designed for crisis response.
This isn’t fantasy. A national public banking movement is rising. In 2019, California passed the Public Banking Act, clearing the legal path for cities like Los Angeles to establish their own public banks. New York City plans a public bank to fund affordable housing and support minority communities. Florida eyes the model for local control of state resources. From San Francisco to New Jersey, cities and states recognize that megabanks can’t meet the scale of today’s economic and environmental challenges. Public institutions keep dollars local, funding fire-resilient housing, green energy projects, and businesses that anchor communities during crises.
During COVID-19, the Bank of North Dakota proved this again. While Wall Street prioritized corporations, the BND partnered with community banks to quickly deliver relief to small businesses and frontline workers. Los Angeles deserves that same agility. A public bank could centralize disaster funds, slash bureaucratic delays, and ensure every dollar stays local—rebuilding neighborhoods instead of enriching distant shareholders.
Housing offers another critical test. Today, financing affordable projects takes years as developers navigate a maze of private lenders. A public bank could create a housing fast-track fund, offering below-market loans for shovel-ready developments. Interest payments would recycle into future projects, not Wall Street bonuses. Streamlined funding means lower costs, faster construction, and more Angelenos housed before the next disaster strikes.
The fight isn’t about resources—it’s about control. A public bank keeps investments local, ensuring funds flow to priorities like firebreaks and microgrids rather than stock buybacks.
Critics argue public banks risk politicization. But the BND’s 105-year track record in a solidly red state disproves this: it's rated A+ by S&P with an 18.2% return on equity in 2023. It’s safer than most big banks and exceptionally stable as a public institution. By law, California’s public banks won’t compete with local community banks, instead, they will partner with them, expanding access to credit in underserved communities.
The money to capitalize a public bank exists. We’ve already raised billions for disaster recovery. The fight isn’t about resources—it’s about control. A public bank keeps investments local, ensuring funds flow to priorities like firebreaks and microgrids rather than stock buybacks.
From LA’s wildfires to Asheville’s floods, disasters are intensifying and demand resilience. Public banking offers a blueprint for recovery: leverage public dollars to cut long-term costs, create jobs, and rebuild smarter.
Los Angeles can lead this revolution. By creating the nation’s first major urban public bank, we’ll pioneer a model for cities nationwide. When the next disaster strikes, we won’t be at the mercy of for-profit banks, we’ll have the tools to rebuild ourselves—faster, fairer, and permanently stronger. The alternative is unthinkable: another decade of rubble, debt, and avoidable loss.