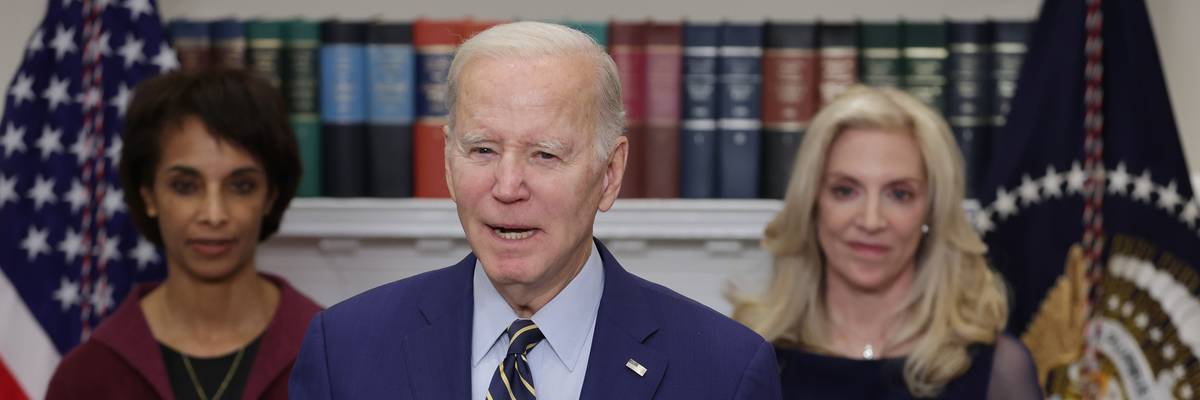
U.S. President Joe Biden delivers remarks on the February jobs report with Council of Economic Advisers Chair Cecilia Rouse and National Economic Council Director Lael Brainard at the White House on March 10, 2023 in Washington, D.C.
The Really Great February Jobs Report
If wage growth is now more or less in line with the 2% target, then the Fed can hold off on further rate hikes.
The failure of Silicon Valley Bank on Friday overtook the really big event of the day, the February jobs report. The 311,000 jobs were far more than I had expected. I thought the huge January number was a fluke of seasonal adjustments and unusually good winter weather. For that reason, I expected the February number to be very weak, not because I thought the labor market had crashed, but just as a correction to the high number in January.
I was wrong in a very big way. The January number was obviously real and the economy is still creating jobs at a very rapid clip.
This is somewhat concerning in that there is no way the economy can keep creating jobs at this pace without seeing some serious inflationary pressure, but this is where the other part of the good news story comes in. Wage growth slowed in February. The slower growth in February, combined with a downward revision to the January number, gave us a 3.6% annual rate of wage growth over the last three months.
This pace of wage growth is consistent with the Fed’s 2% inflation target. We had wage growth at this pace through much of 2018 and 2019 even as inflation was coming in slightly under the targeted rate.
I ordinarily would not be cheering slower wage growth, but the reality is that the Fed is determined to bring inflation down towards its target. If wages are growing at a pace that is faster than is consistent with its target, it will keep raising rates, and throwing people out of work, until wage growth slows.
If wage growth is now more or less in line with the 2% target, then the Fed can hold off on further rate hikes. Hopefully, it would then allow the economy to continue to grow with the unemployment rate remaining near 3.5%.
Of course, we do need to see real wage growth and inflation has been running faster than 3.5%. However, there are good reasons for believing that inflation will be slowing in the months ahead. Most importantly, we know that inflation in rents will slow sharply, as private indexes measuring rents of units coming up on the market have showed little or no inflation in recent months. The CPI rent index, which measures the rent of all units (both those that come up on the market and those with a continuing tenant) follows these indices with a lag of 6-12 months.
It is also likely that we will see further drops in many of the supply chain goods, most importantly cars, where temporary shortages sent prices soaring in the pandemic. This will help put downward pressure on inflation in goods, and also services like car repairs, where the cost of goods is a large part of the price.
And, we are also likely to see less inflation in food prices. The wholesale prices of many items, most notably eggs, has fallen sharply in the last couple of months. This should show up in lower prices in stores.
If we have a story where wages are rising at a 3.6% annual rate, and inflation falls to under 2.5%, then we would be seeing a respectable pace of real wage growth. We can hope for better, and also that we continue to see disproportionate growth at the bottom, but low unemployment and modest real wage growth is a pretty good picture.
We are at a crossroads
This country and this world are at a monumental crossroads. In a few short weeks, US voters will have an opportunity to beat back the forces of fascism and confront the billionaires who are rigging the economy, our media system, and our democracy, making it increasingly impossible for ordinary people to get by. We’re not just talking about the election. We’re talking about what must be done once these fascist elements are vanquished from power. We need a bolder set of solutions than what either major party has so far been willing to offer and a working-class movement ready to fight like hell for it. Trump didn't emerge from nowhere. The conditions that fueled MAGA authoritarianism were created by decades of radical neoliberal economic policies and a corrupt political system dominated by corporate interests. They slashed taxes on the super-rich, promising that the benefits would trickle down. They said giveaways to the corporate titans would make life more affordable for the rest of us. It was all bullshit. And when a bitter, betrayed populace searches for someone to blame, right-wing demagogues have little trouble finding scapegoats. People know when they're being lied to, but you won't hear any of this from the corporate media. Only independent journalism—powered and funded by people who believe in building a better world—can deliver truly trustworthy daily news. Our Fall Campaign is underway, and we need your help. To power our newsroom through the rest of the year, we need to raise $125,000 by midnight on October 31. So if you share our vision, please contribute whatever you can to sustain our work. |
The failure of Silicon Valley Bank on Friday overtook the really big event of the day, the February jobs report. The 311,000 jobs were far more than I had expected. I thought the huge January number was a fluke of seasonal adjustments and unusually good winter weather. For that reason, I expected the February number to be very weak, not because I thought the labor market had crashed, but just as a correction to the high number in January.
I was wrong in a very big way. The January number was obviously real and the economy is still creating jobs at a very rapid clip.
This is somewhat concerning in that there is no way the economy can keep creating jobs at this pace without seeing some serious inflationary pressure, but this is where the other part of the good news story comes in. Wage growth slowed in February. The slower growth in February, combined with a downward revision to the January number, gave us a 3.6% annual rate of wage growth over the last three months.
This pace of wage growth is consistent with the Fed’s 2% inflation target. We had wage growth at this pace through much of 2018 and 2019 even as inflation was coming in slightly under the targeted rate.
I ordinarily would not be cheering slower wage growth, but the reality is that the Fed is determined to bring inflation down towards its target. If wages are growing at a pace that is faster than is consistent with its target, it will keep raising rates, and throwing people out of work, until wage growth slows.
If wage growth is now more or less in line with the 2% target, then the Fed can hold off on further rate hikes. Hopefully, it would then allow the economy to continue to grow with the unemployment rate remaining near 3.5%.
Of course, we do need to see real wage growth and inflation has been running faster than 3.5%. However, there are good reasons for believing that inflation will be slowing in the months ahead. Most importantly, we know that inflation in rents will slow sharply, as private indexes measuring rents of units coming up on the market have showed little or no inflation in recent months. The CPI rent index, which measures the rent of all units (both those that come up on the market and those with a continuing tenant) follows these indices with a lag of 6-12 months.
It is also likely that we will see further drops in many of the supply chain goods, most importantly cars, where temporary shortages sent prices soaring in the pandemic. This will help put downward pressure on inflation in goods, and also services like car repairs, where the cost of goods is a large part of the price.
And, we are also likely to see less inflation in food prices. The wholesale prices of many items, most notably eggs, has fallen sharply in the last couple of months. This should show up in lower prices in stores.
If we have a story where wages are rising at a 3.6% annual rate, and inflation falls to under 2.5%, then we would be seeing a respectable pace of real wage growth. We can hope for better, and also that we continue to see disproportionate growth at the bottom, but low unemployment and modest real wage growth is a pretty good picture.