SUBSCRIBE TO OUR FREE NEWSLETTER
Daily news & progressive opinion—funded by the people, not the corporations—delivered straight to your inbox.
5
#000000
#FFFFFF
To donate by check, phone, or other method, see our More Ways to Give page.
Daily news & progressive opinion—funded by the people, not the corporations—delivered straight to your inbox.
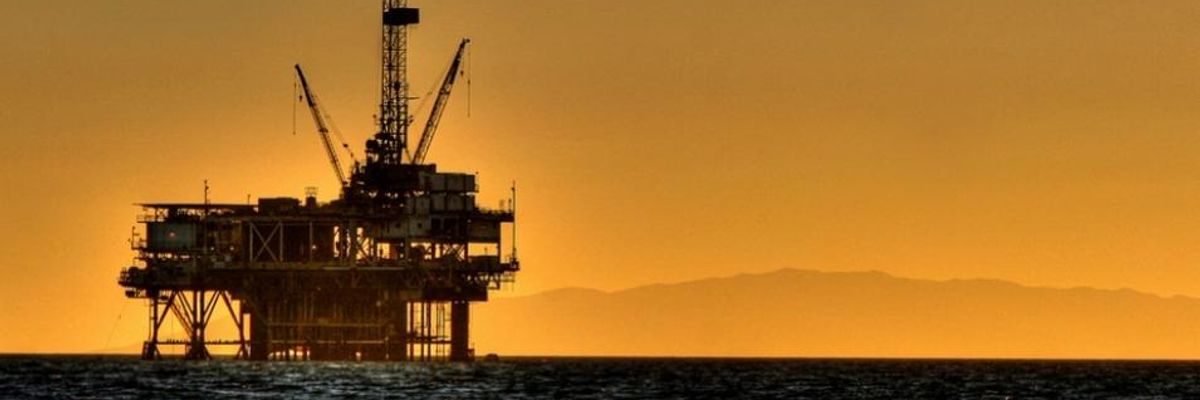
Oil giant Chevron announced Tuesday that it was writing down at least $10 billion and as much as $11 billion in assets. (Photo: arbyreed/flickr/cc)
"Two words: stranded assets."
That was the reaction Wednesday from sustainability professional Jessica Davis after oil giant Chevron announced that it was writing down at least $10 billion and as much as $11 billion in assets.
Reuters reported:
Chevron said it expected write-downs this quarter related to a deepwater Gulf of Mexico project, which needs higher oil prices to churn a profit, and shale gas in Appalachia, which has suffered from low natural gas prices. It is considering selling its stake in Appalachian shale and the proposed Kitmat LNG project in Canada.
"Oil companies have struggled to reap the profits of old and are falling out of favor with investors amid fears that electric vehicles and renewable energy, along with government regulations to address a warming planet, will constrain their futures," the Wall Street Journal added.
The news comes just a week after Spanish energy giant Repsol announced a $5.3 billion write-down of its assets. The company also pledged to be carbon neutral by 2050 and set a goal of "become a leading international player in renewable energies." That move, according to Bloomberg, "throws down the gauntlet to competitors as large oil companies face mounting investor pressure to clean up their act."
Shareholder advocacy group As You Sow said fossil fuel companies should act swiftly on that front.
"Chevron's announcement demonstrates that companies must proactively address changing energy markets. Companies that fail to plan for a net-zero world will inevitably get caught--and investors will pay the price in unplanned write-downs and an economy battered by massive climate impacts," said As You Sow president Danielle Fugere.
Lila Holzman, Fugere's colleague and the group's energy program manager, added that Chevron's write-down "is a signal of much greater troubles to come in the oil and gas industry. Energy companies must start demonstrating now how they are planning to fully align with the Paris agreement to proactively adapt to the transition."
"Business as usual, even efficient business as usual," said Fugere, "is wholly insufficient in a market that is, and must, fundamentally change."
This country and this world are at a monumental crossroads. US voters have an opportunity to beat back the forces of fascism and confront the billionaires who are rigging the economy, our media system, and our democracy, making it increasingly impossible for ordinary people to get by. We’re not just talking about the election. We’re talking about what must be done once these fascist elements are vanquished from power. We need a bolder set of solutions than what either major party has so far been willing to offer and a working-class movement ready to fight like hell for it. Trump didn't emerge from nowhere. The conditions that fueled MAGA authoritarianism were created by decades of radical neoliberal economic policies and a corrupt political system dominated by corporate interests. They slashed taxes on the super-rich, promising that the benefits would trickle down. They said giveaways to the corporate titans would make life more affordable for the rest of us. It was all bullshit. And when a bitter, betrayed populace searches for someone to blame, right-wing demagogues have little trouble finding scapegoats. People know when they're being lied to, but you won't hear any of this from the corporate media. Only independent journalism—powered and funded by people who believe in building a better world—can deliver truly trustworthy daily news. If you share our vision, please contribute whatever you can to sustain our work. |
"Two words: stranded assets."
That was the reaction Wednesday from sustainability professional Jessica Davis after oil giant Chevron announced that it was writing down at least $10 billion and as much as $11 billion in assets.
Reuters reported:
Chevron said it expected write-downs this quarter related to a deepwater Gulf of Mexico project, which needs higher oil prices to churn a profit, and shale gas in Appalachia, which has suffered from low natural gas prices. It is considering selling its stake in Appalachian shale and the proposed Kitmat LNG project in Canada.
"Oil companies have struggled to reap the profits of old and are falling out of favor with investors amid fears that electric vehicles and renewable energy, along with government regulations to address a warming planet, will constrain their futures," the Wall Street Journal added.
The news comes just a week after Spanish energy giant Repsol announced a $5.3 billion write-down of its assets. The company also pledged to be carbon neutral by 2050 and set a goal of "become a leading international player in renewable energies." That move, according to Bloomberg, "throws down the gauntlet to competitors as large oil companies face mounting investor pressure to clean up their act."
Shareholder advocacy group As You Sow said fossil fuel companies should act swiftly on that front.
"Chevron's announcement demonstrates that companies must proactively address changing energy markets. Companies that fail to plan for a net-zero world will inevitably get caught--and investors will pay the price in unplanned write-downs and an economy battered by massive climate impacts," said As You Sow president Danielle Fugere.
Lila Holzman, Fugere's colleague and the group's energy program manager, added that Chevron's write-down "is a signal of much greater troubles to come in the oil and gas industry. Energy companies must start demonstrating now how they are planning to fully align with the Paris agreement to proactively adapt to the transition."
"Business as usual, even efficient business as usual," said Fugere, "is wholly insufficient in a market that is, and must, fundamentally change."
"Two words: stranded assets."
That was the reaction Wednesday from sustainability professional Jessica Davis after oil giant Chevron announced that it was writing down at least $10 billion and as much as $11 billion in assets.
Reuters reported:
Chevron said it expected write-downs this quarter related to a deepwater Gulf of Mexico project, which needs higher oil prices to churn a profit, and shale gas in Appalachia, which has suffered from low natural gas prices. It is considering selling its stake in Appalachian shale and the proposed Kitmat LNG project in Canada.
"Oil companies have struggled to reap the profits of old and are falling out of favor with investors amid fears that electric vehicles and renewable energy, along with government regulations to address a warming planet, will constrain their futures," the Wall Street Journal added.
The news comes just a week after Spanish energy giant Repsol announced a $5.3 billion write-down of its assets. The company also pledged to be carbon neutral by 2050 and set a goal of "become a leading international player in renewable energies." That move, according to Bloomberg, "throws down the gauntlet to competitors as large oil companies face mounting investor pressure to clean up their act."
Shareholder advocacy group As You Sow said fossil fuel companies should act swiftly on that front.
"Chevron's announcement demonstrates that companies must proactively address changing energy markets. Companies that fail to plan for a net-zero world will inevitably get caught--and investors will pay the price in unplanned write-downs and an economy battered by massive climate impacts," said As You Sow president Danielle Fugere.
Lila Holzman, Fugere's colleague and the group's energy program manager, added that Chevron's write-down "is a signal of much greater troubles to come in the oil and gas industry. Energy companies must start demonstrating now how they are planning to fully align with the Paris agreement to proactively adapt to the transition."
"Business as usual, even efficient business as usual," said Fugere, "is wholly insufficient in a market that is, and must, fundamentally change."