If you are sensitive to stories of human suffering and economic hardship, let me warn you that the following report contains material that could be upsetting, so discretion is advised.
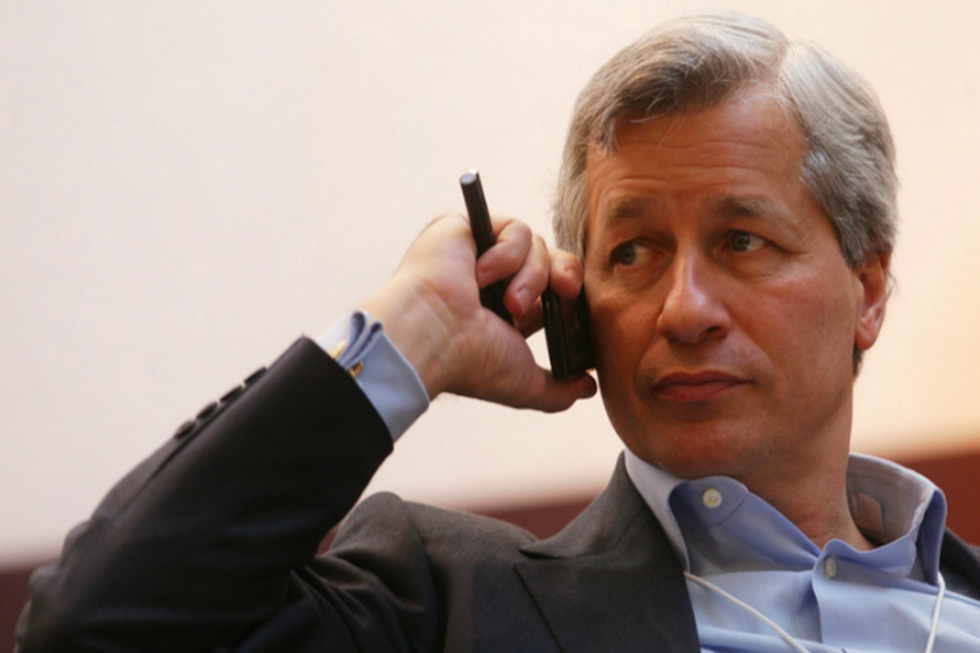
It's about a fellow named Jamie. He lives in New York City, and he has recently had a very rough go with a large financial institution. Such behemoths can be heartless, so as you can imagine, it's tough to stand up to them. The giant in this case is JPMorgan Chase, Wall Street's biggest bank, and it went after poor Jamie Dimon hard. In the end, the bank took more than half his income.
It was a bitterly painful experience, but thanks to the indomitable human spirit, Jamie's story has turned from sad to uplifting! Yes, he was down, but not out. Luckily, he had something big going for him in this fight: JPMorgan is his bank. I don't mean he banks there; he's the CEO.
On Jan. 16, it was announced that JPMorgan's board of directors had docked his pay, awarding him some $12 million less this year than he was given a year ago. Ouch! But there's no need to cry for Jamie. He still is hauling home $11.5 million.
Yet Wall Streeters are all atwitter about the haughty CEO getting his comeuppance (though I guess getting his pay cut in half would more properly be termed a "come-downance").
He certainly did have a very bad year in 2012. He presided over a stunning $6.2 billion loss by the bank's chief investment office, due to finagling or incompetence, or both -- federal authorities are still investigating. But the high-rolling denizens of Wall Street were shocked by the level of punishment meted out by the bank's board, widely condemning it as harsh. However, Dimon himself merely said of the board's action: "I respect their decision."
Of course he does! He walked away with his job intact, an $11.5-million wad in his pocket and a sly grin on his face. Many investors and bank regulators (not to mention us commoners) don't consider that level of "punishment" to be much of a deterrent to the kind of executive narcissism and too-big-too-fail carelessness that characterizes today's Wall Street elite.
JPMorgan's board told regulators it didn't consider canning the chief because he had "accepted responsibility" for the management failures that led to the shocking losses.
Wow! He cost the bank's investors six big ones, but by saying, in effect, "my bad," his bungling still is rewarded with an outsized paycheck. And, get this, $10 million of the $11.5 million he got was awarded to him as a bonus!
What a wonderful morality tale this is for America's children. If you make a mess of something, boys and girls, just tell your parents to give you the Jamie Dimon punishment.
Incredibly, the bank's 12 board members are now actually puffing out their chests and celebrating themselves as a bold governing body. The unanimous vote to slash Dimon's pay, they say, shows that -- by gollies -- we're an effective, take-charge watchdog, keeping the top management of the nation's biggest bank in check. That they can even say something so absurd speaks volumes about the laissez-faire myth that the corporations don't need government regulation, since they have private boards to oversee them.
Perhaps you're asking yourself: "Who are these toothless watchdogs?" Well, Dimon, himself, is one of them (it's always useful to be a member of the board that oversees you -- and nearly all big corporations allow their CEOs to serve as directors).
Most of the other 11 members of Dimon's board are multimillionaires who are current or former top executives of such corporate powers as Boeing, ExxonMobil, Honeywell, Johnson & Johnson and NBC. Fellow corporatists are eagerly sought out by CEOs to serve on their corporate boards because they're trusted members of "The Top Suite Club." They identify with one of their own and share the top dog's sense of entitlement, so they are predisposed to lavish lots and lots of the shareholders cash on The Boss.
Lee Raymond, the former CEO of Exxon, is one of JPMorgan's most influential directors. He heads the compensation committee of the board and was in charge of giving Dimon his "haircut." But Raymond is congenitally soft on CEO pay, because he was a spectacularly paid chieftain whose grasp of compensation propriety has no connection to the real world.
In his 13 years at the helm of the oil giant, he pocketed a total of $686 million in pay. That's $144,000 a day! Plus a car. Then he got a retirement package worth another $400 million.
"Corporate governance" is a joke, but it's not at all funny. By pampering top executives, these brother-in-law boards are dangerously exacerbating income inequality in America. The joke's on us.
If you are sensitive to stories of human suffering and economic hardship, let me warn you that the following report contains material that could be upsetting, so discretion is advised.
It's about a fellow named Jamie. He lives in New York City, and he has recently had a very rough go with a large financial institution. Such behemoths can be heartless, so as you can imagine, it's tough to stand up to them. The giant in this case is JPMorgan Chase, Wall Street's biggest bank, and it went after poor Jamie Dimon hard. In the end, the bank took more than half his income.
It was a bitterly painful experience, but thanks to the indomitable human spirit, Jamie's story has turned from sad to uplifting! Yes, he was down, but not out. Luckily, he had something big going for him in this fight: JPMorgan is his bank. I don't mean he banks there; he's the CEO.
On Jan. 16, it was announced that JPMorgan's board of directors had docked his pay, awarding him some $12 million less this year than he was given a year ago. Ouch! But there's no need to cry for Jamie. He still is hauling home $11.5 million.
Yet Wall Streeters are all atwitter about the haughty CEO getting his comeuppance (though I guess getting his pay cut in half would more properly be termed a "come-downance").
He certainly did have a very bad year in 2012. He presided over a stunning $6.2 billion loss by the bank's chief investment office, due to finagling or incompetence, or both -- federal authorities are still investigating. But the high-rolling denizens of Wall Street were shocked by the level of punishment meted out by the bank's board, widely condemning it as harsh. However, Dimon himself merely said of the board's action: "I respect their decision."
Of course he does! He walked away with his job intact, an $11.5-million wad in his pocket and a sly grin on his face. Many investors and bank regulators (not to mention us commoners) don't consider that level of "punishment" to be much of a deterrent to the kind of executive narcissism and too-big-too-fail carelessness that characterizes today's Wall Street elite.
JPMorgan's board told regulators it didn't consider canning the chief because he had "accepted responsibility" for the management failures that led to the shocking losses.
Wow! He cost the bank's investors six big ones, but by saying, in effect, "my bad," his bungling still is rewarded with an outsized paycheck. And, get this, $10 million of the $11.5 million he got was awarded to him as a bonus!
What a wonderful morality tale this is for America's children. If you make a mess of something, boys and girls, just tell your parents to give you the Jamie Dimon punishment.
Incredibly, the bank's 12 board members are now actually puffing out their chests and celebrating themselves as a bold governing body. The unanimous vote to slash Dimon's pay, they say, shows that -- by gollies -- we're an effective, take-charge watchdog, keeping the top management of the nation's biggest bank in check. That they can even say something so absurd speaks volumes about the laissez-faire myth that the corporations don't need government regulation, since they have private boards to oversee them.
Perhaps you're asking yourself: "Who are these toothless watchdogs?" Well, Dimon, himself, is one of them (it's always useful to be a member of the board that oversees you -- and nearly all big corporations allow their CEOs to serve as directors).
Most of the other 11 members of Dimon's board are multimillionaires who are current or former top executives of such corporate powers as Boeing, ExxonMobil, Honeywell, Johnson & Johnson and NBC. Fellow corporatists are eagerly sought out by CEOs to serve on their corporate boards because they're trusted members of "The Top Suite Club." They identify with one of their own and share the top dog's sense of entitlement, so they are predisposed to lavish lots and lots of the shareholders cash on The Boss.
Lee Raymond, the former CEO of Exxon, is one of JPMorgan's most influential directors. He heads the compensation committee of the board and was in charge of giving Dimon his "haircut." But Raymond is congenitally soft on CEO pay, because he was a spectacularly paid chieftain whose grasp of compensation propriety has no connection to the real world.
In his 13 years at the helm of the oil giant, he pocketed a total of $686 million in pay. That's $144,000 a day! Plus a car. Then he got a retirement package worth another $400 million.
"Corporate governance" is a joke, but it's not at all funny. By pampering top executives, these brother-in-law boards are dangerously exacerbating income inequality in America. The joke's on us.
If you are sensitive to stories of human suffering and economic hardship, let me warn you that the following report contains material that could be upsetting, so discretion is advised.
It's about a fellow named Jamie. He lives in New York City, and he has recently had a very rough go with a large financial institution. Such behemoths can be heartless, so as you can imagine, it's tough to stand up to them. The giant in this case is JPMorgan Chase, Wall Street's biggest bank, and it went after poor Jamie Dimon hard. In the end, the bank took more than half his income.
It was a bitterly painful experience, but thanks to the indomitable human spirit, Jamie's story has turned from sad to uplifting! Yes, he was down, but not out. Luckily, he had something big going for him in this fight: JPMorgan is his bank. I don't mean he banks there; he's the CEO.
On Jan. 16, it was announced that JPMorgan's board of directors had docked his pay, awarding him some $12 million less this year than he was given a year ago. Ouch! But there's no need to cry for Jamie. He still is hauling home $11.5 million.
Yet Wall Streeters are all atwitter about the haughty CEO getting his comeuppance (though I guess getting his pay cut in half would more properly be termed a "come-downance").
He certainly did have a very bad year in 2012. He presided over a stunning $6.2 billion loss by the bank's chief investment office, due to finagling or incompetence, or both -- federal authorities are still investigating. But the high-rolling denizens of Wall Street were shocked by the level of punishment meted out by the bank's board, widely condemning it as harsh. However, Dimon himself merely said of the board's action: "I respect their decision."
Of course he does! He walked away with his job intact, an $11.5-million wad in his pocket and a sly grin on his face. Many investors and bank regulators (not to mention us commoners) don't consider that level of "punishment" to be much of a deterrent to the kind of executive narcissism and too-big-too-fail carelessness that characterizes today's Wall Street elite.
JPMorgan's board told regulators it didn't consider canning the chief because he had "accepted responsibility" for the management failures that led to the shocking losses.
Wow! He cost the bank's investors six big ones, but by saying, in effect, "my bad," his bungling still is rewarded with an outsized paycheck. And, get this, $10 million of the $11.5 million he got was awarded to him as a bonus!
What a wonderful morality tale this is for America's children. If you make a mess of something, boys and girls, just tell your parents to give you the Jamie Dimon punishment.
Incredibly, the bank's 12 board members are now actually puffing out their chests and celebrating themselves as a bold governing body. The unanimous vote to slash Dimon's pay, they say, shows that -- by gollies -- we're an effective, take-charge watchdog, keeping the top management of the nation's biggest bank in check. That they can even say something so absurd speaks volumes about the laissez-faire myth that the corporations don't need government regulation, since they have private boards to oversee them.
Perhaps you're asking yourself: "Who are these toothless watchdogs?" Well, Dimon, himself, is one of them (it's always useful to be a member of the board that oversees you -- and nearly all big corporations allow their CEOs to serve as directors).
Most of the other 11 members of Dimon's board are multimillionaires who are current or former top executives of such corporate powers as Boeing, ExxonMobil, Honeywell, Johnson & Johnson and NBC. Fellow corporatists are eagerly sought out by CEOs to serve on their corporate boards because they're trusted members of "The Top Suite Club." They identify with one of their own and share the top dog's sense of entitlement, so they are predisposed to lavish lots and lots of the shareholders cash on The Boss.
Lee Raymond, the former CEO of Exxon, is one of JPMorgan's most influential directors. He heads the compensation committee of the board and was in charge of giving Dimon his "haircut." But Raymond is congenitally soft on CEO pay, because he was a spectacularly paid chieftain whose grasp of compensation propriety has no connection to the real world.
In his 13 years at the helm of the oil giant, he pocketed a total of $686 million in pay. That's $144,000 a day! Plus a car. Then he got a retirement package worth another $400 million.
"Corporate governance" is a joke, but it's not at all funny. By pampering top executives, these brother-in-law boards are dangerously exacerbating income inequality in America. The joke's on us.