
SUBSCRIBE TO OUR FREE NEWSLETTER
Daily news & progressive opinion—funded by the people, not the corporations—delivered straight to your inbox.
5
#000000
#FFFFFF
To donate by check, phone, or other method, see our More Ways to Give page.
Daily news & progressive opinion—funded by the people, not the corporations—delivered straight to your inbox.
Without endless tax deferrals, they would have only a tiny fraction of what they own today, yet, as things stand, nothing stops them from wielding the power and influence their wealth buys to benefit themselves.
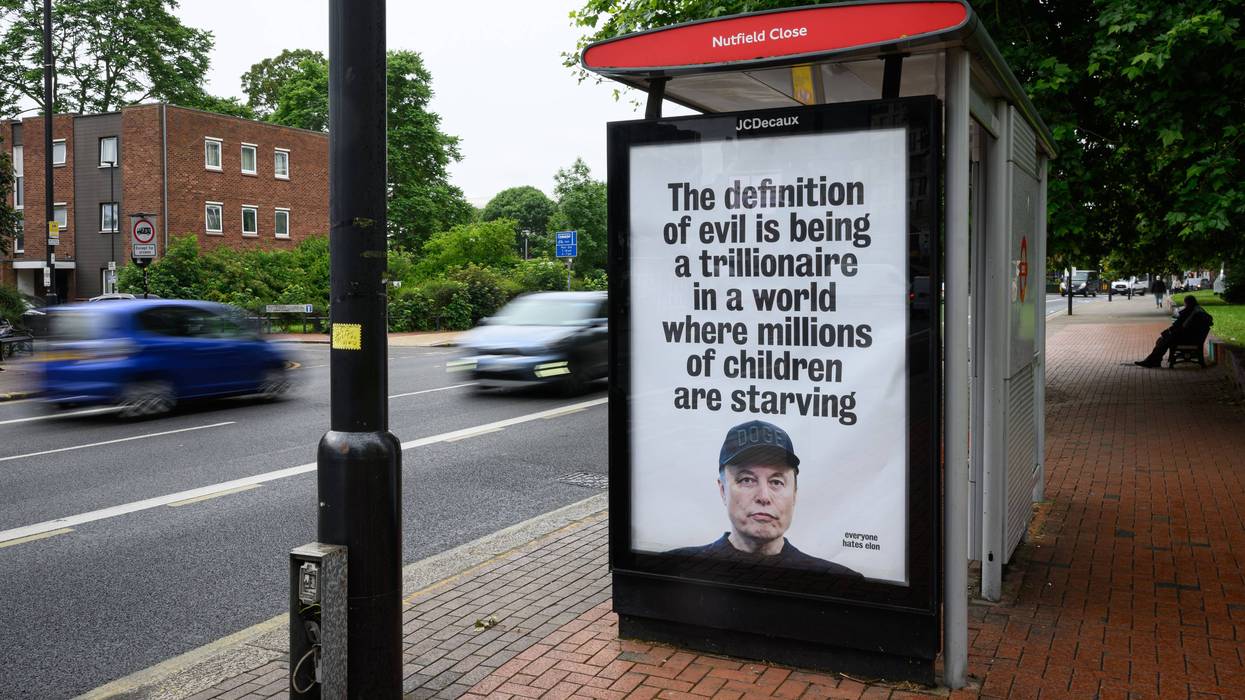
The valuation trends up and down, but one thing’s for sure: Elon Musk became the world’s first trillionaire this summer. At the height of the SpaceX IPO he was briefly worth around $1.45 trillion.
Then SpaceX stock tanked, rallied, then tanked again. But the most important thing about Musk’s wealth isn’t whether it stays above the 13-figure threshold—it’s that 94% of it comes from not having to pay taxes on unrealized gains.
That’s right: Musk’s fortune effectively comes from not paying taxes.
It’s no exaggeration to say that trillionaires (Musk likely won’t be the last) are creatures of the tax code. They ought to be called “taxillionaires.” If it weren’t for laws that permit the wealthy to endlessly defer paying taxes by keeping their gains unrealized, there would be no trillionaires—and many fewer billionaires.
We should end the practice of funding billionaires’ and trillionaires’ accumulation of power at public expense by letting them amass yet larger fortunes without paying taxes.
According to Musk’s own account, when he sold his stake in Paypal in 2002, he netted $180 million, invested it all in SpaceX and Tesla, and borrowed to pay his living expenses. To get from $180 million to a trillion today implies annual returns of over 40% (returns that would be considered impossible for ordinary investors).
Allowing these returns to compound untaxed supercharges growth.
Musk paid some taxes along the way, when he exercised stock options or sold some Tesla shares, but any taxes he paid are insignificant compared to his wealth. By contrast, for most working Americans earning a good salary, total state and federal taxes are significant—typically around 40%.
They can put limited amounts in tax-deferred IRAs, 401(k) plans, and the like. But most of their savings comes from net paychecks after withholding for federal, state, local, Social Security, unemployment, and Medicare taxes. Musk is effectively exempt from these taxes.
But he doesn’t have to be.
Suppose he were subject to the same taxes on his annual wealth increase that most higher-earning Americans pay on what they make, and had to sell some Tesla and SpaceX shares to pay those taxes. We crunched the numbers based on the latest figures, and found he’d be worth around $47 billion today—rich enough to afford the most lavish lifestyle imaginable, but not a trillionaire, and not richer than the GDP of most countries.
It’s the same story for Jeff Bezos, Warren Buffett, and other multibillionaires.
The vast bulk of their fortunes came from not paying taxes on their wealth as it grew. Without endless tax deferrals, they would have only a tiny fraction of what they own today (although that tiny fraction would still be a huge amount of money). Yet as things stand today, nothing stops them from wielding the power and influence their wealth buys to benefit themselves.
In the 2024 elections, Musk was the largest campaign donor, giving $291 million. That’s chump change for him, but it bought unprecedented power: lucrative contracts, the suspension of investigations of Musk’s businesses, access to government data, and the authority to dismantle government programs—including disruptions to foreign aid which are projected to result in over 14 million people dying from preventable diseases.
It’s a vicious cycle of wealth begetting power which begets more wealth, diverting it from the needy and vulnerable. We’re in the grip of unprecedented power accumulated by private, super-rich individuals.
We can check their power by fixing the untaxed wealth problem. We should end the practice of funding billionaires’ and trillionaires’ accumulation of power at public expense by letting them amass yet larger fortunes without paying taxes. We should adopt sensible policies requiring them to pay their fair share, such as the Billionaires Minimum Income Tax Act introduced in Congress in 2023.
Over the next decade, we will face crisis-level national debt and unmet needs for healthcare and retirement income. That will force us to decide whether to leave the vast pool of billionaire and trillionaire wealth untouched, or tax them like the rest of us to curb their influence and address public needs. The choice is ours.
The richer you are, the smaller the portion of your investment gains you pay in tax and the greater the portion of those investment gains converted to permanent wealth. That’s how wealth concentrates.
The top tax rate wealthy Americans pay on their investment gains today runs barely half the top rate the rest of us pay on our wages. But that only begins to tell the story of how lightly taxed our richest have become compared to the rest of us.
On the surface, the nominal tax rate on long-term capital gains from investments seems somewhat progressive, even given the reality that this rate sits lower than the tax rate on ordinary income. Single taxpayers with $48,350 or less in taxable income face a zero capital gains tax rate. Taxpayers with over $533,400 in taxable income, meanwhile, face a 23.8% tax on their capital gains, a rate that includes a 3.8% net investment income tax..
But these numbers shroud the real picture. In reality, we tax the ultra-rich on their investment gains less, not more. The rates we see on paper only apply to gains taxpayers register in the year they sell their investments. But we get a totally different story when we calculate the effective annual tax rate for long-held investments, especially for America’s wealthiest who sit in that nominal 23.8% bracket.
Buffett and Bezos may be poster children for reforming our absurdly regressive capital gains tax policy. But the problem remains wider than a handful of billionaires who founded wildly successful businesses.
For members of America’s top echelon—the wealthiest 2% or so of American households—the effective annual tax rate on capital gains income, the rate that really matters in measuring the impact a tax has on wealth accumulation, actually rates as sharply regressive.
That sound complicated? Let’s just do the simple math.
The federal tax on capital gains doesn’t apply until the investment giving rise to those gains gets sold, be that sale comes two years after purchase or 20. During the time a wealthy American holds an asset, the untaxed gains compound, free of tax. In other words, as the growth in the investment’s value increases, the effective annual rate of taxation when the investment finally gets sold decreases.
The graphic below shows how the effective annual tax rate on investment gains—all taxed nominally at 23.8%—varies dramatically with the rate of the gain and how long the taxpayer hangs on to the asset.
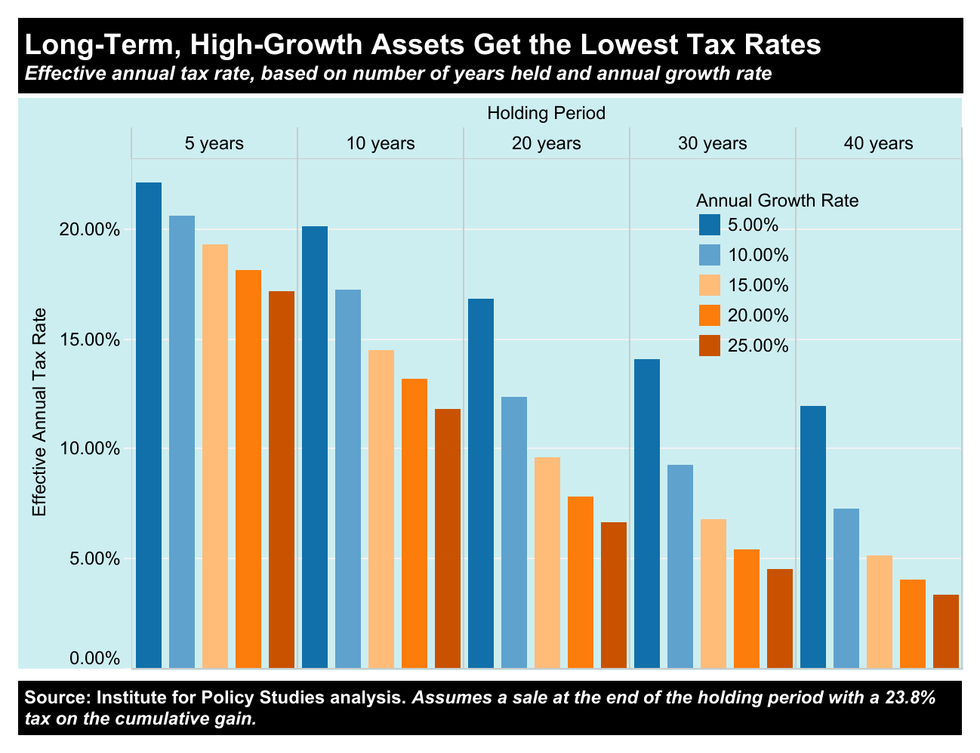
If an investor sells an asset that has averaged an annual growth of 5% after five years, the one-time tax of 23.8% on the total gain translates to an effective annual tax rate of 22.1%. In effect, paying tax at a 22.1% rate each year on investment gains that accrue at a 5% rate would leave the investor with about the same sum after five years as only paying a tax—of 23.8%—upon the investment’s sale.
In that sale situation, the tax-free compounding of gains over the five years causes a modest reduction in the effective annual tax rate, less than two percentage points. The 22.1% effective rate reduces the 5% pre-tax growth rate of the asset to a 3.9% rate after tax.
Let’s now compare that situation to an investment that grows at an average annual rate of 25% before its sale 40 years later. In this scenario, the tax-free compounding significantly reduces the effective annual tax rate to a meager 3.39%. That translates to a barely noticeable reduction in that 25% annual pre-tax rate of growth to 24.15% after tax.
Put simply, in our current tax system, the more profitable an investment proves to be, the lower the effective tax on the gains that investment generates. You could not design a more regressive tax system.
Who benefits from our regressive tax system for capital gains? We hear a lot from our politicians about some of those folks, the ones they want us to focus on.
Think of someone who starts a small business—with a modest investment of, say $100,000—that over three decades grows into a not-so-small business worth $25 million. Our culture celebrates small-business success stories like that, and political leaders in both parties seek to protect the owners of these businesses at tax time. Why punish, these lawmakers ask, small business people who started from humble beginnings and sacrificed weekends and vacations to build up their enterprises?
But do we get sound policy when we base our tax rates on high incomes on the assumption that certain high-earners have sacrificed nobly for their earnings? Think of a highly specialized surgeon who made huge personal sacrifices to develop the skills she now uses to save the lives of her patients. Should the annual income tax rate she pays on her wages be 10 times the effective annual income tax rate on the gain that the founder of a telephone solicitation call center realizes when he sells the business after 30 years?
We hear similar policy justifications for the ultra-light taxation of the gain realized upon the sale of a family’s farmland. But those who push these justifications rarely point out that the gain has little to do with the family’s decades of farming and far more to do with the land either sitting atop a recently discovered mineral deposit or sitting in the path of a major new suburban development.
Just as magicians get their audiences to focus on the left hand and pay no attention to the right, defenders of the lax tax treatment of investment gains heartily hail the hard work of farmers and small business owners, a neat move that diverts our attention from what simply can be windfall investment gains.
America’s taxation of capital gains runs regressive where it most needs to be progressive—to halt the concentration of our country’s wealth.
Those lucky farmers and business owners, you see, provide political cover for America’s billionaires, by far the biggest beneficiaries of the regressive taxation of capital gains. Consider Jeff Bezos, the founder of Amazon. His original investment in Amazon over 30 years ago, in the neighborhood of $250,000, has now grown close to $200 billion. And that’s after he’s sold off billions of dollars worth of shares. Or how about Warren Buffett, whose original investment in Berkshire Hathaway, the source of virtually all his wealth, dates back to 1962?
Bezos and Buffett, when they sell shares of their stock, face effective annual rates of tax similar to those in that far-right bar of the graphic above, under 4%.
Buffett and Bezos may be poster children for reforming our absurdly regressive capital gains tax policy. But the problem remains wider than a handful of billionaires who founded wildly successful businesses.
In 2022, for example, the top one-tenth of the top 1% of American taxpayers reported nearly one-half the total long-term capital gains of all American taxpayers. Average taxpayers in that ultra-exclusive group of just 154,000 tax-return filers had over $4.7 million of capital gains qualifying for preferential tax treatment, a sum that rates some 943 times the capital gains reported, on average, by taxpayers in the bottom 99.9% of America’s population. And this bottom 99.9%, remember, includes the bottom nine-tenths of the top 1%, who themselves boast some pretty healthy incomes,
The regressive taxation of capital gains drives the tax avoidance strategy I call Buy–Hold for Decades–Sell. The essence of this simple strategy: buy investments that will have sustained periods of growth, hold them for several decades, then sell.
The strategy works fantastically well if you happen to hit a home run with an investment and achieve sustained annual growth of 20% a year, like those who purchased shares in Microsoft in 1986 did. But you only need to do modestly well to benefit enormously from Buy–Hold for Decades–Sell. If, for instance, you only manage 10% a year growth, barely more than the average return on the S&P 500, your effective annual tax rate if you sell at the end of 30 years would be just 9.28%, leaving you with an after-tax pile of cash over 13 times the amount of your original investment.
If we dig into the data produced by economists Edward Fox and Zachary Liscow, we can see clearly that once we get to the upper levels of America’s economic pyramid, the tax avoidance benefit of Buy–Hold for Decades–Sell increases mightily as we progress to the pinnacle.
Fox and Liscow estimate, for the period between 1989 and 2022, the average annual growth in unrealized taxpayer gains at various levels in our economic pyramid [see their research paper’s second appendix table]. The clear pattern: The higher your ranking in our economic pyramid, the greater your average annual growth in unrealized gains.
And when the growth in unrealized gains is running at its highest rate, the annual effective rate of tax on those gains—when finally realized—is running at its lowest. Why? The same factors that drive the growth rate of unrealized gains higher—longer asset holding periods and higher rates of appreciation in value—also drive the annual effective tax rate lower, as the graphic above vividly shows
In short, thanks to Buy–Hold for Decades–Sell, America’s taxation of capital gains runs regressive where it most needs to be progressive—to halt the concentration of our country’s wealth. The higher we go on our wealth ladder, from the highly affluent to the rich to the ultra-rich, the lower the rate of tax. The upshot: The richer you happen to be, the smaller the portion of your investment gains you pay in tax and the greater the portion of those investment gains converted to permanent wealth. That’s how wealth concentrates.
Unless we reform the taxation of capital gains to shut down Buy–Hold for Decades–Sell, the concentration of our country’s wealth at the top—and the associated threat to our democracy—will worsen.
It’s just math.
By taking into account corporate taxes while ignoring corporate income, the foundation’s methodology drives up effective income tax rates for the super rich only because these rich happen to own a massive amount of corporate stock.
An income tax rate of over 100% would be hard for anyone to sustain. At a rate a smidge over 100%, our deepest pockets might be able to get by if they drew down their wealth or borrowed against it. But keeping up, year in and year out, with an income tax rate of over 1,000%, 10 times income? That seems, on its face, totally implausible.
Yet the Washington, D.C.-based Tax Foundation would have us believe Warren Buffett did just that for at least five years running, all while enormously growing his own personal wealth.
This conclusion about Buffett’s tax situation emerges inescapably out of the claims the Tax Foundation makes in a research paper published just after last year’s November election. The paper’s title—America’s Super Rich Pay Super Amounts of Taxes, New Treasury Report Finds—could hardly lay out the Tax Foundation’s case more starkly.
Shareholders don’t pay corporate income tax obligations. Corporations do, from their corporate income.
But did the U.S. Department of the Treasury report the Tax Foundation paper references actually make such a finding? No, not even close.
The Treasury report does analyze the total tax payments of rich and ultra-rich taxpayers relative to their wealth. The report’s writers, all highly respected economists, took into account every tax that impacts a person’s wealth, directly or indirectly. One example: A corporate shareholder bears no personal responsibility for the payment of a corporation’s income tax. But the Treasury report attributes a proportionate share of that corporate tax to shareholders since corporate taxes reduce the value of shareholders’ holdings and, consequently, their wealth.
The Tax Foundation took this Treasury analysis of total tax payments by wealthy taxpayers and proceeded to blindly compare those payments to these taxpayers’ adjusted gross incomes. That comparison enables the Tax Foundation to insist, among other claims, that the nation’s richest 0.0001% of taxpayers are paying 58% of their adjusted gross incomes in taxes.
I didn’t find this specious Tax Foundation logic particularly surprising, given that I’ve commented in the past on the specious logic that runs through other Tax Foundation studies. But this new Tax Foundation paper vividly exposes how accepting the foundation’s logic and applying that logic to real life produces results so absurd that they demand some in-depth illumination.
Which brings us back to Mr. Buffett. Thanks to reporting by the independent news outlet ProPublica and publicly available information on the income tax payments of Berkshire Hathaway, Buffett’s corporate investment base, we have considerable data on Buffett’s adjusted personal gross income, his ownership interest in Berkshire Hathaway from 2014 through 2018, and the income tax payments Berkshire made in each of those years.
We don’t have full information about Buffett’s other tax obligations, but let’s assume those obligations amounted to zero, since any additional payments would only have driven Buffett’s effective tax rate, according to the Tax Foundation’s methodology, even higher.
Warren Buffett’s ownership interest in Berkshire Hathaway—as reported in SEC filings for the years 2014, 2015, 2016, 2017, and 2018—amounted to 20.5% that first year, 19.6% the next, and then 18.7%, 17.9%, and 17.2% the last three.
According to the data service macrotrends, Berkshire Hathaway’s income tax payments minus refunds for those years totaled $7.9 billion in 2014, $10.5 billion in 2015, and $9.2 billion in 2016 before sinking into refund territory in both 2017 and 2018, with $21.5 billion in refunds the first of those two years and $321 million the second.
Applying the Tax Foundation’s methodology would attribute to Buffett a share of Berkshire’s taxes paid—and refunds received—by multiplying his ownership stake in the corporation for each of the years by the corporate tax payment made or refund received for that year. Doing the math, Buffett ends up with a personal tax liability from Berkshire of over $1.5 billion.
That figure tops by more than 10 times Buffett’s adjusted personal gross income of $125 million for that same period, according to a ProPublica review of IRS records. The bottom line: All these numbers that we get applying the Tax Foundation’s methodology bring Buffett’s effective personal income tax rate to just over 1,200%.
And Buffett would end up having paid taxes at that rate, according to the Tax Foundation methodology, at a time when Berkshire’s income tax payments, net of refunds, were running relatively low. In 2017, the massive hurricanes Harvey, Irma, and Maria had Berkshire’s insurance businesses incurring huge losses. Without those losses, and the tax refunds resulting from them, Buffett’s effective personal tax rate—according to the Tax Foundation methodology—would have topped over 4,000%!
Impossible? Of course. So what sleight of hand is the Tax Foundation playing here? Corporate income tax payments do reduce the wealth of their shareholders. Attributing a share of those tax payments to shareholders, as the original Treasury Department study does, makes eminent sense. But shareholders don’t pay corporate income tax obligations. Corporations do, from their corporate income. The Tax Foundation, for its part, doesn’t attribute corporate income to shareholders. It only attributes corporate tax.
By taking into account corporate taxes while ignoring corporate income, the Tax Foundation’s methodology drives up effective income tax rates for the super rich only because these rich happen to own a massive amount of corporate stock. We can better understand the dynamics at play here by considering the tax situations of business owners far from billionaire status.
Consider this comparison: Taxpayers A and B each own a profitable business that generates $49,999 of income in 2025. They each reinvest all business profits in their businesses, living off the savings they have sitting in tax-exempt bonds. A and B each have $1 of other income. A, who owns his business directly, reports the profits on his personal tax return, along with his dollar of other income, and pays $10,500 in tax. His effective tax rate is 21%.
B, who owns her business through a corporation, reports the profits on the corporation’s tax return, and the corporation pays $10,500 in tax. Since B’s own adjusted gross income is just one dollar, B’s effective tax rate according to the Tax Foundation would be 1,050,000%, 50,000 times A’s effective tax rate.
In its reporting, ProPublica also considered Warren Buffett’s effective income tax rate. Taking his personal federal income tax payments as a percentage of his true economic income, including the $24.3 billion increase in his wealth between 2014 and 2018, ProPublica determined his effective income tax rate to be 0.1%. Quite a far cry from 1,200%.
Despite a decline in the total number of U.S. billionaires, the total wealth of the exclusive nine-figure-club grew by $500 billion over the last five months.
There are now 801 billionaires based in the United States with a combined wealth totaling $6.22 trillion, according to an Institute for Policy Studies analysis of the Forbes Real Time Billionaire List.
The total number of billionaires is down 11 people as of September 13, 2024 from April when Forbes published their 38th annual World’s Billionaire List. Despite that decline in the number of billionaires, the total wealth of the exclusive nine-figure-club grew by $500 billion over the last five months.
The top five billionaires and by individual wealth are:
There are now a total of 12 billionaires with more than $100 billion each. For context, the first person to cross the $100 billion personal wealth threshold—Jeff Bezos—only did so in 2018.
When Forbes started tracking wealth in 1982 there were only 13 billionaires on the Forbes 400 list and it took $75 million to join the list. Today, a person needs have a minimum of $3.2 billion to make the cut.
Among the wealthiest families on the Forbes list:
Many top billionaires have seen their wealth surge since the onset of the Covid-19 pandemic.
On March 18, 2020, Elon Musk had wealth valued just under $25 billion. By the start of the next year he became the richest person in the world with a net worth of $185 billion.
After a decline of his assets from the acquisition of Twitter (now X) and falling Tesla valuations, Musk’s wealth has almost reached its 2022 peak with $252 billion.
Jeff Bezos saw his wealth rise from $113 billion on March 18, 2020 to $204 billion in the September 13, 2024 survey.
Three Walton family members—Jim, Alice, and Rob—saw their combined assets increase from $161.1 billion on March 18, 2020 to $286 billion this September.
Companies don't get better because of buybacks. Shareholders only get richer.
Warren Buffett, one of the richest people in America, defended stock buybacks in his highly anticipated annual letter to Berkshire Hathaway shareholders, released a few days ago.
“When you are told that all repurchases are harmful to shareholders or to the country, or particularly beneficial to CEOs, you are listening to either an economic illiterate or a silver-tongued demagogue (characters that are not mutually exclusive).”
Buffett may be correct about buybacks being good for shareholders, for the simple reason that each remaining outstanding share has more corporate profit behind it.
But the Oracle of Omaha is dead wrong about buybacks being good for the country. They merely enrich people who own shares of stock (the richest 10 percent of Americans own 92 percent of the stock market) rather than add to the productive capacity of America.
Many pundits (including Andrew Ross Sorkin of The New York Times’s DealBook) are failing to draw the distinction — assuming that if stock buybacks are good for corporations and their shareholders, they must be good for America.
Rubbish.
To take but one recent example: Last year, the Norfolk Southern Railway enjoyed record revenue and operating income — $3.2 billion in the fourth quarter alone, a remarkable 13 percent year-over-year increase.
How did the railroad accomplish this? By cutting nearly 10,000 jobs — reducing its workforce by a third while running fewer, longer trains. Some trains now stretch longer than 2 miles. It made these changes despite warnings that they worsened safety risks.
The corporation also refused to provide its remaining workers with sick leave. And it failed to invest in improved safety equipment. (As I noted last week, the railroad mounted a major lobbying blitz against stronger safety regulations.)
And what did Norfolk Southern do with all the money it saved from cutting its workforce, running longer trains, refusing sick leave, and scrimping on safety?
Over the past two decades, it has boosted shareholder payouts by 4,500 percent (along the way enriching Warren Buffett and other investors).
Specifically, it has spent billions on stock buybacks — hitting a record $4.7 billion in buybacks and dividends last year.
Then it went off the rails, literally, releasing a toxic plume over East Palestine, Ohio.
On Saturday it went off the rails again, near Springfield, Ohio, although thankfully this Norfolk Southern train wasn’t carrying hazardous materials.
Companies don’t get better because of buybacks. Shareholders only get richer. While railroads spent more on stock buybacks than rail safety, Warren Buffett’s wealth increased by $42 billion.
Researchers at Deloitte point out that buybacks and dividends have soared as a share of GDP, while corporate investments in equipment and infrastructure have stagnated. Many of the social costs of this failure to invest have been shifted to the public-at-large, as we saw in East Palestine.
Stock buybacks don’t create more jobs. They don’t increase wages. They don’t grow the economy.
Before 1982, it was illegal for corporations to purchase their own stock to artificially prop up share prices. Then Ronald Reagan’s SEC adopted a rule protecting corporations from being charged for this kind of stock manipulation.
Jump ahead to 2017 and the Trump-GOP tax cuts added fuel to the fire. Since then, stock buybacks have more than doubled, reaching a record high $1.2 trillion in 2022 alone.
That’s $1.2 trillion that did not go into improving quality of life for American workers or building the American economy. It just went straight into the pockets of already-wealthy shareholders and CEOs.
Once again, Wall Street gains at the expense of working families.
Which is why the Inflation Reduction Act imposes a 1 percent tax on buybacks. And why Biden wants to raise it to 4 percent. The Stock Buyback Accountability Act of 2023, introduced by Senators Sherrod Brown and Ron Wyden, would do just this.
From the standpoint of America as a whole, Biden is exactly right about stock buybacks. Buffett is utterly wrong.
If any readers are in a position to have a few of these otherwise predisposed mega-donors come to a discussion about this opportunity, the generic questions to pose to them are: What if? How to? And why not?
The super successful mega-investor, Warren Buffett, CEO of the giant conglomerate Berkshire Hathaway, was heard to say: There are only 535 members of Congress, why can’t 300 million Americans control them? That’s a pretty fundamental question since our senators and representatives are given their sovereign power by the people. Remember the preamble to our Constitution?
Buffett is a generous philanthropist. Among his contributions, he has given the Gates Foundation (public health projects) about $3 billion each year for over a decade. That’s over $30 billion dollars! Just one $3 billion contribution, devoted to establishing systemic-focused Congress Watchdog locals in every congressional district, would fund such groups for more than thirty years. Their objective would be to organize up to one-half of one percent of adults to volunteer in each congressional district to make sure our elected officials do the general public’s bidding under honest election procedures. The American people and their children have far more commonly desired necessities and wants than the hyped divide-and-rule tactics imposed by the present ruling powers imply. (See, Unstoppable: The Emerging Left-Right Alliance to Dismantle the Corporate State by Ralph Nader, April 2014).
I can hear some readers saying, “Well, if Mr. Buffett is such a public-spirited person, why don’t you ask him to do this? You’ve been writing about these groups for many years.” (See my recent columns: Think Big to Overcome Losing Big to Corporatism, January 7, 2022; Facilitating Civic and Political Energies for the Common Good, February 2, 2022; Going for Tax Reform Big Time, March 11, 2022; and Going for Big Watch on Big Budgets, March 31, 2022).
Answer: I did once, broadly, in a written letter. No connection was made. In 2011, I wrote a fictional book, “Only the Super-Rich Can Save Us!” about a Warren Buffett recoiling from the immediate neglectful aftermath of the 2005 Hurricane Katrina disaster in New Orleans. In the book, he launched, with 16 other enlightened individuals, a just, step-by-step democratic overhauling of American politics top-down and then bottom-up.
This realistic work of fiction caught his attention. He invited me to showcase the book at his massive annual shareholder’s meeting in Omaha, Nebraska. I went.
At an earlier breakfast, I mused about the story becoming a Hollywood movie. He amusingly asked who would play his character. I mentioned actors like Warren Beatty or Alan Alda.
In any event, nothing came of these interactions. My guess is that having to closely supervise over 70 managers of the sizable corporate subsidiaries of Berkshire requires an intensity of focus and time that is incompatible with the additional project of changing Congress to get good things done – popular as that would be in today’s America.
Some knowing readers might ask why Buffett doesn’t ask his network of some 236 multi-billionaires, who have signed on to his Giving Pledge, to donate half of their wealth to “good works.”
Answer: A condition for the Giving Pledge is that these philanthropists would not urge or ask each other to support their favored causes.
The obvious rejoinder to that impediment might be, “Surely this reflective man, who gets his calls returned, can create the necessary institutional network and public investments to make these long-overdue changes” – again top-down then bottom-up. Probably, yes. But the problem is, neither he nor his collaborators want to be the recipients of daily vitriol and smears so easily conveyed to the world through the Internet. They want to be left to concentrate on their own business or other pursuits in retirement.
So, what it comes down to is the perceived sense of great urgency, coupled with a belief that a group, such as described, is unique to being able to make a significant, lasting difference for the present and for posterity. That is what a civic sense of legacy, demonstrated already by the Pledgors, is – but multiplied many times over by institutional and structural reforms, backed by a critical mass of an alert citizenry, and nurtured by regular civic education for all ages.
If any readers are in a position to have a few of these otherwise predisposed mega-donors come to a discussion about this opportunity, the generic questions to pose to them are: What if? How to? And why not? Taken together, my four books “Only the Super-Rich Can Save Us”! Unstoppable: The Emerging Left-Right Alliance to Dismantle the Corporate State, Breaking Through Power: It’s Easier Than We Think, and the Fable The Day the Rats Vetoed Congress provide detailed pathways to deep-rooted transformations of our country backed by about four-fifths of the American people.
There are, predictably, many readers who will scoff and stereotype all very rich people with a totally dismissive brush. There are, however, enough examples in American history that expose this wave-of-the-hand as an excessive generalization. Some are not like the rest. Even some of the rest should be given the opportunity to make amends.
Responses are invited: info@csrl.org
Advocacy groups on Tuesday joined rail workers and progressives in Congress in calling out U.S. President Joe Biden for encouraging legislative action that would avert a December strike and force through a contract with no paid sick leave.
"If Congress must intercede, Biden should instead ask legislators to pass a better deal, including the necessary sick leave."
Biden late Monday encouraged Congress to use its authority under the Railway Labor Act of 1926 to advance the White House-brokered deal that was rejected by over half of the nation's unionized rail workforce. House Speaker Nancy Pelosi (D-Calif.) signaled the chamber could act as early as Wednesday.
Revolving Door Project executive director Jeff Hauser warned Biden that such action could harm not only rail workers but also the Democratic Party--at a time when Republicans continue to align themselves with a twice-impeached ex-president who incited an insurrection.
"President Biden has strained to rekindle working people's support for the Democratic Party. To his great credit, he has appointed genuine labor champions at the National Labor Relations Board and other independent labor agencies," he noted. "However, by calling to override the will of organized railway workers, without granting any of their demands, Biden risks undermining that hard work's legacy. Unless he reverses course, he threatens to reignite distrust of the Democratic Party among workers nationwide."
"If Democrats turn on a unionized workforce which did everything right in a struggle for basic dignity, the entire labor movement will see and remember," Hauser continued. "Rank-and-file union members have voted more and more for Republicans, sometimes including the most extreme MAGA Republicans, in recent years. This is due, in no small part, to too many broken promises and too little respect paid to labor by successive Democratic administrations."
Highlighting that "Democrats defied the historical odds to duel Republicans to a draw in the midterms not even one month ago" and "embracing economic populism and strong support for unions was a necessary component of their winning strategy," he asked, "Do Democrats want voters to think that was all a lie?"
According to Hauser:
Being a pro-labor president does not just mean taking photographs with workers or recounting family anecdotes about manual labor in speeches. It means supporting workers' ability to choose their own futures and to stand up to the bosses that oppress them. The absolute minimum which a pro-labor president should do is listen when rail workers say that the contract his administration negotiated did not deliver what they need.
The economic harms of a railway strike could indeed be grievous. This is precisely why Biden shouldn't be urging Congress to punish the workers. If Congress must intercede, Biden should instead ask legislators to pass a better deal, including the necessary sick leave, as some members are calling for already. Moreover, Biden should publicly attack the railway owners' rapacious greed. Corporate rail shareholders can live without a few extra millions in dividends, but rail workers should not be forced to live without sick leave.
Rather than pushing for the existing agreement, Hauser argued, "Biden should instead fight to give rail workers what they need, and aim the full force of the federal government where it should have been aimed all along: at the greed of the rail bosses."
Morris Pearl, chair of the Patriotic Millionaires, agreed--accusing Biden of "siding with billionaires over rail workers" and "saying that these essential workers have to suffer to preserve the profits of the railroad industry and its billionaire owners."
"No one wants a rail strike to cripple our nation's economy, but forcing workers to accept a deal they have voted against is not the only solution," he noted. "If Biden were as pro-union as he claims to be, he could have called on Congress to improve the contract for workers and force railway management to accept it. He did not do that."
Pearl warned that "if Congress votes to force rail workers to accept the current deal, they will be doing a massive disservice to workers who deserve fair compensation and adequate sick leave. By choosing to ram through this terrible deal, Joe Biden and Democratic leadership in Congress are betraying the rail unions and taking the side of billionaires like Warren Buffett, whose company Berkshire Hathaway owns BNSF, one of the largest railways in America."
"Billionaire railway owners like Warren Buffett have held the American economy hostage by refusing to concede to rail worker demands, and now the federal government is going to give them exactly what they want," Pearl continued. "Buffett is being rewarded for playing chicken with the American economy."
"If Buffett and these multibillion-dollar rail companies were to meet unions where they are and include the bare minimum number of paid sick days, it would only cost them a small fraction of their massive profits," he added. "If Congress is going to act to avert a strike, they need to protect workers, not rail company profits."
Some members of Congress made clear Tuesday that they won't support a resolution on the issue unless it includes paid sick leave.
Sen. Bernie Sanders (I-Vt.) in September blocked a Republican-led attempt to force railroad workers to accept the contract recommended by a presidential board and has continued to support their fight for a better deal.
"At a time of record profits in the rail industry, it's unacceptable that rail workers have ZERO guaranteed paid sick days," Sanders tweeted Tuesday evening. "It's my intention to block consideration of the rail legislation until a roll call vote occurs on guaranteeing seven paid sick days to rail workers in America."
HuffPost's Igor Bobic reported that when asked about Sanders' demand, Senate Majority Leader Chuck Schumer (D-N.Y.) said, "We're going to work it out and get it done."
According to Politico's Nancy Vu, Sen. John Cornyn (R-Texas) told reporters that he believes there could be "substantial Republican support" for Sanders' amendment.
Warning that the looming U.S. railroad strike "would devastate our economy," President Joe Biden angered labor advocates on Monday after he implored Congress to take legislative action to force union members to keep working under a contract that many of them have rejected, mainly due to its denial of paid sick days.
"Paid sick leave is both a basic part of fair employment practices and an absolutely essential part of national public health policy."
"I am calling on Congress to pass legislation immediately to adopt the tentative agreement between railroad workers and operators--without any modifications or delay--to avert a potentially crippling national rail shutdown," Biden said in a statement.
Under the Railway Labor Act of 1926--which critics have long slammed as anti-worker--Congress can pass a joint resolution that would force employees to stay on the job. By signing such a measure, labor advocates say, Biden would be betraying his claim, reiterated in Monday's statement, to be a "pro-labor president."
Progressive political commentator Krystal Ball responded to the president's statement by tweeting that "Biden is siding with corporate rail bosses over the rank-and-file workers who voted against this agreement."
Labor reporter Jonah Furman went even further in his criticism, accusing Biden of a "full sellout."
In his statement, Biden noted that "this agreement was approved by labor and management negotiators in September" and that the deal "provides a historic 24% pay raise for rail workers" as well as "improved healthcare benefits."
However, while most unions representing rail workers did reach agreements with their employers, the two largest--the International Association of Sheet Metal, Air, Rail, and Transportation Workers-Transportation Division (SMART-TD) and the Brotherhood of Locomotive Engineers and Trainmen (BLET)--did not accept the proposal, which critics said did not address workers' key demands on work rules and conditions.
The main sticking point involves paid sick leave. U.S. rail workers get none, and the deal being pushed by railroad companies and Biden would keep it that way. Congress could impose the industry-backed agreement without paid sick days, or it could heed unions' call for the addition of such compensated time off. Lawmakers could also extend a "cooling-off" period, allowing negotiations to continue while workers remain on the job.
Tony Caldwell, president of the Brotherhood of Maintenance of Way Employees--which rejected the proposed deal--told The Washington Post that "during [the] pandemic, our members suffered the most. The pandemic spread through our membership like wildfire. We lost members to sickness and death. They aren't happy with the deal because it didn't address their main issue: sick leave."
Dr. Eric Reinhart, an expert on public health policy, tweeted Monday that "railroad workers still get zero paid sick leave. Increased risk of exposure to infectious illness is part of many jobs. Paid sick leave is both a basic part of fair employment practices and an absolutely essential part of national public health policy."
An analysis published last week by the watchdog group Accountable.US showed that BNSF--a subsidiary of multibillionaire Warren Buffett's Berkshire Hathaway, which operates one of North America's largest railroad networks--saw a net income increase of 4% to $4.4 billion during the first three quarters of 2022. Railroad giant Union Pacific also enjoyed an 11% profit increase over the same period, during which it spent nearly $8 billion on stock buybacks.
"The corporate greed never ends," U.S. Sen. Bernie Sanders (I-Vt.) wrote Sunday. "Last year, the rail industry made a record-breaking $20 billion in profits after cutting their workforce by 30% over the last six years. Meanwhile, rail workers have ZERO guaranteed paid sick days. Congress must stand with rail workers."
The U.S. Justice Department announced Wednesday that a mortgage company owned by billionaire businessman Warren Buffett engaged in an illegal "pattern or practice of lending discrimination" by "redlining" in the Philadelphia area, and will pay $20 million in a settlement agreement.
"The complaint also alleges that Trident's employees exchanged emails where they referred to neighborhoods of color as 'ghettos' and made racist jokes."
The DOJ, which launched a Combatting Redling Initiative last October, is calling the deal the first it has ever reached with a nonbank lender and the second-largest settlement in the agency's history involving the illegal practice of denying mortgage loans to potential homebuyers of color.
The U.S. Consumer Financial Protection Bureau alleged in a complaint filed Wednesday that from at least 2015 until 2019, Trident Mortgage Company--which is owned by Buffett's Berkshire Hathaway Inc.--violated the Fair Housing Act and the Equal Credit Opportunity Act by avoiding "providing home loans and other home mortgage services in majority-minority neighborhoods" in metropolitan Philadelphia, including in New Jersey and Delaware. The lender also "discouraged those living in, or seeking credit to purchase properties in, these neighborhoods from seeking or applying for credit from Trident."
Under the terms of the agreement, Trident will invest over $20 million in boosting credit opportunities in neighborhoods of color in the Philadelphia metropolitan area.
"This settlement is a stark reminder that redlining is not a problem from a bygone era. Trident's unlawful redlining activity denied communities of color equal access to residential mortgages, stripped them of the opportunity to build wealth, and devalued properties in their neighborhoods," said Kristen Clarke, assistant attorney general of the U.S. Justice Department's Civil Rights Division, announcing the deal.
"Along with our federal and state law enforcement partners, we are sending a powerful message to lenders that they will be held accountable when they run afoul of our fair lending laws," she added.
Speaking at a Wednesday press conference announcing the settlement, Clarke said that "Trident's office locations were concentrated in majority-white neighborhoods, and that Trident's loan officers were directed to not to serve--and did not serve--the credit needs of neighborhoods of color."
"The complaint also alleges that Trident's employees exchanged emails where they referred to neighborhoods of color as 'ghettos' and made racist jokes," she added. "There's even a photo of a senior Trident manager posing in front of a Confederate flag."
Jacqueline Romero, the U.S. attorney for the Eastern District of Pennsylvania, asserted that "for far too many years Philadelphia's Black, Latino, and other communities of color have lacked equal access to lending and legal deed ownership. These historically redlined areas of Philadelphia continue to experience disproportionate amounts of poverty, poor health outcomes, limited educational attainment, unemployment, and violent crime."
Pennsylvania Attorney General Josh Shapiro, a Democrat, said that "this was systemic racism--pure and simple. This is about real people. People who were ignored and who were harmed and left behind."
Although redlining officially ended following the passage of the Fair Housing Act in 1968, studies have shown the policy persists in practice in scores of metropolitan areas across the nation. Additionally, communities that were redlined remain predominantly minority and low-income today. A 2015 study by the National Community Reinvestment Coalition found that in Baltimore, race--and not economic status--was the most important factor in mortgage lending. Formerly redlined communities also face greater climate-related risks.
After seeing their fortunes surge during the deadly coronavirus pandemic, America's 719 billionaires are now collectively worth $4.56 trillion--making them over four times wealthier than the roughly 165 million people in the bottom half of U.S. society combined, according to a new analysis by the Institute for Policy Studies and Americans for Tax Fairness.
"It's not just during the pandemic--billionaires have been running up the score on average Americans for decades."
--Frank Clemente, Americans for Tax Fairness
The two groups found that the wealth of U.S. billionaires grew by $1.62 trillion--55%--between March 18, 2020 and April 12, 2021, a period in which millions lost their jobs and more than 500,000 Americans lost their lives to Covid-19.
The 165 million people at the bottom of the wealth distribution, meanwhile, collectively own around $1.01 trillion, far less than the nation's hundreds of billionaires.
IPS and ATF note that in 1990, "the situation was reversed"--adjusted for inflation, the bottom 50% owned $380 billion in combined wealth while the nation's 66 billionaires owned $240 billion.
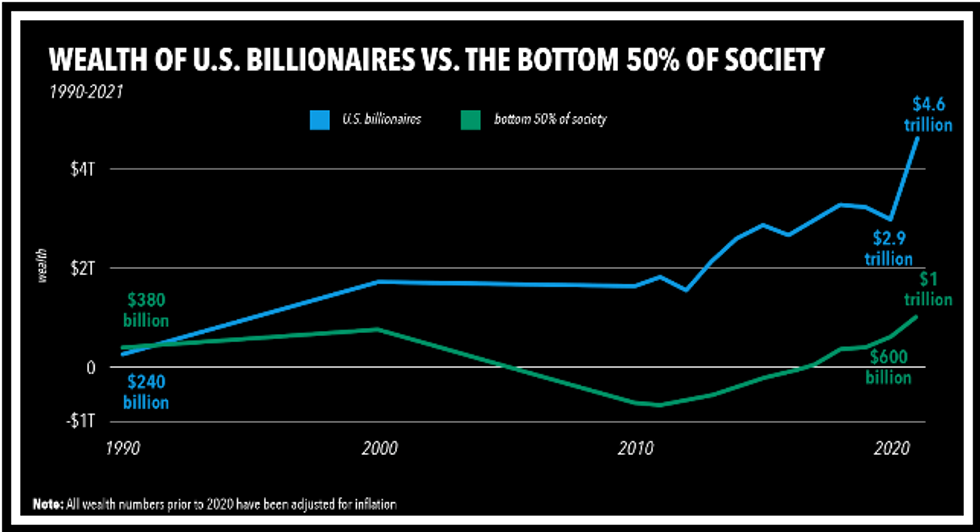
"It's not just during the pandemic--billionaires have been running up the score on average Americans for decades," said ATF executive director Frank Clemente. "The way to reverse this trend is by making sure the wealthy, and the corporations they own, start paying their fair share of taxes."
Citing Forbes wealth data, the new analysis shows that the U.S. now has six "centi-billionaires," people worth $100 billion or more:
"This pandemic billionaire wealth surge is a grotesque milestone after three decades of wealth steadily flowing to the top," Chuck Collins, director of the Program on Inequality at IPS, said in a statement. "Congress should act to restore taxes on the wealthy and limit further democracy-distorting concentrations of wealth and power."